
ARLINGTON, Va. — The high-stakes legal battle defining the future of event-contracts and prediction markets in the United States has reached a critical juncture, with industry leaders warning that the ultimate outcome will determine whether these innovative financial instruments thrive under federal oversight or vanish from the domestic landscape entirely.
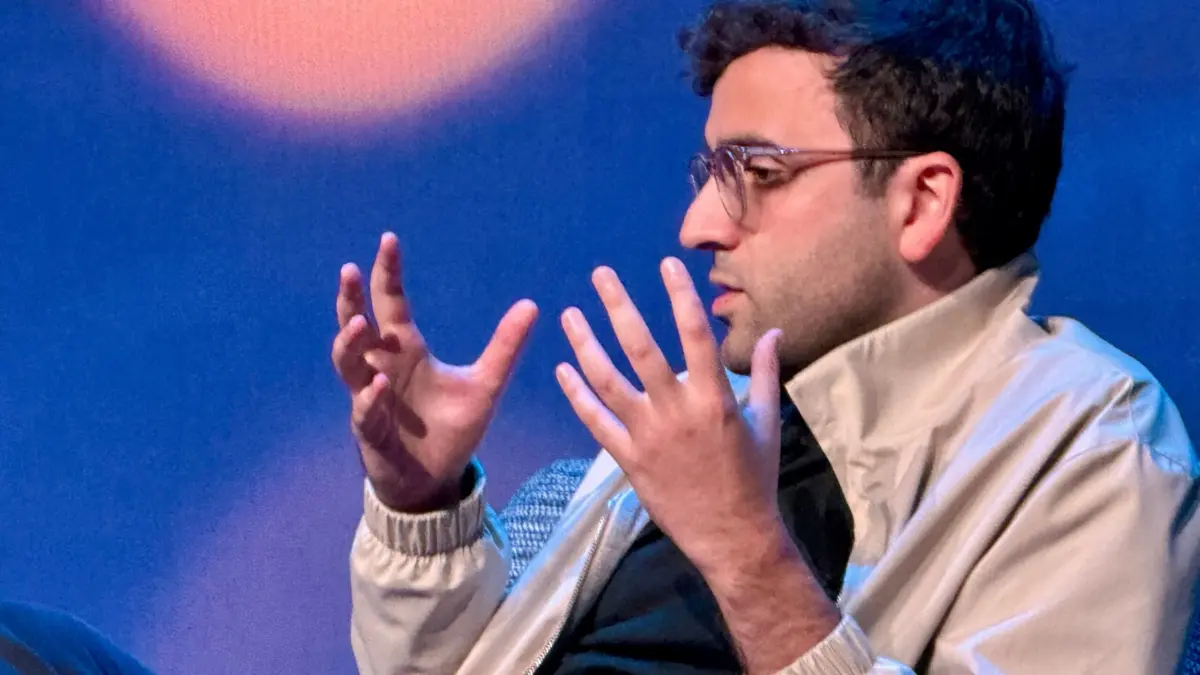
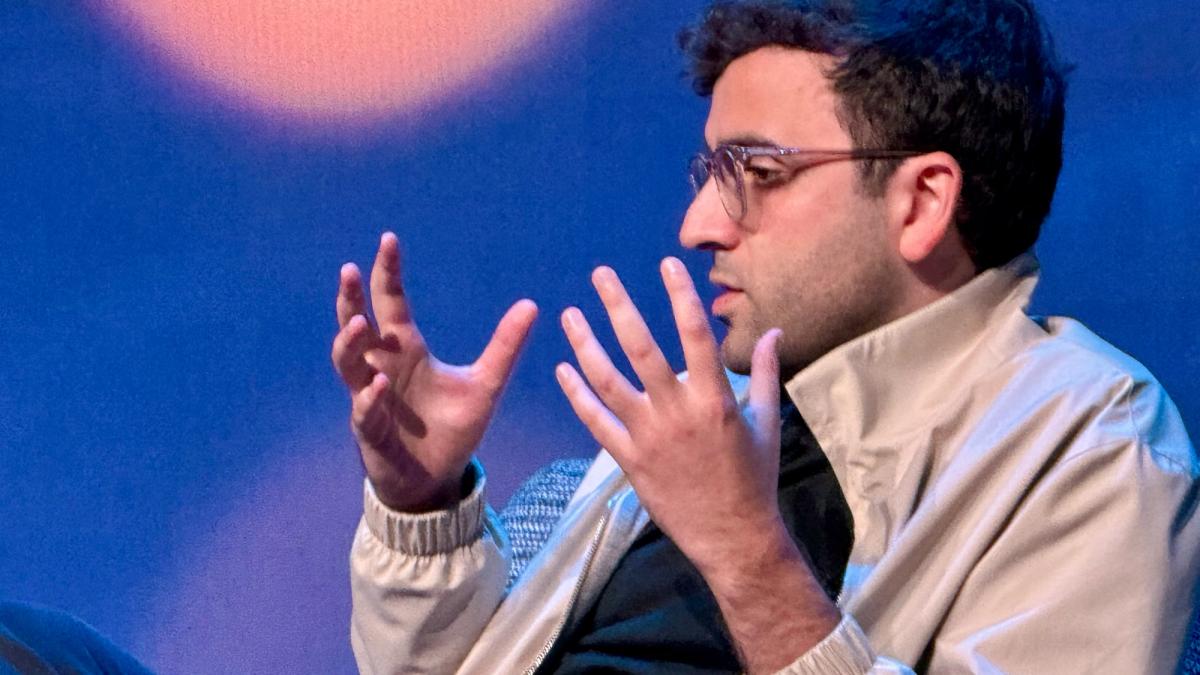
Speaking at the DC Fintech Week event near Washington, Kalshi CEO Tarek Mansour stated that he feels "pretty good" about the pending resolution of the multi-jurisdictional clash. However, he emphasized that the fundamental question at the heart of the litigation is not merely a jurisdictional tug-of-war between state and federal regulators, but a stark choice between regulated oversight within the United States or the complete migration of the industry to offshore jurisdictions.
"We feel pretty good about where we stand overall," Mansour told attendees during his appearance on Wednesday, addressing the mounting regulatory and legal pressures facing his company.
The Core Conflict: State Gambling Regulators Versus Federal Oversight
At the center of the dispute is Kalshi, a federally regulated financial exchange that has found itself locked in a fierce courtroom battle. A growing coalition of individual U.S. states has challenged Kalshi and other prediction market platforms, arguing that their rapidly expanding selection of event contracts—particularly those tied to sports outcomes—constitutes illegal sports wagering. State authorities contend that such activities fall squarely under the purview of state-level gambling and gaming regulators rather than financial watchdogs.
Conversely, Kalshi and its primary federal regulator, the Commodity Futures Trading Commission (CFTC), have pushed back aggressively in courts across the country. They maintain that the CFTC serves as the appropriate and sole federal watchdog for prediction markets, classifying these contracts as legitimate financial derivatives rather than traditional forms of gambling.
As the litigation has wound its way through the American judicial system, the legal landscape has grown increasingly fractured. The dispute has climbed to multiple federal appellate courts, resulting in a notable split among jurisdictions: one major appellate ruling has landed firmly on Kalshi’s side, while two separate rulings have backed the view of the states.
The division has raised the stakes significantly, prompting New Jersey to formally petition the U.S. Supreme Court to take up the case and resolve the split. The high-profile petition has drawn intense interest from outside groups, with prominent entities—including the National Football League—filing legal briefs to share their perspectives and push back against the expansion of prediction markets into sports-related forecasting.
Defending the Economic Significance of Sports Contracts
During his panel appearance at DC Fintech Week, Mansour addressed and rejected the core arguments raised by critics and sports leagues who claim that sports-based event contracts lack the traditional economic consequence required to justify status as federally regulated financial instruments.
The explosive growth of sports betting within the broader event-contracts space has served as a central flashpoint for opponents who argue that sports outcomes do not belong on a financial exchange. Mansour dismissed this line of reasoning directly, pointing to the massive financial footprint of the sports and entertainment industries.
"The notion that sports does not have economic consequence is ludicrous," Mansour said.
He argued that the structure of Kalshi’s offerings was carefully considered from the company’s inception, asserting that the exchange’s contracts fit neatly within long-established statutory definitions of a commodity. According to Mansour, the foundational legislation governing the space—the Commodity Exchange Act—represents a remarkably enduring legal framework that has successfully accommodated decades of economic evolution.
The statute, he noted, has historically allowed the U.S. financial system to transition seamlessly from traditional agricultural futures to complex markets involving oil and metals, and eventually to less tangible modern financial products such as swaps and event-based derivatives. From his perspective, prediction markets represent a natural extension of this evolution rather than a dangerous departure from established financial principles.
The Threat of Offshore Migration
Mansour reiterated that the ongoing legal battles carry profound implications for the broader American fintech ecosystem. In his view, a ruling against federal oversight and in favor of a fragmented, state-by-state regulatory patchwork would stifle innovation and drive capital, technology, and talent out of the country.
"It’s not a choice of state versus federal market," Mansour warned. "It’s a choice of whether prediction markets exist in the U.S. or whether they go offshore."
By forcing platforms to navigate dozens of conflicting state gambling laws, the industry could become entirely unviable domestically, pushing American users toward unregulated or foreign-based platforms that operate entirely outside the reach of U.S. consumer protection laws and federal transparency requirements.
Addressing Volume Questions and Market Maker Activity
In addition to regulatory and legal hurdles, Mansour used his appearance to address recent public scrutiny regarding trading activity on his platform. He responded to questions surrounding reports of inflated trading volumes in bitcoin and ether perpetual-futures markets on Kalshi, which had drawn attention across social media and financial news outlets.
Recent data analysis had highlighted instances of unusual, repetitive trade sizes dominating a significant portion of the volume in those specific cryptocurrency markets on Kalshi. The patterns sparked online debate and skepticism regarding the organic nature of the platform’s liquidity.
Dismissing the chatter, Mansour pointed to the noise surrounding the issue on social media channels, specifically referencing the platform formerly known as Twitter.
"There’s a lot of crazy on X," Mansour remarked.
He reiterated explanations previously provided by the company, attributing the recurring trade sizes and volume concentrations to standard, fixed-size orders executed by professional market makers rather than artificial or misleading activity. As Kalshi continues to navigate both regulatory scrutiny and high-stakes Supreme Court deliberations, Mansour remains confident that the platform’s foundational legal and operational model will ultimately prevail.