When businesses calculate their tax obligations in the United States, looking at a single figure rarely tells the whole story. Corporations operating across the country navigate a multi-layered tax environment defined by a flat federal rate combined with a diverse patchwork of state-level policies. Understanding the true tax burden requires examining how federal and state levies interact, the varying structures states use to raise revenue, and the overall impact these combined rates have on corporate competitiveness and economic growth.
At the federal level, corporations in the United States face a corporate income tax levied at a flat rate of 21 percent. This rate serves as the baseline for businesses nationwide. However, the federal government is only part of the equation. Forty-four states and the District of Columbia also impose their own taxes on corporate income, creating a complex web of overlapping jurisdictions that businesses must navigate.
These state-level top marginal rates vary significantly depending on where a company does business. On the lower end, North Carolina levies a top marginal rate of just 2.0 percent, offering a comparatively light state-level burden. On the higher end, New Jersey imposes a top marginal rate of 11.5 percent, representing the highest state corporate income tax rate in the nation.
States also differ widely in how they structure these taxes. Thirteen states implement graduated corporate income tax rates, meaning the tax percentage increases as a company’s taxable income rises. Meanwhile, a larger group consisting of 31 states and the District of Columbia levy a flat rate on corporate income, providing a predictable percentage regardless of the scale of the business’s earnings. A corporate income tax is fundamentally levied by federal and state governments on business profits. However, many companies are not subject to these specific corporate income taxes because they operate as pass-through businesses, meaning their income is instead reportable under the individual income tax system.
Beyond traditional income taxes, several states utilize alternative methods to tax business activity. In Nevada, Ohio, Texas, and Washington, corporations are subject to gross receipts taxes instead of corporate income taxes. Gross receipts taxes are applied directly to a company’s gross sales, without allowing deductions for standard business expenses such as employee compensation, the cost of goods sold, and overhead expenses. Unlike a standard retail sales tax, a gross receipts tax is assessed directly on businesses and applies to transactions at every single stage of the production process. This compounding effect often leads to what economists refer to as tax pyramiding, where the tax is levied multiple times on the same final product as it moves through the supply chain.
Other states employ a hybrid approach. Delaware, Oregon, and Tennessee impose both a traditional tax on corporate income and a separate, distinct levy on gross receipts. Meanwhile, Pennsylvania, Virginia, and West Virginia do not levy state-level gross receipts taxes, but they do permit local municipalities to levy gross receipts taxes at the local level. At the other end of the spectrum, two states—South Dakota and Wyoming—maintain a completely different approach by levying neither a corporate income tax nor a gross receipts tax at the state level.
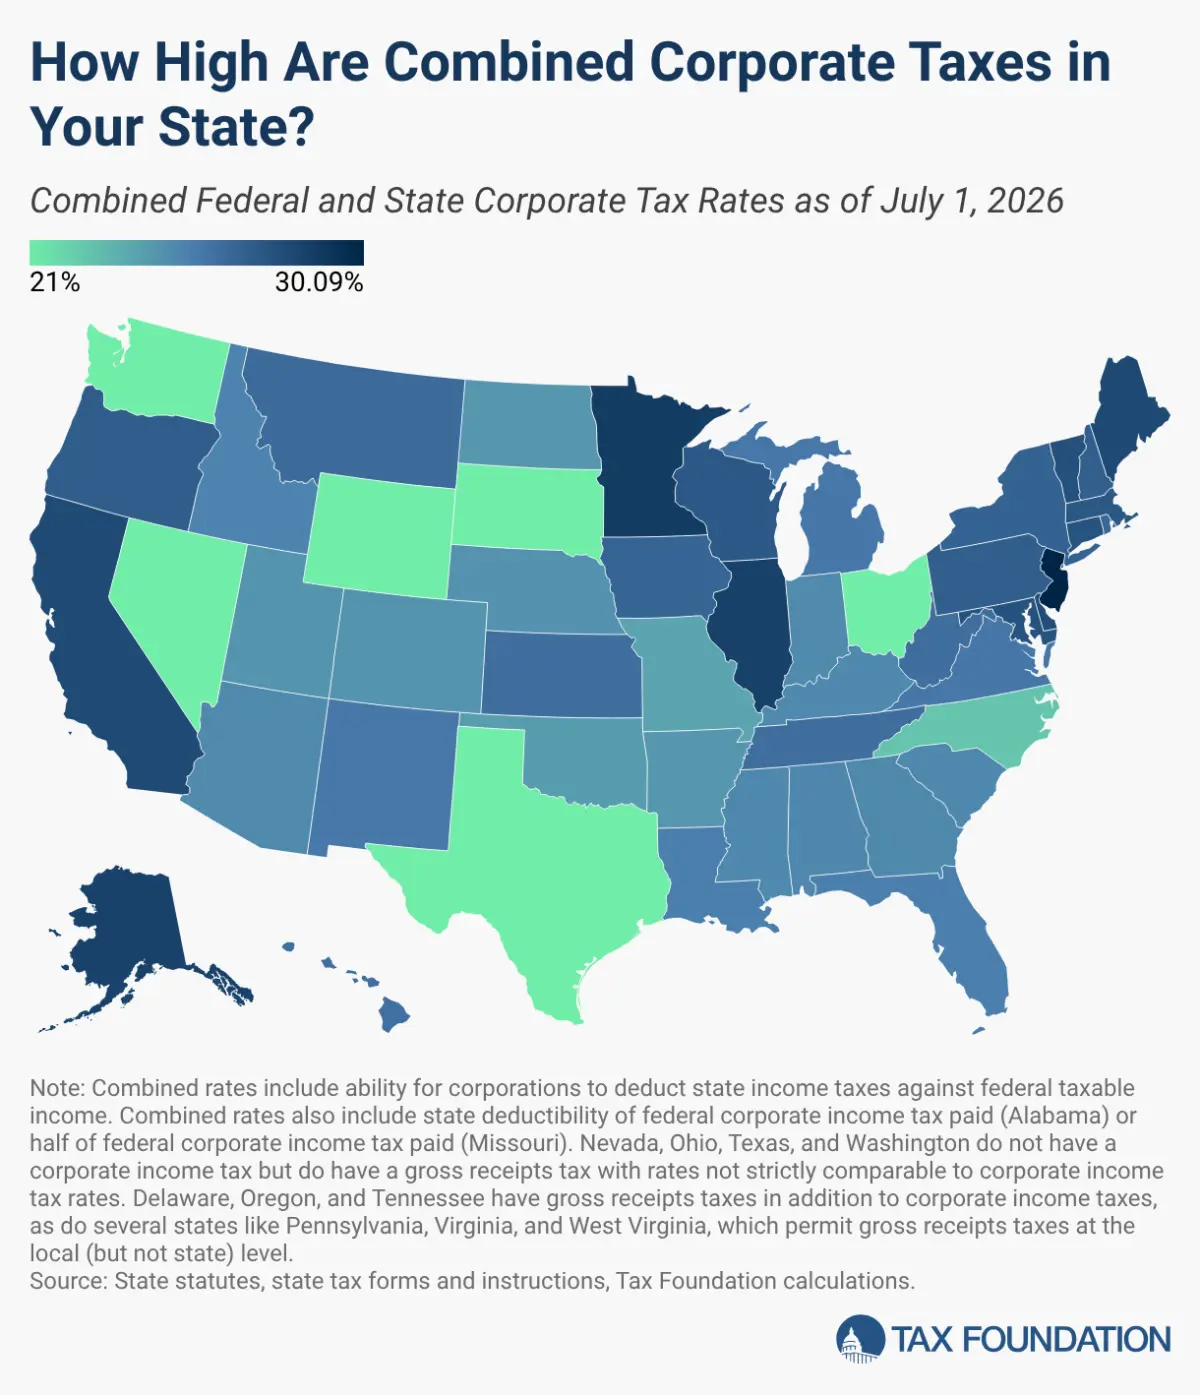
When economists and tax policy experts calculate the overall burden businesses face, they look at the combined corporate income tax rate, which accounts for both federal and state levies. New Jersey maintains the highest combined corporate income tax rate in the country at 30.1 percent, driven by its steep 11.5 percent state rate interacting with the federal system. In several other jurisdictions, including Alaska, Illinois, Maine, and Minnesota, corporations face combined corporate income tax rates at or above 28 percent.
Conversely, six states—Ohio, Nevada, South Dakota, Texas, Washington, and Wyoming—levy no state corporate income tax at all. Corporations in these states face only the federal tax rate of 21 percent, though it is worth noting that four of these jurisdictions—Ohio, Nevada, Texas, and Washington—compensate by levying statewide gross receipts taxes instead.
A critical nuance in calculating these tax burdens involves the complex interplay between federal and state tax deductions. Corporations are generally permitted to deduct state corporate income tax payments against their federal taxable income. Taxable income represents the net amount of income subject to tax after accounting for allowable deductions and exemptions, making it distinct from and lower than gross income.
Because state taxes can be deducted from federal calculations, the effective federal corporate income tax rate is reduced. For example, a corporation subject to Rhode Island’s 7 percent flat corporate income tax may deduct that state tax paid from its federal taxable income. This deduction against the 21 percent federal corporate income tax lowers the effective federal rate to 19.53 percent, resulting in a combined rate of 26.53 percent for businesses operating in the state.
In addition to federal deductions for state taxes, a small number of states offer the reverse mechanism, allowing corporations to deduct federal corporate income tax payments against a portion of their state corporate income tax liability. Alabama stands out by allowing full deductibility of federal corporate income tax liability against state liability. Meanwhile, Missouri permits a 50 percent deduction of federal corporate income tax liability. These rare provisions further lower the effective corporate income tax rate faced by corporations operating within those specific state borders.
Taking all jurisdictions into account, including the states that impose no corporate income taxes whatsoever, the average combined state and federal corporate tax rate imposed in the United States sits at 25.5 percent.
Analyzing these figures highlights why evaluating tax burdens on businesses requires a comprehensive view encompassing both federal and state corporate taxes. Economists widely view corporate income taxes as among the most economically damaging ways for governments to raise public revenue. Because capital is highly mobile, heavy corporate taxation can discourage investment, hamper business expansion, and slow wage growth for workers. Consequently, reforming corporate tax structures remains a promising area for states seeking to increase their economic competitiveness, foster a more dynamic business environment, and promote long-term growth that ultimately benefits both companies and their workforces.