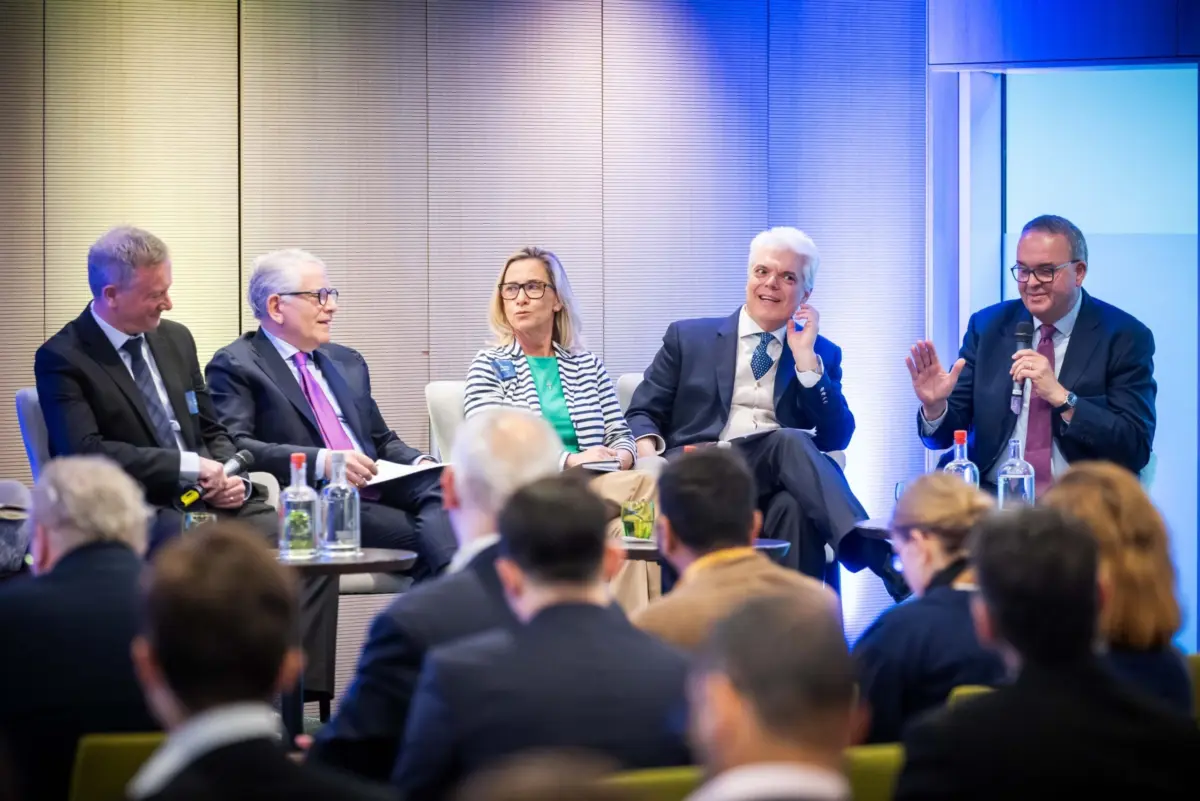
Tax professionals, policymakers, and economic analysts from across Europe and beyond have gathered to confront one of the most volatile and rapidly evolving economic landscapes in recent history. As digitalization reshapes global commerce and geopolitical tensions redefine trade routes, the fundamental mechanics of taxation are undergoing a profound transformation. This year’s high-profile conference has placed the intersection of technology, national politics, and international tax coordination at the forefront of the global economic debate, offering a comprehensive look at the forces that will govern fiscal policy for years to come.
Keynote: AI, Disruption, and the Future of Tax: Labor Revenue, Competition, and Innovation
The opening keynote set a forward-looking and urgent tone for the event, focusing heavily on the seismic impact of artificial intelligence and technological disruption on traditional tax systems. For decades, modern tax frameworks have relied heavily on labor-based revenues—income taxes, payroll contributions, and social security withholdings—to fund public services and national budgets. However, the rapid acceleration of AI and automation threatens to upend this model. As machines and algorithms increasingly replace human labor across various sectors, economists and tax authorities are grappling with an impending contraction in labor-related tax bases.
Speakers during the keynote emphasized that this technological shift is not merely a technical challenge for tax administrators, but a fundamental test of economic competitiveness and innovation. Governments find themselves caught in a delicate balancing act: they must foster an environment that encourages technological advancement and attracts cutting-edge digital enterprises, while simultaneously ensuring that their revenue streams remain stable. The discussion highlighted the complex relationship between tax policy and corporate behavior, noting that as companies evolve to rely less on physical human capital and more on intangible digital assets, traditional concepts of tax jurisdiction and value creation are being rendered obsolete. Experts underscored the urgent need for forward-thinking reforms that can accommodate the realities of the modern digital economy without stifling the entrepreneurial spirit driving innovation forward.
Session 1: How Elections Will Shape French Tax Policy
Shifting focus from technological disruption to domestic political reality, the first session of the conference tackled the intricate and high-stakes arena of French tax policy, examining it through the lens of recent and upcoming electoral outcomes. Conducted in French, the session explored the immediate and long-term implications of the new presidential administration’s tax agenda on the broader French budget and its alignment with overarching European Union priorities.
Elections are inherently pivotal moments for fiscal policy, serving as referendums on wealth redistribution, public spending, and economic stimulus. Panelists dissected how campaign promises translate into legislative reality, particularly in a nation where public debt and fiscal discipline are under intense scrutiny from Brussels. A central theme of the discussion was how policymakers can effectively navigate these domestic constraints while simultaneously making France more economically competitive on the global stage. Balancing the demands for social equity and public service funding with the imperative to lower corporate burdens and attract foreign investment remains one of the most formidable challenges facing French leadership. Furthermore, the session analyzed how France’s national tax trajectory intersects with EU-wide initiatives, ensuring that domestic reforms do not run afoul of broader European integration and harmonization goals.
Session 2: The Latest on EU Tax Policy
As the conference moved to the European level, participants received a comprehensive update on the labyrinth of regulatory developments currently moving through the Brussels pipeline. European Union tax policy is undergoing a period of unprecedented activity, driven by the need for fiscal harmonization, digitalization, and enhanced transparency among member states.
The session provided a detailed overview of the Multiannual Financial Framework (MFF) and the ongoing debates surrounding new own resources for the EU budget, which are designed to repay joint borrowing and finance strategic European public goods. Attendees were also brought up to speed on the Omnibus package, a sweeping set of legislative measures aimed at simplifying regulatory burdens and streamlining compliance across multiple sectors.
Significant attention was devoted to the Directive on Administrative Cooperation (DAC) recast, which continues to expand the scope of information exchange between tax authorities, particularly in emerging areas such as crypto-assets and e-commerce. Progress on Pillar One of the OECD/G20 inclusive framework—which seeks to reallocate taxing rights over the largest multinational enterprises to market jurisdictions—was scrutinized for its feasibility and timeline within the European context. Additionally, the discussion touched upon the Mobility Map, mapping out the future of cross-border workforce taxation and social security coordination in an era where remote work and international mobility have become the norm for a substantial portion of the European labor force.
Session 3: Investment and Competition in an Era of Trade Wars
The final session of the conference addressed the volatile macroeconomic environment characterized by rising geopolitical tensions, protectionist trade policies, and escalating trade wars. In an era where globalization is increasingly giving way to fragmentation and near-shoring, the role of foreign direct investment (FDI) is being radically reevaluated.
Panelists analyzed how foreign direct investment strategies are adapting to the implementation of Pillar Two—the global minimum corporate tax rate of 15% designed to curb a race to the bottom in corporate taxation—alongside the imposition of new tariffs and trade barriers by major economic powers. While Pillar Two aims to establish a level playing field by setting a floor for corporate tax rates, the simultaneous rise in trade protectionism introduces competing pressures that can distort investment flows and complicate supply chain management for multinational corporations.
The session engaged in a robust debate over what constitutes healthy tax competition in a post-Pillar Two world. Without the traditional tool of aggressive corporate tax rate cuts to lure foreign investors, nations are being forced to compete on other merits, such as infrastructure, workforce education, regulatory efficiency, and targeted innovation incentives. Experts evaluated how developing and developed economies alike are repositioning themselves to remain attractive destinations for capital in a fractured global marketplace, concluding that the future of international tax competition will rely far more heavily on structural economic strengths rather than fiscal maneuvering alone.