Marking a major personal milestone, the creator behind the popular Financial Independence Podcast recently celebrated ten full years since leaving the traditional workforce. Reflecting on a decade of post-Financial Independence (FI) life, the milestone offers a rare and candid look at the realities of early retirement, the psychological hurdles of transitioning from intense wealth accumulation to spending, and the unexpected challenges of navigating an uncharted future.
Looking back on ten years of freedom, the overwhelming emotion remains deep gratitude. Being entirely removed from the corporate grind has allowed for an immense amount of family time, particularly the ability to witness milestones and be an active, everyday presence in the lives of growing children. Beyond the domestic sphere, the passage of time has brought a profound sense of financial security, especially when viewed through the lens of modern technological shifts.
As a former software developer, the host reflected on how the industry has drastically transformed over the past decade, particularly with the rapid evolution and integration of artificial intelligence tools like Claude Code. While exploring these technologies out of personal curiosity and a love for building things, the reality of their market impact is undeniable. If survival and ongoing investing still relied on a traditional software developer salary, there would be genuine cause for concern. Having achieved financial independence long before the current wave of AI disruption has removed that anxiety entirely, serving as a powerful reminder of the unpredictability of the modern job market.
This economic uncertainty has also shaped a new perspective on traditional retirement planning philosophies, specifically regarding the debate between lean FIRE and fat FIRE. Looking back, the unintentional drift into a more robust financial cushion proved far more advantageous than sticking strictly to a bare-bones lean FIRE lifestyle. For those currently climbing the corporate ladder—particularly software developers in high-paying positions who are not entirely miserable—the advice is to reconsider rushing out the door at the absolute minimum threshold. Building an extra layer of financial security is increasingly prudent given the shifting macroeconomic landscape and the uncertain future of white-collar employment. Furthermore, embracing a slightly more expansive budget has unlocked a level of lifestyle enjoyment that far exceeds initial expectations.
From an external standpoint, daily life may not look extravagant, but the fundamental shift has been entirely psychological. Operating with the underlying knowledge that the investment portfolio can comfortably sustain an upper-middle-class lifestyle without ever needing to monitor prices or worry about daily expenses has freed up an extraordinary amount of mental energy. Rather than pursuing ultra-luxury purchases like private aviation or yachts, the true benefit lies in frictionless daily choices—whether that means enjoying premium morning coffee without a second thought or treating the family to appetizers and desserts at dinner.
Experimenting with higher spending over the years led to a profound realization: money is rarely the ultimate limiting factor anymore. Instead, constraints are dictated by time, personal energy, and the practical realities of family life. Dining out with young children, for instance, naturally limits how often and where a family eats, making a relaxed neighborhood pub far more appealing than an expensive Michelin-starred establishment. Similar constraints apply to travel and home improvements, where the hassle of transit and physical space naturally govern consumption rather than financial limitations.
This evolution in mindset mirrors financial philosophies championed by personal finance expert Ramit Sethi, whose advice initially sounded counterintuitive during past interviews. Concepts such as spending more instead of less, seeking out the highest quality items in rare categories of interest, and making peace with financial waste began to make complete sense with time and maturity. Letting go of a hyper-efficient mindset—a trait deeply ingrained in both programming and early financial planning—has been one of the most liberating mental adjustments of post-FI life.
Embracing this philosophy showed up clearly during recent travel experiences, including major trips to Canada and Italy. In previous years, rigid adherence to itineraries and sunk costs would have forced the family to push through extended vacation days even after the high point of the trip had passed. By choosing to book one-way tickets home early when a trip naturally reached its emotional peak, the family prioritized happiness over optimization, ultimately saving money on accommodations while preserving fond, unexhausted memories.
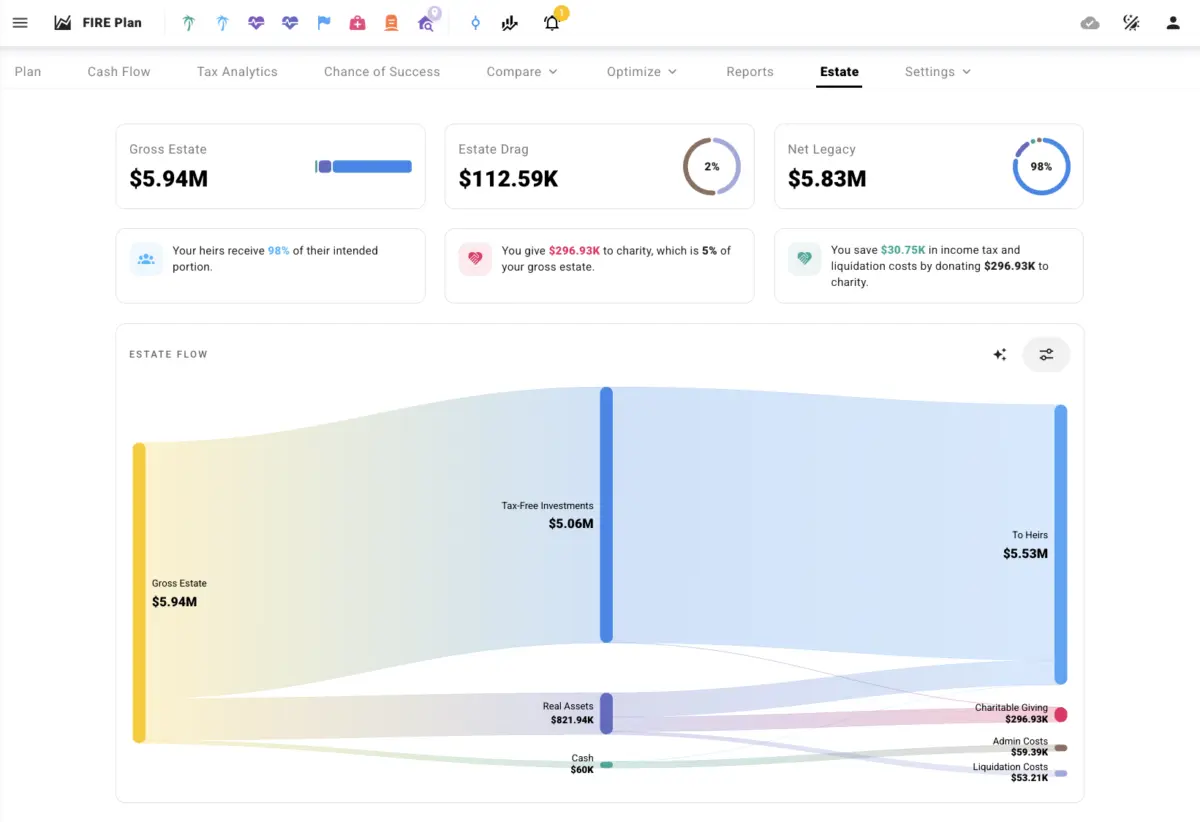
These mental adjustments inevitably led to a gradual increase in annual spending. However, unlike traditional lifestyle creep driven by salary raises—which can become perilous if employment is suddenly lost—asset-driven lifestyle creep is fundamentally sustainable. When spending power grows organically alongside a expanding portfolio, such as a modest bump enabled by the classic four percent rule, it provides a permanent, inflation-adjusted increase in lifestyle quality. This realization served as the inspiration for developing Wealth Machines, a software project designed to help individuals better visualize and utilize their excess capital to enhance present-day living rather than hoarding wealth indefinitely for a distant future.
Simultaneously, the past decade has brought a deliberate shift away from complex financial optimization in favor of simplicity. While meticulous tax strategies like backdoor Roth contributions and hyper-optimized portfolios were hallmarks of early blogging days, the mental overhead they introduce is no longer deemed worthwhile. Streamlining investments into a few permanent funds eliminates unnecessary administrative burdens and keeps financial tracking effortless.
In a similar vein of risk management, a recent portfolio adjustment involved reallocating a portion of equities into thirty-year Treasury Inflation-Protected Securities (TIPS). With real yields hovering near historical highs of around three percent, these bonds establish a reliable spending floor designed to mature precisely as standard retirement age arrives and required minimum distributions from tax-deferred accounts begin. This measured step allows the core wealth machine to run largely on autopilot, requiring nothing more than occasional, routine rebalancing.
Despite enjoying a highly sustainable and comfortable daily routine, the household’s spending still falls safely below the portfolio’s maximum capacity. This surplus has sparked ongoing discussions about how best to utilize remaining resources to further enrich the family’s quality of life during peak parenting years. With parents and grandparents still healthy and children at an age where they actively enjoy spending time together, maximizing the present moment is paramount. Consequently, exploring a potential relocation to a dream home base—one characterized by great weather, high walkability, and strong community roots—has emerged as a primary focus for the next fifteen years.
The goal of this prospective move is to establish a strong gravitational pull for the family, creating a welcoming, beautiful environment where children will naturally want to return during adulthood. Whether the ideal location centers on outdoor mountain activities, a vibrant coastal town, or close proximity to extended family and friends, the upcoming years will involve exploratory living arrangements and long-term rentals to find the right fit.
Reaching this stage of life also brings an entirely new psychological landscape. Having successfully achieved all long-term financial and personal goals that originally motivated the pursuit of independence, the horizon is remarkably clear. For someone accustomed to driving toward distant milestones, operating without a grand long-term plan feels unfamiliar yet deeply liberating. The focus has decisively flipped from engineering an ideal future to maximizing the present day, replacing grueling cardio workouts with enjoyable games of tennis and prioritizing shared memories over future-proofing.
Ten years removed from the traditional workforce, the journey of financial independence has evolved from a strict mathematical exercise into a dynamic, intentional way of living. By successfully bridging the gap between wealth accumulation and present-day enjoyment, the last decade has proven that financial freedom ultimately serves its true purpose when it grants the time, space, and peace of mind to fully engage with the people and experiences that matter most.