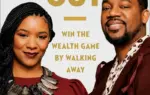


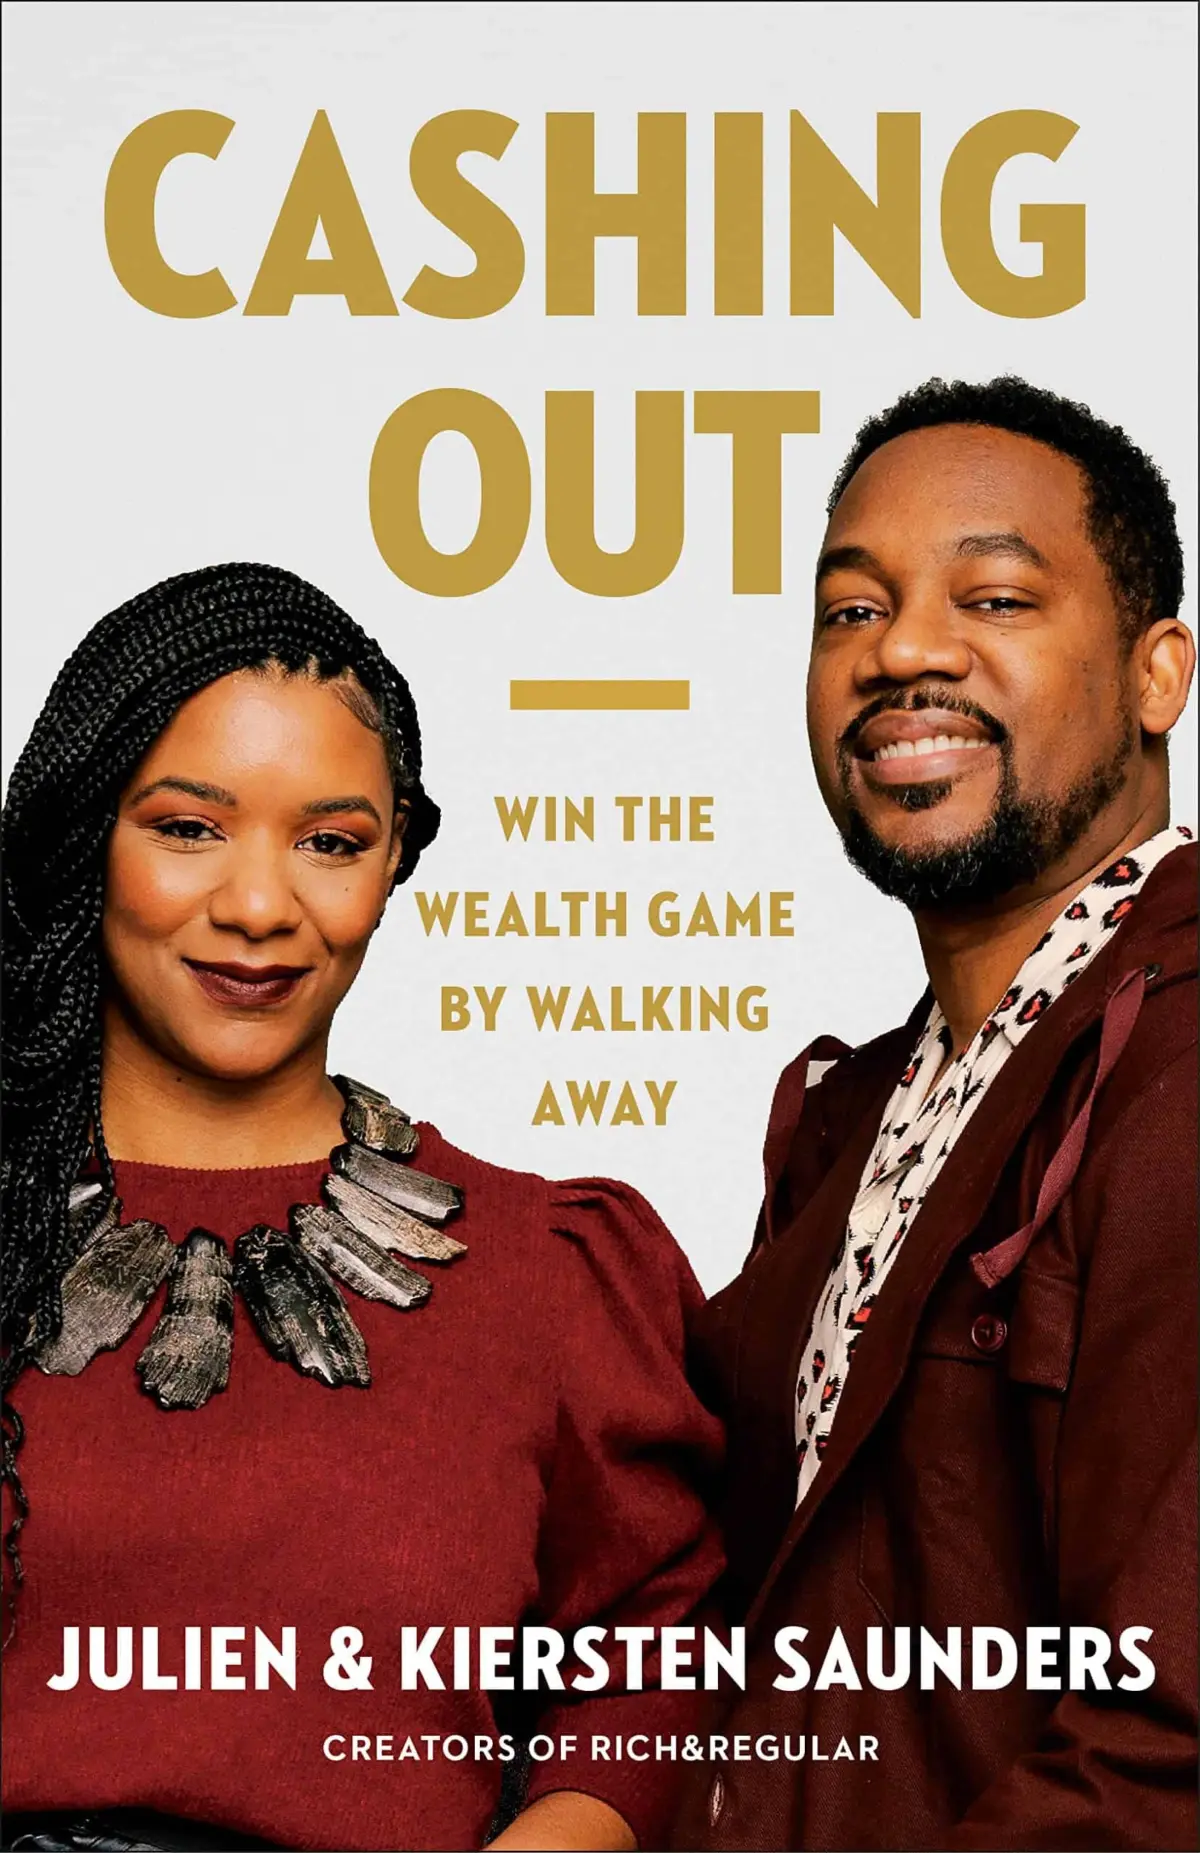
The "Get Rich Slowly" summer book series concludes with a compelling excerpt from Cashing Out: Win the Wealth Game by Walking Away, written by Julien and Kiersten Saunders. The authors, recognized as the power couple behind the prominent rich & Regular blog and YouTube channel, offer a fresh perspective on how romantic partners navigate personal finance. Published by Portfolio/Penguin, the book provides practical insights into transforming traditional marital money disputes into collaborative partnerships.
Drawing on concepts from clinical psychology, the authors examine why financial conversations frequently devolve into conflict and how couples can fundamentally alter their communication patterns.
At the heart of their philosophy is a concept borrowed from Dr. Sue Johnson, a clinical psychologist who specializes in emotionally focused therapy. According to Dr. Johnson, when couples argue—regardless of the specific subject matter—they are engaging in a predictable dance. One partner makes a move, and the other responds in kind. In this framework, the dance itself is always the problem, rather than the individuals involved or the topic they are debating.
By shifting attention toward these interaction patterns, partners can begin to observe the rhythm that defines their conflicts. Developing the instinct to recognize when to reach out and connect requires what Dr. Johnson terms emotional attunement.
If interpersonal conflict resembles a dance, emotions serve as the music. Emotional attunement means both partners can hear the same song, or at the very least, acknowledge that multiple songs may be playing simultaneously. Communication breaks down when partners attempt to move together while operating under completely different internal rhythms.
When couples spend years avoiding financial discussions, they effectively attend a silent disco where everyone is moving independently without hearing the underlying audio. To establish attunement, partners must first recognize how unresolved financial anxieties manifest emotionally within the relationship.
Name-Calling: Conversations About Spending
Over years of engaging with hundreds of couples regarding personal finance, the authors note that spending habits generate the most frequent friction. Disagreements often arise over visible consumption patterns, such as one partner questioning the volume of new acquisitions arriving at the front door compared to the other’s extensive wardrobe.
In many cases, one partner brings the other to a financial advisor or coach because traditional communication has failed. They express frustration that standard explanations do not resonate. During these consultations, participants frequently rely on labels, categorizing one person as a saver and the other as a spender.
This dichotomy carries an inherent moral judgment. The saver is often framed as the responsible decision-maker, while the spender is cast as irresponsible and in need of correction. However, the authors argue that this binary perspective fails to reflect economic reality.
Saving and spending are ultimately fluid concepts separated primarily by time horizons. Spenders allocate resources for immediate gratification in the present, while savers set aside capital to spend at a later date. For instance, an individual who saves twenty thousand dollars over the course of a year to purchase a vehicle with cash transitions from a saver to a spender depending entirely on the timeframe in question.
Achieving emotional attunement begins by removing these rigid labels and replacing judgment with curiosity. Successful financial conversations require eliminating the notion of villains and shifting the paradigm from a framework of good versus bad to a perspective centered on now versus later.
Whenever money is spent, an individual is typically chasing an underlying emotional need—whether seeking security, spontaneity, or pleasure. Once partners recognize that both share the fundamental desire to experience positive emotions, the conversation shifts away from assigned personas toward objective problem-solving. The ultimate objective is not merely reaching a compromise, but achieving a state of harmony where both individuals express themselves in a way that supports the collective relationship.
Nagging: Conversations About Saving
Beyond spending disagreements, persistent nagging regarding saving habits can severely strain a relationship. Continuous warnings about accumulating wealth often put the receiving partner on the defensive, eroding objectivity over time.
Constant financial surveillance creates conversational fatigue. When reminders about money blend seamlessly with everyday domestic requests, they begin to sound like a broken record. If the tone remains uncorrected, the recipient may conclude that the underlying criticism targets their character rather than the financial balance.
Attunement in this area relies on reframing the conversation. Because saving is essentially planning future consumption, focusing on future plans can act as a release valve for high-pressure dynamics. Anticipation provides positive psychological benefits, and shared optimism proves far more reliable than sheer willpower.
When the authors needed to curtail dining out to save for a future vacation, they recreated the culinary and cultural experience of their intended destination at home. By cooking themed meals, playing local music, and watching travel videos, they transformed a restriction into a shared anticipation, building discipline while maintaining connection.
Blaming: Conversations About Debt
Financial disparities, particularly when one partner enters a relationship with significantly more debt than the other, frequently generate resentment and insecurity. Constant reminders of outstanding balances can trigger deep shame, leading the indebted partner to internalize the debt as a personal moral failure. Conversely, the partner without debt may harbor resentment regarding their perceived obligation to contribute toward its resolution.
For Kiersten Saunders, the shame surrounding her initial debt triggered defensiveness and reliance on avoidance tactics common to her conflict-resolution style. Initial conversations felt like personal attacks. Overcoming this hurdle required both partners to let go of preexisting expectations—Kiersten abandoning the notion of being rescued, and Julien relinquishing judgment regarding past financial choices.
By combining finances and confronting debt collaboratively, the couple learned to navigate frugality and flexibility simultaneously. While some couples may choose to manage debt separately due to specific loan forgiveness rules or personal preference, emotional attunement remains essential to ensure both partners feel aligned in their overarching financial strategy.
"Tell Me More"
To foster constructive dialogue during charged financial discussions, the authors recommend using the phrase "tell me more" when clarification is needed. This simple prompt signals a desire for context and encourages further expression without resorting to judgment.
Harsh language and criticism function similarly to a sudden scratch on a record player, halting the conversational flow instantly. Conversely, inviting elaboration encourages vulnerability and risk-taking within the relationship.
However, the authors emphasize a critical caveat regarding the timing of such phrases. Curiosity cannot coexist with feelings of threat and intimidation. Following early financial disclosures, rebuilding trust took considerable time, and intense emotional moments required patience rather than conversational pressure. Preserving the relationship’s emotional foundation often takes precedence over forcing an immediate resolution, ensuring the partnership remains resilient for future discussions.