By Jabran Kundi
September 23, 2026
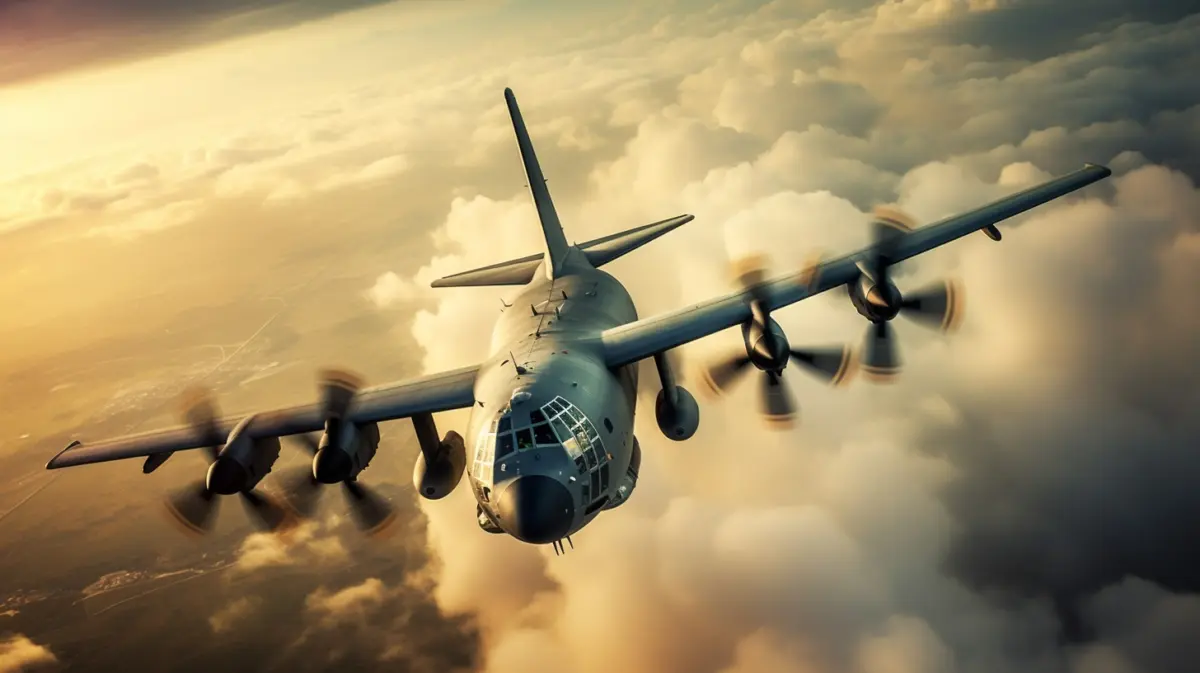
In a significant move to bolster U.S. air superiority in an era of intensifying global competition, Lockheed Martin Corporation (NYSE: LMT) has entered into a landmark framework agreement with the U.S. Department of War. Announced on September 17, 2026, the agreement is designed to accelerate the production of the AIM-260 Joint Advanced Tactical Missile (JATM), a weapon system widely regarded as the most sophisticated air-to-air missile in the American arsenal. While the partnership signals a robust institutional commitment to the platform, the development serves as both a strategic win and a fiscal litmus test for the defense giant as it navigates the complexities of congressional funding and shifting geopolitical requirements.
The AIM-260 JATM is not merely an incremental upgrade; it represents a fundamental shift in how the U.S. military intends to counter emerging air threats, particularly those originating from China. As the Pacific theater becomes a primary focus for defense planners, the demand for longer-range, highly maneuverable, and stealth-compatible weaponry has skyrocketed. The JATM is specifically engineered to provide a critical technological edge, offering extended range and superior targeting capabilities compared to the long-serving AIM-120 AMRAAM. Its compatibility with the F-22 Raptor and the F-35 Lightning II makes it a cornerstone of the future of U.S. tactical air power.
For Lockheed Martin, the framework agreement acts as a vital "demand signal," indicating that the Department of War views the JATM as a high-priority procurement item. However, the path to full-scale production remains fraught with the typical hurdles of the modern defense acquisition cycle.
Lockheed Invests Ahead of a Multiyear JATM Contract
One of the most notable aspects of this agreement is Lockheed Martin’s willingness to shoulder the financial burden of capacity expansion before a formal multiyear procurement contract is even signed. By self-funding investments in production infrastructure, the company is effectively betting on the program’s long-term viability. This proactive approach is intended to ensure that, once the political and budgetary green lights are finally illuminated, the manufacturing lines are already prepared to meet the high-volume requirements of the military.
Tim Cahill, president of Lockheed Martin Missiles and Fire Control, acknowledged the significance of the development, noting that the program—which has long operated under a veil of secrecy—is finally stepping into the public consciousness. "We’re proud to finally talk about the extraordinary work behind this missile and how we’re working with the U.S. government to rapidly scale production," Cahill stated. His comments reflect a broader organizational shift toward transparency regarding next-generation capabilities, likely intended to reassure stakeholders and investors that the company is at the vanguard of the Pentagon’s modernization efforts.
The momentum behind the JATM extends beyond domestic interest. The program recently reached a critical milestone by securing Australia as its first international customer, with the Australian government committing approximately A$736 million to the initiative. This international buy-in is a significant validation of the missile’s capability and strategic necessity. Furthermore, the framework agreement coincides with other positive developments for Lockheed Martin, including a recent Indefinite Delivery/Indefinite Quantity (IDIQ) contract ceiling for the Army’s PrSM (Precision Strike Missile) Increment 2. These combined successes underscore a clear, strengthening trend in global demand for advanced missile systems, positioning Lockheed Martin as a primary beneficiary of the ongoing shift toward high-tech, long-range munitions.
A Demand Signal Without a Final Multiyear Contract
Despite the optimism surrounding the announcement, industry analysts remain cautious. The framework agreement, while promising, is not a guarantee of future revenue. It functions more as an expression of intent rather than a binding, multiyear procurement contract. Crucially, the agreement requires the explicit approval of Congress, a hurdle that has become increasingly complicated in the current political environment.
The absence of a disclosed dollar value or specific production targets in the initial announcement has left many observers wondering about the concrete economic impact. Reports from The Aviationist and Military Times have highlighted these missing details, noting that without a finalized contract, the precise timeline for production remains fluid.
For investors, this creates a distinct set of risks. Simply Wall Street has cautioned that Lockheed Martin’s strategy of self-funding capacity expansion—while necessary to maintain production schedules—introduces potential execution and inventory risks. If the anticipated demand from the U.S. government fails to materialize as expected, or if Congress scales back funding in the face of broader federal debt concerns, the company could find itself with excess capacity and capital tied up in assets that are not generating immediate returns.
Furthermore, the defense industry is currently under a microscope. The Motley Fool has pointed to growing bipartisan criticism on Capitol Hill, where some lawmakers have expressed frustration with major defense contractors. Specifically, there is rising scrutiny regarding the tendency of large firms to prioritize share buybacks over the timely delivery of hardware. In an era of record federal deficits, defense spending is being subjected to intense debate, with legislators increasingly demanding accountability for every dollar spent. This political climate adds a layer of uncertainty to any program that has not yet reached the stage of a fully funded, multiyear contract.
Market Sentiment and the Path Forward
The financial market’s reaction to these developments has been nuanced. Data regarding hedge fund activity shows a cooling trend, with the number of hedge funds holding positions in Lockheed Martin dropping from 83 at the end of the first quarter of 2026 to 75 by the end of the second quarter. This decline suggests a period of re-evaluation among institutional investors, possibly due to the broader macroeconomic environment or a wait-and-see approach regarding the company’s massive capital investments.
However, the bearish sentiment is not overwhelming. As of August 31, 2026, short interest in Lockheed Martin remained modest at 1.39% of the float. This suggests that while there is some hesitation, there is not a significant movement betting against the stock’s performance. The market appears to be balancing the long-term strategic importance of the JATM program against the immediate risks of federal budgetary constraints and the timing of the next phase of the contract.
Ultimately, the trajectory of Lockheed Martin’s stock in the coming months will be inextricably linked to the legislative process. The framework agreement has set the stage, but the transition from a strategic vision to a funded, high-volume production reality rests in the hands of Congress. For now, Lockheed Martin is positioning itself as the indispensable partner in the U.S. government’s effort to maintain its technological lead in the air, betting that its proactive investments will be rewarded when the political and financial pieces of the JATM puzzle finally click into place. Until that formal contract is signed, the industry and the investor community alike will be watching the halls of Congress as closely as they watch the production lines.