For more than eight decades, Securities and Exchange Commission (SEC) Rule 14a-8 has served a simple yet transformative purpose in American corporate governance. By providing a structured, federal mechanism for everyday owners to place questions of corporate accountability directly before their fellow shareholders, the rule has functioned as a cornerstone of shareholder democracy. Today, however, that longstanding framework faces an existential threat. A controversial SEC proposal to rescind Rule 14a-8 entirely—framed by regulators as a measure of systemic reform—promises to do the exact opposite of what reform implies. Instead of refining the process, the proposal would effectively eradicate the federal forum where vital debates regarding corporate behavior, risk management, and governance occur.
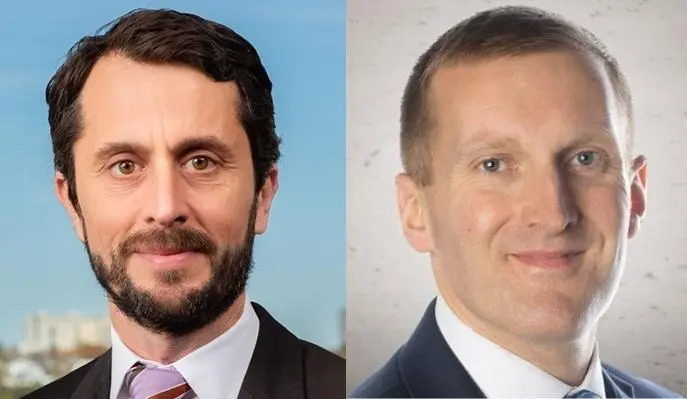
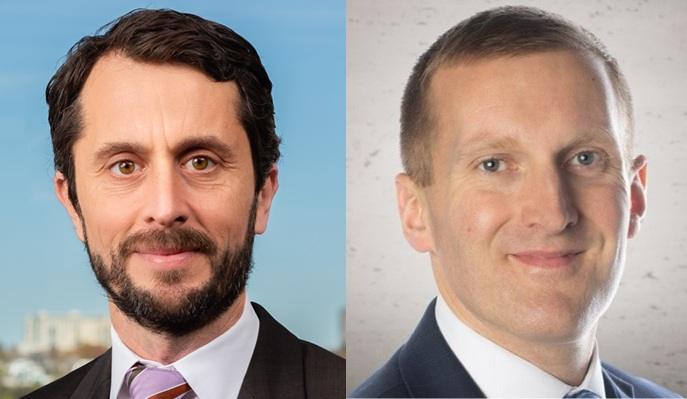
This looming regulatory shift has sparked deep concern across the investment community, particularly among institutional and faith-based investors who have relied on the proxy process for generations to guide corporate stewardship. Matthew Illian, Director of Responsible Investing, and Noah Tabor, General Counsel, at United Church Funds, have voiced sharp opposition to the Commission’s trajectory. In their view, while the administrative process surrounding shareholder resolutions has always experienced friction, the correct path forward involves thoughtful modernization rather than outright demolition. The SEC, they argue, would be far better served by preserving meaningful investor access to company proxy materials while actively addressing the operational inefficiencies that have long frustrated stakeholders on all sides of the debate.
A Long History of Shareholder Engagement
To understand what is at stake in the current debate over Rule 14a-8, one must look back at how the mechanism has been deployed throughout modern economic history. For decades, the rule has acted as a primary bridge between corporate management and the individuals and institutions who hold an ownership stake in public companies. Critics and supporters alike have often found reasons to be frustrated by the Commission’s administration of proposal eligibility. Some participants have historically argued that the agency has permitted too many peripheral resolutions onto corporate ballots, while others have contended that regulators have unjustifiably excluded matters of genuine and legitimate shareholder concern.
Despite these persistent imperfections and occasional administrative disagreements, Rule 14a-8 has successfully provided a functioning, predictable framework for investor engagement and corporate accountability for the better part of a century. The historical record demonstrates that the proxy process is not merely a modern ideological battleground, but a proven tool for addressing material business risks.
During the 1970s, for instance, faith-based investors utilized Rule 14a-8 to submit groundbreaking shareholder resolutions urging major U.S. corporations to cease their operations in South Africa as a moral and economic protest against the severe human rights abuses of the apartheid regime. In the decades since, faith-based institutional investors have continued to leverage the proxy process to address an evolving array of corporate risks. These have included pressing companies to manage hazards related to single-use plastics, worker safety standards, data privacy protocols, and various other operational vulnerabilities. Because these concerns directly affect a company’s day-to-day operations, public reputation, and long-term financial value, proponents argue that the rules governing shareholder proposals must preserve meaningful access. This access ensures that fellow shareholders have the opportunity to assess a proposal’s merits independently and decide whether to cast their votes in support.
Governance Reforms and Board Accountability
Beyond operational and environmental risks, faith-based and institutional investors have long utilized Rule 14a-8 to champion fundamental corporate governance reforms. United Church Funds and similar institutional participants have regularly filed shareholder proposals seeking to separate the dual roles of Chief Executive Officer and board chair at several major companies, arguing that independent board leadership provides essential oversight.
Furthermore, the proxy process has been the vehicle of choice for advancing proposals ensuring that corporate directors stand for reelection every single year rather than serving staggered terms, and that directors are required to resign if they fail to secure majority support from their shareholders. These governance reforms, alongside many others, enjoy broad support across a diverse spectrum of the investor community. Over the years, they have evolved into critical mechanisms for improving corporate transparency, reducing agency costs, and holding corporate boards strictly accountable to their true owners.
If shareholders are stripped of this federally protected route to place such vital governance issues directly into company proxy materials, the practical opportunities to advance these reforms will diminish drastically. Without a standardized federal mechanism, investors will find it exponentially more difficult to challenge entrenched management structures or demand meaningful board accountability.
The Fragmented Legal Landscape of State-Level Barriers
Rescinding Rule 14a-8 would not create a regulatory vacuum; rather, it would throw corporate governance into a fragmented and potentially confusing landscape governed primarily by state laws and individual company governing documents. Without a uniform federal standard, access to company proxy materials would become heavily dependent on local jurisdictions, opening the door to a patchwork of restrictive state-level regulations.
Already, early indicators of this fracturing legal environment are visible. Texas has adopted an opt-in law that allows certain publicly traded corporations domiciled or operating within the state to impose significantly higher barriers to entry for shareholder proposals. These stringent state-level requirements include mandates that proponents must own—either individually or as part of a coordinated group—at least $1 million in voting shares or 3% of the company’s total voting shares. In addition, the Texas framework enforces strict holding-period prerequisites and complicated solicitation requirements.
For many institutional investors, smaller funds, and faith-based organizations, such prohibitive financial and procedural barriers could render meaningful participation nearly impossible and prohibitively costly. The substitution of a uniform federal standard with a chaotic web of state-by-state restrictions threatens to price ordinary investors out of the corporate democracy process entirely.
The Urgency of the Public Comment Period and the Call for Public Hearings
The ultimate timeline, trajectory, and final impact of any rescission of Rule 14a-8 remain shrouded in uncertainty. The future of the rule could be heavily influenced by ongoing legal challenges from investor coalitions, shifting political agendas, and the evolving legislative forces emerging out of recent midterm elections.
In the face of this regulatory uncertainty, investor advocates emphasize that market participants must act immediately to make their voices heard. With the public comment period drawing to a close on November 20, 2026, concerned investors have been urged to submit formal comment letters opposing the total rescission of the rule. United Church Funds has already submitted its own comments opposing the move, maintaining that all investors who value corporate accountability should make their positions known to regulators.
However, industry leaders argue that for a regulatory shift of this historical magnitude, the Commission’s standard practice of merely soliciting written comments falls woefully short. Instead of operating behind closed doors, the SEC should hold open public hearings or interactive roundtables to thoroughly examine the practical, real-world consequences that a rescission would impose on both investors and public companies.
Modernizing the Framework Rather Than Demolishing It
Rather than pursuing a destructive, wholesale elimination of Rule 14a-8, critics of the SEC proposal suggest that genuine regulatory reform should focus on addressing the process’s actual administrative costs and historical inconsistencies. Policymakers should instead look for structural solutions capable of enduring the inevitable swings of political change.
In their formal comment letter, representatives from United Church Funds proposed a constructive alternative: evaluating an independent Shareholder Proposal Review Service operating under a retained federal framework. Under this model, a time-limited working group composed of diverse investors, corporate executives, SEC staff, and legal and dispute-resolution experts could examine how such a specialized service might help resolve proposal eligibility disputes promptly, fairly, and affordably. Any serious evaluation of this concept would naturally need to establish the service’s lawful scope, strict independence, and broad accessibility.
Ultimately, the Commission should pursue practical, sensible improvements to the existing system while fiercely preserving the foundational ability of shareholders to put specific, material concerns before their fellow owners. That careful, collaborative work—not an abrupt and sweeping rescission—is where federal regulators should direct their focus. The central question before the market is not whether Rule 14a-8 is a flawless instrument, but rather whether investors and companies are better served by maintaining a functioning forum for corporate accountability or by operating with no federal forum at all. Reform the process, modernize it, and improve its efficiency—but do not demolish it.