The concept of Financial Independence (FI) often revolves around rigorous saving, diversified stock portfolios, and careful adherence to safe withdrawal rates. However, seasoned practitioners of the FI lifestyle frequently emphasize that building wealth involves more than just traditional investments. For years, travel miles and credit card points have functioned as a shadow portfolio—a secondary asset class capable of significantly supplementing a standard FI nest egg.
Recent tracking data shared by prominent personal finance figures highlights the substantial, tangible financial impact that strategic credit card use can yield over time. By looking at a multi-year ledger, the monetary value extracted from travel rewards reveals a surprisingly lucrative secondary revenue stream. Historical tracking shows an annual accumulation of value that began at $2,614 in 2019 and climbed through subsequent years, hitting $4,401 in 2020, $6,080 in 2021, and $6,192 in 2022. Following a temporary dip to $648 in 2023, the returns surged dramatically to $10,593 in 2024, before registering $4,253 in 2025 and $5,917 in 2026.
Averaging out these figures demonstrates a consistent yield of over $5,000 per year in direct financial value. Through the lens of standard Financial Independence math—specifically utilizing a traditional 4% safe withdrawal rate—generating $5,000 annually in travel and lifestyle value is the mathematical equivalent of holding an additional $127,175 in a traditional investment portfolio. In essence, optimizing everyday spending habits and travel rewards eliminates the need to accumulate more than one hundred thousand dollars in invested capital to achieve the same lifestyle outcome.
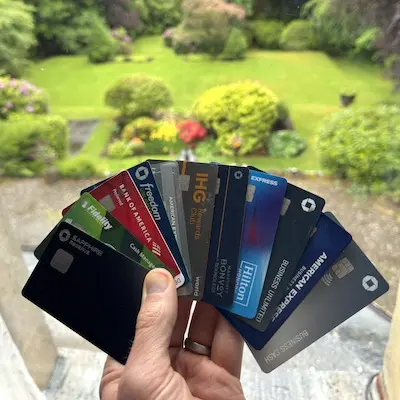
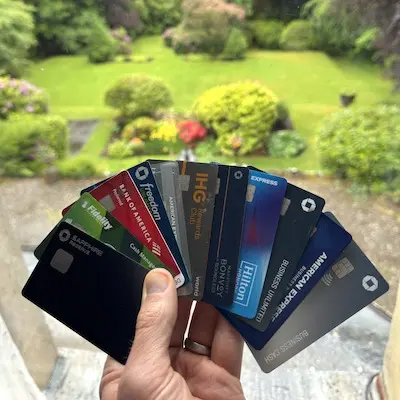
While the broader mechanics of traditional FI portfolios are widely discussed, examining the actual tools kept in a consumer’s wallet provides a clearer picture of how this secondary portfolio is practically managed. Over the years, many financial optimizers shift their strategy away from constant card churning toward simplification. Rather than chasing every newly released sign-up bonus or maximizing fractional percentage gains across a dozen rotating cards, a settled, minimalist approach often proves more sustainable and equally rewarding.
At the center of this streamlined wallet strategy sits the Chase Sapphire Reserve, a premium travel card that commands the vast majority of daily consumer expenditure. Acquired shortly after its initial market launch in 2016, this card has remained the primary payment vehicle for more than 95% of transactions. Industry valuation experts, such as those at The Points Guy, frequently value these transferable points at approximately 2.05 cents each. Consequently, earning elevated multipliers on major expenditure categories—such as 4x points on flights and hotels, and 3x points on dining—translates to an effective return of over 8% and 6% back, respectively, on a household’s largest recurring budget items.
Beyond point accumulation, premium travel cards offer immediate logistical and financial relief during transit. Complimentary airport lounge access, for instance, frequently saves travelers substantial sums per airport visit, depending on local pricing at terminals lacking dedicated airline spaces. More importantly, these amenities transform stressful transit days into relaxed, predictable experiences. Recent structural updates to premium cards, which accompanied annual fee adjustments, have introduced a suite of targeted lifestyle perks. For disciplined spenders, these credits have unlocked thousands of dollars in added utility, effectively offsetting the higher cost of card ownership while encouraging intentional spending on high-value experiences.
Complementing the primary rewards card in the wallet is a vital tool designed for international travel and domestic banking flexibility: the Fidelity Cash Management Debit Card. While this product does not accrue travel miles or reward points, it serves an indispensable function by removing foreign transaction fees and offering unlimited worldwide ATM fee reimbursements. When traveling abroad, this card eliminates the cumbersome and costly process of exchanging physical currency at traditional exchange kiosks or banks. Instead, cardholders can withdraw local currency directly from foreign ATMs immediately upon arrival, securing superior interbank exchange rates with zero administrative friction. Domestically, the universal reimbursement policy transforms any automated teller machine into a fee-free banking terminal, liberating consumers from the necessity of hunting down specific brick-and-mortar branch locations.
Alongside these core offerings, a select group of secondary cards occupies specific niches within the wallet. A traditional banking debit card remains in reserve for localized cash withdrawals near specific home branches. For everyday domestic spending outside of travel and dining, the Chase Freedom Unlimited provides a reliable baseline, earning 1.5 points per dollar on all purchases. When evaluated at a valuation of 2.05 cents per point, this equates to an effective 3% cash-back equivalent on general merchandise without imposing an annual fee, securing its status as a permanent fixture in the rotation.
Grocery expenditures in the United States are routed through dedicated supermarket cards like the Amex Everyday, which returns 2 points per dollar on everyday food retail purchases. Meanwhile, legacy hotel credit cards—such as legacy IHG Select products, Chase Marriott Bonvoy Boundless, and basic Hilton Honors American Express cards—are strategically retained despite narrow usage parameters. Even when restricted strictly to brand-specific lodging purchases, these accounts often justify modest annual fees by delivering an annual free night award that far outweighs the yearly cost of card maintenance.
In the small-business sector, streamlined options with zero annual fees dominate the portfolio. The Chase Ink Business Unlimited serves as a primary commercial card by offering a flat 1.5 points per dollar on all business expenditures. Similarly, the Amex Business Blue provides competitive earning structures on early commercial spending tiers when business owners wish to diversify their point balances across different reward ecosystems, while legacy cards like the Chase Ink Business Cash are retained quietly for their lack of annual overhead.
The true financial potency of these rewards strategies, however, is most clearly demonstrated through the detailed utilization of premium card perks. Recent adjustments to high-tier credit card offerings have introduced substantial statement credits and lifestyle benefits that require active management to maximize. Rather than acting as mere marketing gimmicks, these credits can significantly subsidize luxury travel, fine dining, and entertainment when integrated into an intentional lifestyle plan.
For travelers utilizing updated premium perks, statement credits can transform standard weekend getaways. For instance, booking upscale urban accommodations can trigger substantial hotel statement credits, which are frequently paired with daily dining vouchers for adjoining restaurants and property-wide credits for food and beverage purchases. Additional entertainment credits can be applied toward major cultural events, professional sporting fixtures, and live music concerts. Furthermore, crossing high annual spending thresholds can unlock substantial airline credits and elite status upgrades, which translate directly into eliminated baggage fees and accelerated boarding privileges.
When compiling the total financial impact—factoring in hotel credits, dining statement credits, entertainment allocations, airline incidentals, and lounge access savings—the aggregate return on a single premium card can easily surpass several thousand dollars annually. This return is generated largely through natural spending on goods and services consumers would purchase regardless, supplemented by occasional discretionary upgrades that enrich overall lifestyle quality.
Ultimately, the accumulation of travel miles, points, and strategic card perks functions as a sophisticated financial instrument. By viewing these rewards not merely as vacation discounts, but as a legitimate secondary portfolio capable of generating thousands of dollars in annual value, individuals pursuing Financial Independence can effectively reduce the capital requirements of their core investment nest egg, proving that smart financial management extends far beyond the traditional stock and bond markets.