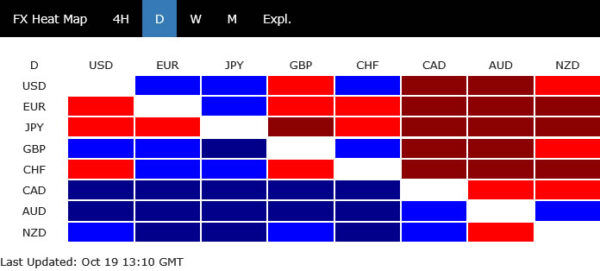
Global currency markets opened the week with a distinct divergence, as the Australian and Canadian dollars surged to lead the major currencies. However, analysts emphasize that these strong performances are far from evidence of a broad risk-on rally across global financial markets. Instead, currency strength is being driven by highly selective, localized catalysts rather than any generalized improvement in global risk appetite. While commodity-linked currencies found solid footing early in the week, European equities faced sharp declines, and French government bond yields edged perilously close to the critical 5% threshold, highlighting a fragmented and uneven macroeconomic environment.
Across asset classes, the fragmentation is glaringly obvious. The Australian, Canadian, and New Zealand dollars occupy the stronger end of currency performance rankings. Conversely, the Japanese yen and Swiss franc are lagging behind, while the U.S. dollar sits comfortably near the middle of the pack. At the same time, major European indices are deep in the red. Germany’s DAX has fallen by 1.29%, France’s CAC 40 has lost 1.44%, and Britain’s FTSE 100 is lower by 1.21%. Crude oil prices have retreated slightly, and industrial metals are displaying mixed results. This stark contrast between regional equity losses and select currency gains underscores that traders are reacting to isolated fundamental developments rather than diving blindly back into risk assets.
Aussie Surges on Stronger China Growth and Persistent RBA Tightening Bets
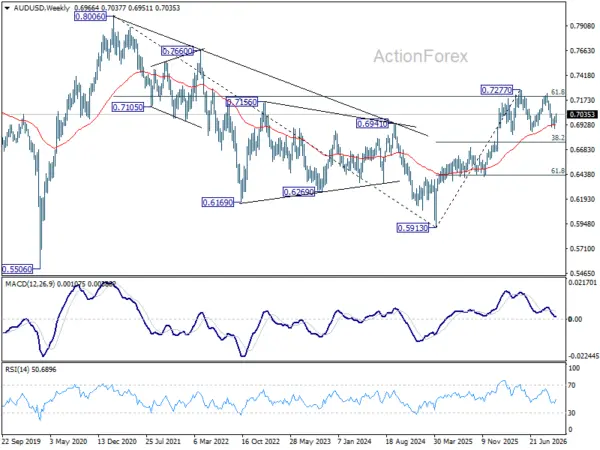
The Australian dollar claimed the crown as the day’s strongest major currency, extending its advance well beyond the U.S. dollar. The Aussie outperformed the euro, Canadian dollar, New Zealand dollar, and yen alike. These broad-based gains strongly suggest that domestic Australian developments, heavily reinforced by better-than-expected economic data from China, are providing far more fundamental support than the broader, more ambiguous global currency environment.
Recent data releases from Beijing point toward firmer economic momentum in the world’s second-largest economy. China’s third-quarter gross domestic product grew by 4.5% year-on-year, beating the forecasted 4.4% and improving upon the previous quarter’s 4.3%. Meanwhile, September retail sales rose by 1.1% year-on-year, topping expectations of 0.5% and accelerating from the prior reading of 0.4%. Industrial production also showed resilience, expanding by 5.5% year-on-year to beat the 5.4% forecast and improve upon the previous 5.2%. While these figures suggest a healthier economic pulse, economists note that persistent weakness in China’s property sector and fixed-asset investment continues to place a soft ceiling on the overall breadth of the recovery.
Adding wind to the Australian dollar’s sails, recent commentary from Reserve Bank of Australia Assistant Governor Christopher Kent has effectively challenged market assumptions that the central bank’s interest rate tightening cycle has definitively ended. Kent acknowledged growing signs that neutral interest rates are rising both domestically and globally, which could render the current 4.60% cash rate far less restrictive than previously assumed. Describing monetary policy as merely "somewhat restrictive," Kent questioned whether the existing degree of policy restraint is truly sufficient to tame persistent inflation pressures.
Nevertheless, Kent’s hawkish undertones were tempered by the recognition that Australia’s labor market is loosening at a pace faster than the RBA had anticipated. September employment figures showed a surprise contraction of 39,300 jobs, while the national unemployment rate ticked up to a five-year high of 4.7%. This sudden labor market deterioration has naturally cooled expectations for an immediate back-to-back rate hike. Even so, Kent’s assessment makes it clear that further tightening cannot be completely dismissed by market participants.

Current financial market pricing assigns roughly a 25% to 30% probability to another rate increase at the upcoming November policy meeting. While a further rate hike is certainly not the baseline expectation, the lingering possibility remains meaningful, especially if upcoming inflation prints prove stubborn. Australia’s upcoming quarterly consumer price index report on October 28 will serve as a critical test for the currency ahead of the RBA’s November 2–3 monetary policy meeting.
Canadian Dollar Holds Firm Despite Softer Core Inflation and Energy Support
The Canadian dollar has also enjoyed a resilient session, outperforming several of its peers despite receiving a mixed signal from domestic inflation data. Canada’s headline consumer price index for September accelerated from 3.0% to 3.1% on an annual basis, falling just short of market forecasts pointing to 3.2%. More importantly for monetary policy, all three of the Bank of Canada’s closely watched core inflation measures unexpectedly eased. The CPI-trim index declined from 1.9% to 1.8%, the CPI-median dropped from 2.0% to 1.9%, and the CPI-common measure softened from 2.6% to 2.4%. All three core metrics came in below economist expectations.
The notable divergence between headline and underlying inflation was driven almost entirely by the energy sector. Gasoline inflation accelerated sharply from 22.8% to 27.8%, pushing overall energy inflation up from 15.4% to 19.0%. However, when stripping out gasoline, Canada’s core CPI slowed from 2.4% to 2.2%, reinforcing the broader narrative of moderating underlying price pressures despite the headline increase caused by energy markets.
The Canadian dollar initially weakened in the immediate aftermath of the data release, though the market reaction proved remarkably contained. The USD/CAD exchange rate drifted higher from approximately 1.4077 ahead of the figures to 1.4105 shortly afterward, while the broader U.S. Dollar Index also registered a modest gain. Crucially, Canadian government bond yields did not experience a corresponding sell-off, signaling that the inflation surprise failed to trigger an immediate, broad-based reassessment of domestic interest rate expectations.
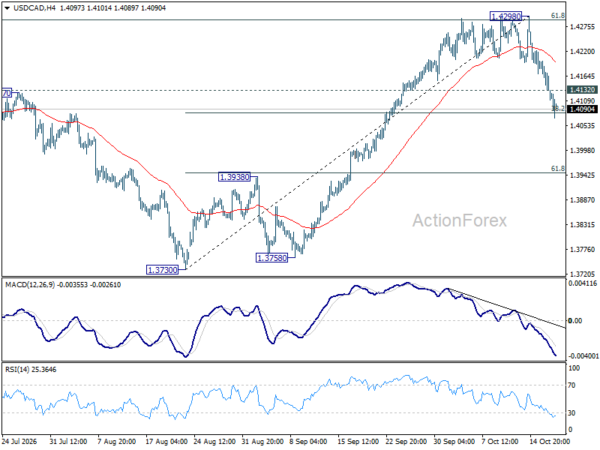
From a technical perspective, USD/CAD is currently testing the 38.2% retracement level of the broader upward wave from 1.3730 to 1.4298, located right around 1.4081. The currency pair has managed to find decent support near this technical floor, with the softer CPI print capping further downside momentum without validating a convincing bullish reversal for the U.S. dollar.
Furthermore, the loonie continues to draw substantial structural support from elevated crude oil prices. Although Brent crude retreated somewhat during Monday’s trading session, its impressive rally over preceding weeks remains a massive tailwind for Canada’s primary energy-exporting economy. With the Bank of Canada widely anticipated to hold interest rates steady at its upcoming October 28 policy gathering, the central question for traders is whether softer underlying inflation will eventually weigh more heavily on the currency, or if commodity-related inflows will continue to insulate the loonie against domestic economic cooling.
Oil Market Balances Supply Disruptions Against Sanction Adjustments
Crude oil prices softened on Monday, though the pullback has done little to reverse the substantial gains accumulated during the previous week’s rally. The recent surge in energy prices was driven primarily by mounting anxieties over global supply disruptions, as heightened geopolitical tensions in the Middle East continue to introduce a thick layer of risk premium into the market. Ongoing security incidents involving commercial shipping lanes around the Strait of Hormuz, threats directed at energy infrastructure in Saudi Arabia, and renewed drone and missile strikes against Russian petroleum facilities have all kept supply availability concerns front and center for traders.
Monday’s downward correction, conversely, reflects competing market expectations that additional Russian crude could find its way back onto international markets following recent adjustments to U.S. sanctions and tariff policies. Consequently, the global oil market finds itself delicately balancing persistent supply-disruption risks against the potential for improved production availability, failing to deliver a singular, clear directional signal for the broader commodity complex.
For the Canadian dollar, this distinction holds immense importance. While elevated crude prices continue to provide a supportive backdrop for the currency, extended weakness in oil markets could gradually erode that structural advantage. The loonie’s surprising resilience in the face of softer domestic consumer inflation is notable, but sustained long-term strength will ultimately require fundamental backing that extends beyond the short-term energy rally of the previous week.
French Bond Yields Press Toward 5% Amid Rising Political and Fiscal Risks
In Europe, the overarching market sentiment remains decidedly cautious. The euro is under moderate downward pressure, with the EUR/USD exchange rate hovering near 1.1212, marking a decline of approximately 0.24%. Political developments in France have injected a fresh layer of uncertainty into an already fragile fiscal landscape, arriving precisely as the government faces crucial legislative votes regarding its upcoming national budget.
Weekend demonstrations across France over escalating living costs and educational conditions deteriorated into violent clashes in several major cities, resulting in more than 2,000 arrests and widespread property damage. In response, President Emmanuel Macron called for urgent consultations with students, teachers, labor unions, and business leaders, while simultaneously vowing to implement tougher measures to restore public order.
For financial markets, the unrest is significant less for its direct economic toll than for its ominous implications for the government’s fiscal consolidation plans. France’s minority government is already struggling to reconcile mounting public spending demands with aggressive legislative targets aimed at reining in the national deficit. The added layer of political instability threatens to severely complicate the budgetary process, reinforcing an already elevated sovereign risk premium.
Reflecting this deepening anxiety, France’s 10-year government bond yield has continued to climb, trading near 4.88% and pressing hard against the upper boundary of its recent consolidation pattern. The yield remains comfortably above its 55-day exponential moving average, vividly illustrating the stark deterioration in sentiment toward French sovereign debt since the summer months.
The closely watched yield spread between French OATs and German Bunds remains parked at approximately 145 basis points, indicating that institutional investors continue to demand substantial financial compensation for holding French risk relative to benchmark German debt. Analysts note that a sustained, aggressive widening of that yield spread would offer much more conclusive evidence of renewed France-specific fiscal distress than a simple upward drift in French yields alone.
A decisive break above the psychologically important 5% threshold would serve as a major warning sign that selling pressure within the French bond market is intensifying, particularly if it coincides with additional widening of the sovereign spread. Markets view this threshold primarily as a vital risk marker rather than a guaranteed breakout point or a rigid yield target.
Immediate catalysts for French assets loom large, starting with the National Assembly’s legislative vote on the revenue components of the 2027 budget, followed closely by Moody’s scheduled sovereign credit review of France’s Aa3 rating, which currently carries a negative outlook. Further political setbacks or an unfavorable credit rating decision could easily amplify downward pressure on French assets, whereas visible progress through the legislative budget process would offer a much-needed window for market sentiment to stabilize.
Ultimately, Monday’s global currency market performance highlights a series of isolated, idiosyncratic developments rather than a unified global risk theme. The Australian dollar is capitalizing on stronger economic momentum in China and the lingering prospect of further RBA tightening, while the Canadian dollar retains its resilience despite softer core inflation, buoyed by elevated crude oil prices.
In sharp contrast, the European landscape tells a tale of caution, where sliding equity markets and French sovereign yields pressing toward 5% underscore enduring structural financial risks. For the time being, the foreign exchange market is actively rewarding selective economic and policy catalysts, but the glaring divergence between local currency resilience and European market vulnerability serves as a strong reminder against misinterpreting the session as a widespread resurgence in global risk appetite.