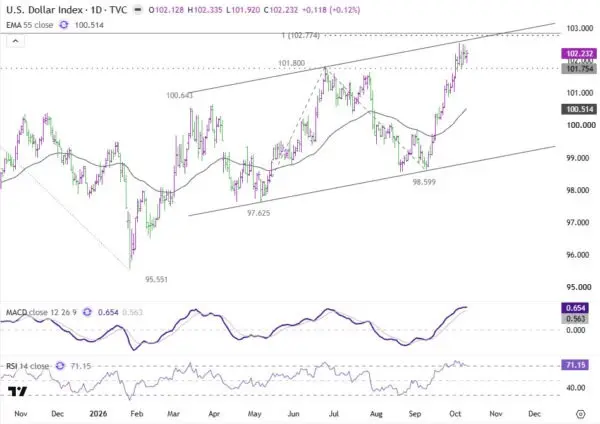
The relentless rally behind the US Dollar has hit a notable speed bump, losing its aggressive upward momentum rather than reversing its foundational direction. The US Dollar Index (DXY) recently stalled out at 102.232 after testing a high of 102.536, weighed down by a shifting macroeconomic landscape where Federal Reserve urgency has visibly cooled, long-end Treasury yields have met heavy institutional demand at two-decade highs, and European sovereign stress—specifically in France—is left shouldering a larger share of the greenback’s remaining support.
Absent a surprisingly sharp US Consumer Price Index (CPI) print, the Dollar appears increasingly vulnerable to further consolidation, with ample technical and fundamental scope to drift lower as markets look ahead to the looming midterm elections.
Why This Matters
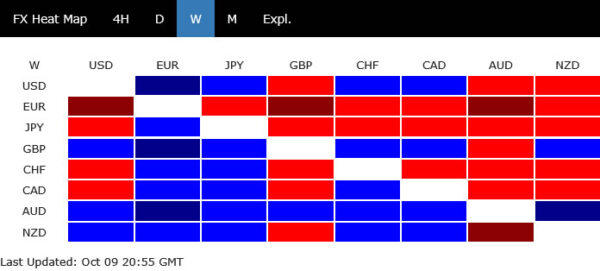
While the Dollar managed to close the week higher, it did so with markedly less conviction than earlier in its advance. The DXY touched 102.536 before retreating to settle at 102.232, failing to extend its gains even as the Euro languished as the weakest major currency on the weekly heat map. This loss of momentum does not establish a definitive top for the Dollar, but it underscores a structural shift: the three primary pillars that previously reinforced one another are beginning to diverge.
Historically, the greenback’s advance rested on aggressive Federal Reserve signaling, surging long-term yields, and steady weakness originating from the Eurozone. Today, however, Fed urgency has faded, long-term Treasury yields have pulled back from extreme highs as buyers step in at historically elevated levels, and France remains the primary catalyst for Euro weakness—though that third support increasingly depends on whether sovereign fiscal stress deteriorates further.
Unless upcoming inflation data delivers a shock large enough to reignite the rates trade, the Dollar may consolidate sideways rather than immediately resume its upward trajectory ahead of the November 3 midterms.
Fed Urgency Has Already Faded
The foundational pillar supporting the Dollar has softened more than any other. The pivot began on September 29, when New York Fed President John Williams remarked that there was "no need for urgency" following the central bank’s September rate hike, while suggesting that a single additional increase later in the year might suffice if economic conditions evolved as anticipated.
Subsequent labor market data reinforced this cautious posture. September payroll growth decelerated to just 29,000 jobs, the unemployment rate ticked up to 4.2%, wage growth slowed to a modest 0.1% month-on-month, and historical payroll estimates were revised downward.
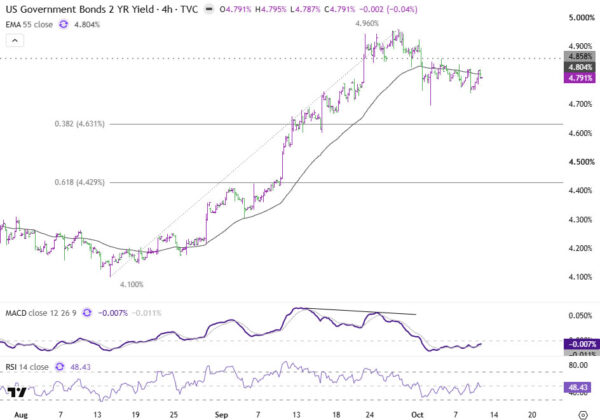
The domestic bond market quickly mirrored this sentiment. The US two-year Treasury yield peaked near 4.960% around the turn of the month before finishing the week down at 4.791%, unwinding approximately 17 basis points. Subsequent remarks from Fed Governor Christopher Waller—noting that additional rate hikes may still be required but "do not need to come at consecutive meetings"—aligned neatly with this market repricing.
Crucially, the Federal Reserve has not turned definitively dovish; rather, the urgency premium has largely evaporated from the pricing models. A back-to-back October rate hike is no longer the consensus assumption among market participants, even though subsequent tightening remains entirely possible. This distinction is vital for currency valuations. The front end of the yield curve can stop providing incremental momentum without forcing investors to price in an aggressive easing cycle. The central question for traders is no longer whether the central bank has finished tightening, but whether enough policy urgency remains to push short-term yields back toward their recent cyclical highs.
Long-Term Yields Have Started Meeting Buyers
The second pillar of the Dollar’s strength—surging long-term yields—has not broken, but it has stopped accelerating. The benchmark US 10-year Treasury yield reached a peak of 5.365% during the week before retreating to 5.242% by Friday’s close. Similarly, the 30-year yield eased from approximately 5.73% down to 5.600%. These movements represent a cooling off from extreme highs rather than an outright collapse, with the 10-year yield remaining roughly 45 basis points higher over the trailing month.
The catalyst for this shift was the market’s response to heavy Treasury debt issuance. The 10-year auction cleared at 5.300%, representing the highest auction yield recorded since 2000, yet it generated unexpectedly fierce institutional demand. The bid-to-cover ratio reached 2.77 compared to a historical average of roughly 2.51, the auction stopped through by 1.7 basis points, and indirect bidders absorbed a massive 80.3% of the total offering. The 30-year auction similarly demonstrated solid indirect demand at 72.3%, even though the overall bid-to-cover ratio dipped slightly to 2.54.
These robust auctions forced investors to confront a new reality: have US Treasury yields finally climbed high enough to organically generate their own resistance and attract long-term capital?
Pre-midterm positioning may also be playing a marginal role in tempering yields. While direct positioning data remains inconclusive, the upcoming elections carry substantial fiscal implications, particularly following proposals for large economic dividend payments and warnings from financial institutions that a political sweep could heighten fiscal risks. With November 3 fast approaching, institutional investors may be inclined to lock in historically attractive yields before domestic fiscal uncertainty deepens.
For now, the definitive takeaway is that buyers are stepping in aggressively once yields hit two-decade highs. Relative yield spreads continue to favor the US Dollar, with US-Japan and US-Canada 10-year differentials widening over the course of the week while US-Germany spreads remained largely unchanged. The Dollar has not lost its fundamental yield advantage, but the underlying mechanism has shifted from a relentless upward spiral to a dynamic where attractive yields draw substantial independent demand.
Oil Keeps the Rates Story From Turning Dovish
Crude oil continues to act as an indirect cushion for domestic interest rates rather than the direct driver of the recent Treasury yield pullback. Brent crude settled around $104.53 per barrel, remaining below September’s peak of $109.97 but still holding higher on the week. This divergence is telling: energy prices remained elevated while bond yields drifted off their highs, indicating that the Treasury correction was driven fundamentally by institutional demand for fixed income rather than any sudden alleviation of energy-driven inflation pressures.
Geopolitical developments have also introduced temporary boundaries to inflation concerns. Announcements regarding the diplomatic trajectory of discussions with Iran have placed a temporary ceiling on immediate Middle East escalation risks without resolving the underlying conflict.
Consequently, the geopolitical risk premium has been capped rather than eliminated, and this pause carries a distinct timeline tied to the domestic political calendar. Oil can continue to keep broader inflation expectations elevated without necessarily triggering an immediate secondary surge in Treasury yields, leaving markets to re-evaluate energy and macroeconomic risk pricing around the early November milestones.
France Is Carrying More of the Dollar’s Remaining Support
The third pillar keeping the greenback afloat is rooted in Europe. Persistent French sovereign fiscal stress has served as a primary driver of sustained downward pressure on the Euro. The yield spread between French OATs and German Bunds widened to roughly 159 basis points before easing back toward 135 basis points, while France’s 10-year sovereign yield pulled back from above 5% toward 4.85%.
While immediate market panic has subsided, the underlying fiscal dilemma remains unresolved. The government’s ongoing legislative efforts to narrow the national deficit from 5.4% toward 5% within a fractured parliament mean that French borrowing costs remain acutely sensitive to budgetary credibility. At the same time, persistent political uncertainty tied to longer-term electoral dynamics continues to unnerve fixed-income investors.
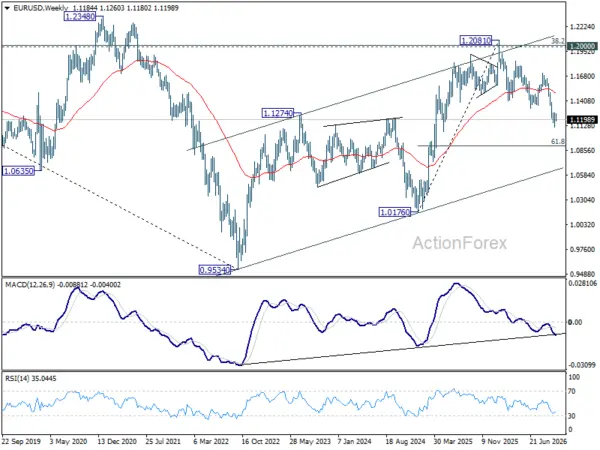
This European vulnerability keeps the Euro under pressure, helping prop up the Dollar Index through the exchange rate channel, with EUR/USD hovering near 1.12015. However, this dynamic introduces a complex secondary risk. A renewed widening of the OAT-Bund spread would typically pressure the Euro and offer a tailwind to the DXY. Yet, if European sovereign stress were to escalate to the point of triggering a flight-to-safety demand for US Treasuries, falling US yields could simultaneously strengthen rival safe-haven currencies like the Japanese Yen and Swiss Franc. Consequently, French fiscal jitters possess the capacity to lift the Dollar Index without necessarily translating into a broad, market-wide Dollar rally.
Dollar Index Is Tiring, Not Yet Topped
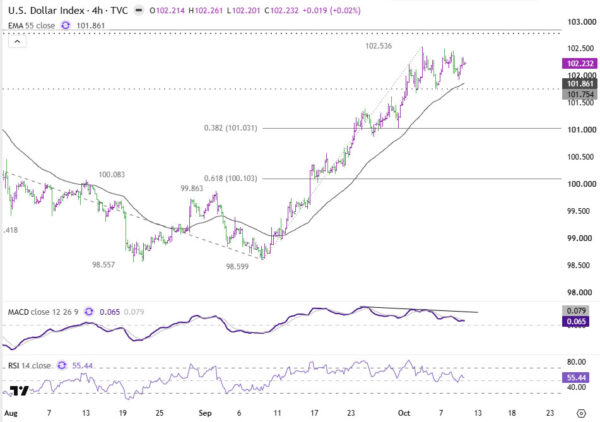
From a technical standpoint, price action on the DXY chart mirrors the broader macroeconomic narrative. The index has drifted sideways after testing the 102.536 threshold. The near-term trend retains a constructive bias as long as the 4-hour 55 exponential moving average, situated near 101.86, remains intact as support, but underlying momentum indicators confirm a loss of aggressive buying pressure.
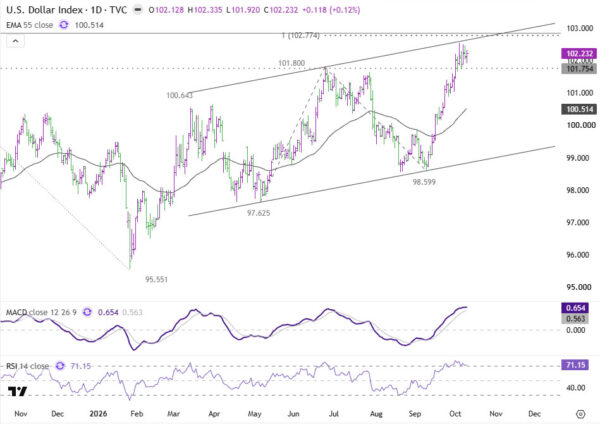
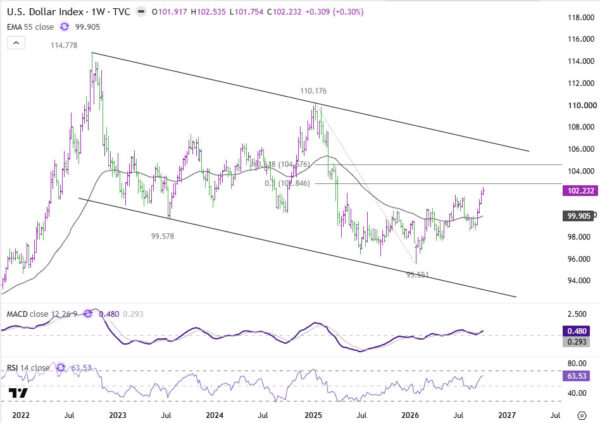
Overhead resistance is densely clustered just above current trading levels. The 100% projection of the move from 97.62 to 101.80 measured from 98.60 sits at 102.77, the 50% retracement of the larger decline from 110.17 to 95.55 is positioned at 102.84, and the upper boundary of the daily rising channel converges tightly in the 102.77 to 103.00 zone.
Momentum oscillators reflect this exhaustion, with the daily Relative Strength Index hovering at 71.15 in marginally overbought territory, accompanied by bearish divergence on the 4-hour MACD. While this combination warns that the current advance is struggling to extend itself, neither indicator provides confirmation of an impending trend reversal.
The first meaningful downside level to monitor is the 101.75 support mark. A decisive break below this threshold would suggest that a standard consolidation phase has morphed into a deeper technical correction, exposing downside targets toward the 38.2% retracement of the 98.599 to 102.536 swing at 101.03. Even a decline to this level, however, would represent a routine corrective pullback rather than validation of a major market top for the Dollar. Conversely, a sustained breakout above the 102.77 to 102.85 resistance band would invalidate the exhaustion argument and open the door for a push toward the 61.8% retracement level at 104.58.
Two-Year Yield Confirms the Loss of Momentum
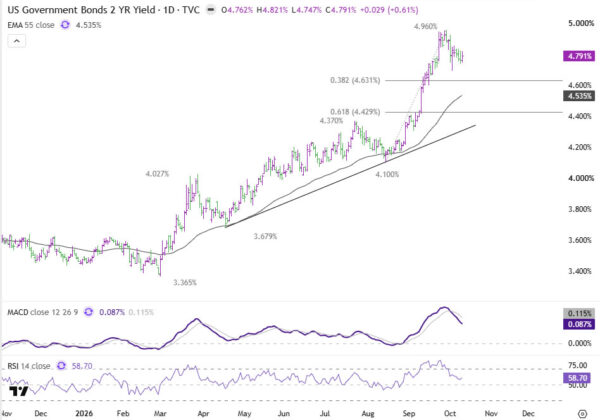
The front-end interest rate environment offers further confirmation of waning bullish momentum. The two-year Treasury yield formed a short-term peak at 4.960%, accompanied by bearish divergence on short-term MACD charts.
The yield has repeatedly encountered selling pressure around its 4-hour 55 EMA, currently parked near 4.804%. Immediate resistance stands at 4.858%, and sustaining prices below this ceiling keeps the corrective downward bias active, targeting the 38.2% retracement of the 4.100% to 4.960% range at 4.631%. A firm recovery back above 4.858% would signal that the front-end correction has concluded and put the 4.960% peak back into immediate focus.
Ten-Year Yield May Have Completed Its First Major Upswing
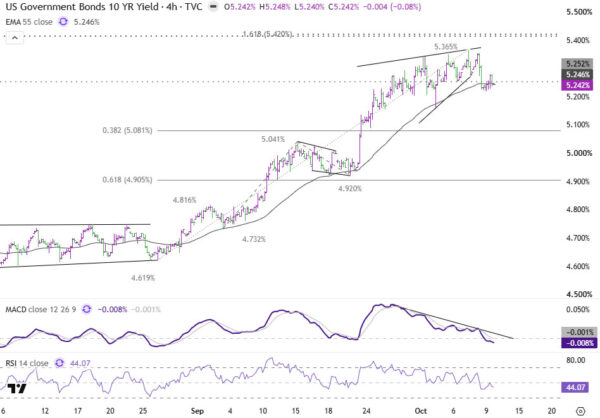
The 10-year Treasury yield presents a structurally mature technical profile. The aggressive advance from 4.619% to 5.365% can be interpreted as a completed five-wave impulse, with the final leg of the rally from 4.920% forming an ending diagonal pattern. This ascent stalled just beneath the 161.8% projection target at 5.420% before slipping below 5.252%.
Momentum across the benchmark maturity has eroded noticeably. Sustained trading beneath the 4-hour 55 EMA, currently sitting at 5.246%, will validate this topping interpretation and invite a deeper retracement toward the 38.2% retracement of the entire 4.619% to 5.365% advance, located at 5.081%. Alternatively, a decisive push through the 5.365% high would invalidate the pattern and place the 5.420% area back into play.
CPI Comes First, Then the Midterms
The immediate test for the prevailing wait-and-see market dynamic arrives with the upcoming release of US Consumer Price Index data. A softer-than-expected inflation reading could strip away lingering near-term policy tightening premiums, dragging the two-year yield toward 4.631% and pulling the DXY down toward the 101.03 support zone. Conversely, a hotter inflation print would provide the most direct catalyst for a renewed test of the 4.960% two-year yield and a fresh attempt by the Dollar Index to pierce the 102.77 to 102.85 resistance barrier.
Parallel to domestic data, European developments will remain in focus. A renewed break in the EUR/USD below 1.1159, accompanied by OAT-Bund yield spreads pushing back toward the 150 to 159 basis point range, would provide an independent source of underlying strength for the DXY even if domestic US yields remain subdued.
The late-October Federal Open Market Committee meeting follows closely behind, though with policy projections absent and markets heavily pricing in a policy hold, the gathering may prove less volatile than incoming inflation data, barring unexpected forward guidance regarding December meeting expectations. Beyond monetary policy, the focus will inevitably settle on the November 3 midterm elections, a date that has acquired heightened significance across both domestic political and geopolitical landscapes.
Rally Stalled Does Not Yet Mean Rally Over
The underlying challenge facing the US Dollar is not that its core bullish supports have vanished entirely; rather, they are no longer synchronized in their upward drive.
Federal Reserve policy urgency has cooled, the front end of the yield curve has undergone a technical correction, and long-term Treasury yields have demonstrated that significant institutional demand exists at historical extremes. While French fiscal pressures continue to provide a floor for the Euro, that stress is increasingly carrying the burden of sustaining the Dollar Index on its own.
This disconnect leaves the greenback vulnerable to an extended period of consolidation in the weeks ahead. Unless upcoming inflation figures deliver an unexpected shock, market participants appear increasingly content to await the macroeconomic and political catalysts clustered around the end of October and the early November midterms. Within that environment, a gradual drift toward 101.03 would align cleanly with the natural digestion of the previous advance. The Dollar may have lost its forward momentum, but confirming a definitive cyclical top will require considerably more technical and fundamental evidence.