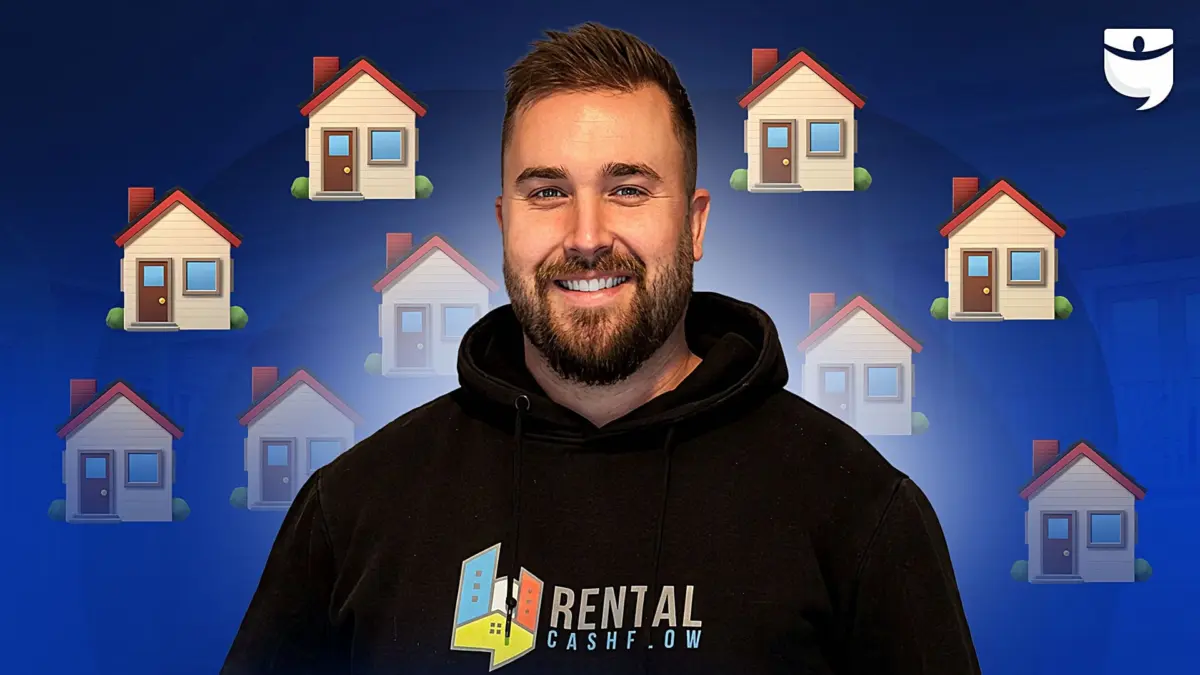
For Matt Krueger, the turning point arrived in 2014 with a sobering reality check. Working a bottom-end cellular retail sales position at a Sprint store in Des Moines, Iowa, Krueger was bringing home just $35,000 a year. He and his wife, Mariah, were barely getting by, and with a baby on the way, the financial pressure mounted quickly. Compounding the urgency was a shared family goal: Mariah wanted to be a stay-at-home mother, a lifestyle choice that seemed entirely out of reach on a modest single-income salary.
Faced with mounting financial constraints, Krueger turned to an avenue his in-laws had long advocated: real estate investing. There was just one fundamental obstacle standing in his way—he had virtually no liquid capital.
What followed was a methodical, high-sweat-equity journey that ultimately allowed Krueger to completely replace his salary, quit his W-2 job, and build a robust 12-unit real estate portfolio. Recently appearing on the BiggerPockets Podcast alongside co-host Henry Washington, Krueger detailed the exact playbook that transformed his financial standing from scraping by on a retail wage to achieving long-term portfolio independence.
Inspiration Roots and the First Acquisition
Krueger’s introduction to the wealth-building potential of real estate came directly from observing his wife’s parents. Having retired in their 50s after a career that included working as a grocery store meat cutter, his father-in-law had successfully accumulated more than 20 properties through alternative financing strategies. Seeing firsthand how real estate afforded them the freedom to spend a month each year working on property in Tucson, Arizona, left a lasting impression on the young family man.
Determined to replicate that success without a traditional war chest of savings, Krueger turned to a creative variation of house hacking. Instead of purchasing a multi-family property like a duplex or fourplex, he focused on acquiring distressed single-family homes using low-down-payment conventional loans, living in them while executing renovations, and eventually converting them into long-term rentals.
In 2015, utilizing a first-time homebuyer grant secured through a local hockey team promotion, Krueger purchased his first property—a beat-up $90,000 single-family residence colloquially known as a "grandma house." Sporting orange shag carpet in the bedrooms, wood-paneled walls throughout, and even carpet in the kitchen, the home was severely dated but structurally sound enough to qualify for conventional financing.
By offering $92,000 with the seller covering $2,000 in closing costs, Krueger brought just $2,500 of his own cash to the closing table. He leveraged sweat equity, YouTube tutorials, assistance from family members, and discount building supplies sourced from Habitat for Humanity ReStores to completely renovate the interior over the course of a year. Total renovation expenses were kept to approximately $5,000.
After fulfilling the mandatory one-year owner-occupancy requirement to satisfy mortgage guidelines, Krueger and his growing family moved a few blocks away to repeat the process on another fixer-upper. Renting out the original property for $1,200 a month against an escrowed mortgage payment of roughly $620 generated an immediate monthly cash flow of nearly $600—a financial injection Krueger described as life-changing at the time.
Scaling Through the Live-In Fixer-Upper Strategy
Over the next four years, Krueger repeated the house-hacking and renovation cycle four times. Each project involved purchasing an affordable fixer-upper requiring cosmetic updates like paint, carpet, countertops, and tile, utilizing down payments ranging from 3% to 5%, and applying aggressive personal labor to maximize the properties’ value.
The strategy, however, was not without its hurdles. Balancing family life, demanding work hours, and intense property renovations placed a heavy emotional and physical strain on the household. Krueger credits his wife, Mariah, as an indispensable partner in the venture, noting instances where she tackled intensive projects like installing tile backsplashes with an infant strapped to her back.
After completing four consecutive live-in projects, the family decided to settle down permanently on an acreage outside Des Moines. Rather than continuing to move from house to house, Krueger shifted strategies. He paused acquisitions for two and a half years, directing all incoming cash flow from his rental properties toward renovating their permanent residence, thereby building substantial equity.
When an appraisal valued their primary residence at approximately $500,000—up significantly from its purchase price of $180,000—the couple qualified for a home equity line of credit (HELOC) totaling $160,000. This credit line provided the capital needed to fuel the next phase of their investment expansion.
Pivoting into Short-Term Rentals and Quitting the W-2 Job
By 2020 and 2021, shifting market dynamics drew Krueger’s attention toward short-term rentals. Seeking a manageable entry point, he purchased his first short-term rental property locally in Des Moines for $160,000, keeping within a 30-minute radius of his home to maintain hands-on operational control.
Applying his familiar renovation methodology, Krueger invested about $25,000 into cosmetic updates and furnishings sourced from thrift stores and budget retailers. The property quickly outpaced expectations, generating $57,000 in bookings during its first year of operation.
Bolstered by this success, Krueger acquired a second short-term rental. Confident in the mathematical performance of his portfolio and having achieved a baseline cash flow that surpassed his retail salary, Krueger called his boss to resign from his W-2 job right from the parking lot of the closing office after purchasing the second property.
Rather than focusing exclusively on high-end vacation destinations, Krueger concentrated on what he calls "accommodation locations"—non-traditional vacation markets where guests frequently travel for weddings, funerals, family reunions, work trips, and holidays. By outfitting these four- and five-bedroom properties with amenities like hot tubs, game rooms, and fire pits, he positioned his rentals to capture consistent demand year-round, insulating the business from seasonal tourism slumps.
Building a Platform and Focusing on Stewardship
As his portfolio expanded to include a mix of short-term rentals, long-term single-family homes, and multi-family properties, Krueger began documenting his journey on social media under the handle @rental.cashflow. Initially launched to share educational insights and encourage everyday workers trapped in low-income jobs, his content unexpectedly evolved into a significant platform.
Today, Krueger collaborates with prominent proptech and property management brands, generating substantial revenue through his online presence while continuing to speak at industry events. Despite the monetization opportunities found in content creation, he maintains that his primary motivation remains rooted in service and family priority.
Reflecting on his progression from a $35,000-a-year retail employee to a seasoned real estate investor, Krueger’s portfolio currently stands at 12 rental units, encompassing short-term rentals, long-term single-family homes, and a multi-family fourplex. While he evaluates potential future ventures into self-storage or commercial real estate, his foundational mission remains unchanged: maintaining financial stability, growing purposefully, and prioritizing time as a husband and father.