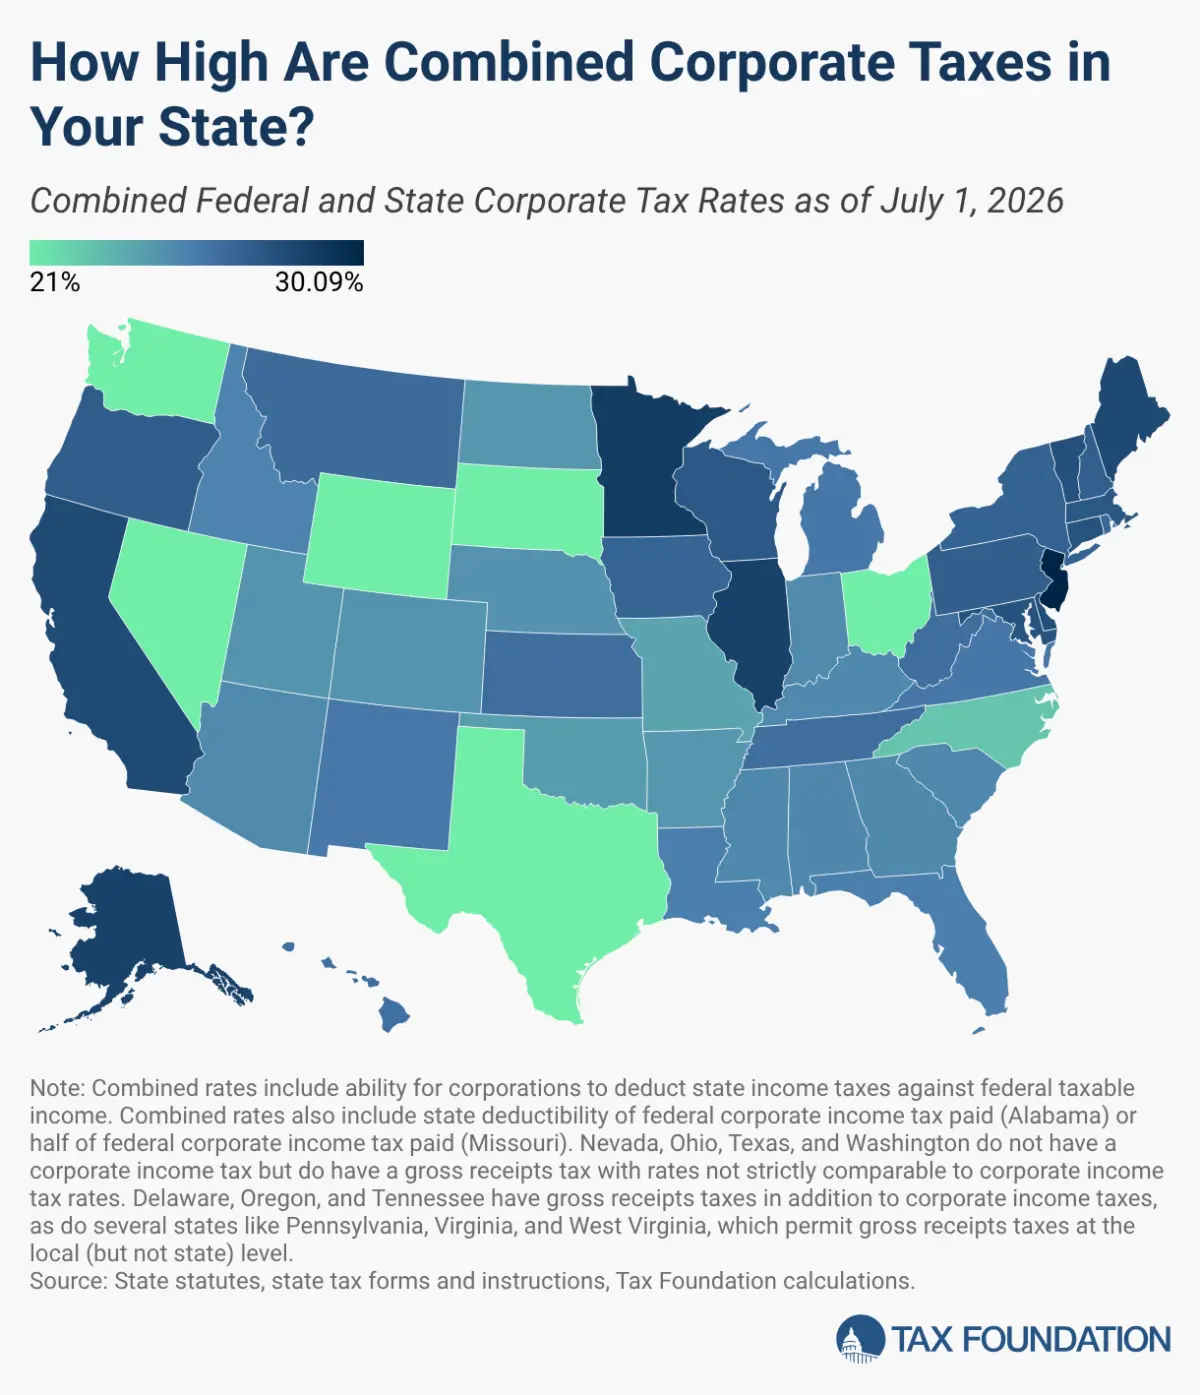
When businesses calculate their tax liabilities in the United States, looking only at federal requirements provides an incomplete picture. Corporations operating across the country are subject to a multi-layered tax environment involving federal levies, varied state-level corporate income taxes, gross receipts taxes, and complex deductibility rules that ultimately shape the true cost of doing business.
At the federal level, corporations in the United States pay a flat corporate income tax rate of 21 percent. However, this is only the baseline. Forty-four states and the District of Columbia also levy taxes on corporate income, creating a diverse patchwork of subnational fiscal policies. Top marginal rates among these states vary significantly, ranging from a modest 2.0 percent in North Carolina to a steep 11.5 percent in New Jersey.
The structural approach to state corporate income taxation varies widely as well. Thirteen states currently levy graduated corporate income tax rates, applying higher percentages to higher tiers of corporate profits. Meanwhile, 31 states and the District of Columbia opt for a flat rate on corporate income, offering a more predictable calculation for businesses operating within their borders.
The corporate income tax, or CIT, is levied by both federal and state governments on business profits. It is worth noting that many companies are not subject to the CIT directly because they are organized as pass-through businesses. For these entities, income is reportable under the individual income tax rather than the corporate tax regime. For traditional C corporations, however, the combination of federal and state obligations creates a substantial ongoing tax burden.
Beyond traditional corporate income taxes, some states utilize alternative mechanisms to extract revenue from commercial enterprises. In Nevada, Ohio, Texas, and Washington, corporations are subject to gross receipts taxes instead of corporate income taxes. Unlike standard corporate income taxes that apply to net profits after accounting for expenses, gross receipts taxes are applied directly to a company’s total gross sales. Crucially, these taxes allow no deductions for a firm’s business expenses, such as employee compensation, the cost of goods sold, and overhead costs.
Furthermore, gross receipts taxes differ fundamentally from retail sales taxes. While a retail sales tax is assessed on the final consumer transaction, a gross receipts tax is assessed on businesses and applies to transactions at every single stage of the production process. This cascading effect leads to what economists call tax pyramiding, where the same economic value is taxed multiple times as a product moves through the supply chain from raw material to finished good.
The policy landscape becomes even more intricate in states that employ multiple layers of taxation. Delaware, Oregon, and Tennessee impose a traditional tax on corporate income while also maintaining a separate, distinct levy on gross receipts. Other states push tax authority down to local municipalities; Pennsylvania, Virginia, and West Virginia levy gross receipts taxes at the local level, even though they do not impose them statewide. On the other end of the spectrum, two states—South Dakota and Wyoming—maintain a distinctly business-friendly posture by levying neither a corporate income tax nor a gross receipts tax.
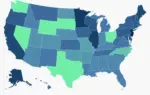
When combining federal and state obligations, the overall tax burden shifts dramatically depending on geography. The state with the highest combined corporate income tax rate in the nation is New Jersey, where businesses face a combined burden reaching 30.1 percent when factoring in federal interactions. Other states push corporations toward similarly high combined rates; in Alaska, Illinois, Maine, and Minnesota, corporations face combined corporate income tax rates at or above 28 percent.
Conversely, six states—Ohio, Nevada, South Dakota, Texas, Washington, and Wyoming—levy no state corporate income tax at all. Corporations operating exclusively within these jurisdictions face only the federal tax rate of 21 percent, though it is important to remember that four of these states offset their lack of an income tax by levying statewide gross receipts taxes instead.
Calculating the exact financial impact requires accounting for how federal and state tax systems interact with one another. Corporations are generally permitted to deduct state corporate income tax payments against their federal taxable income. This deduction lowers the effective federal corporate income tax rate, softening the blow of the combined subnational tax burden.
To illustrate how this mechanism functions in practice, consider a corporation subject to Rhode Island’s corporate income tax, which is levied at a flat 7 percent rate. Because the company can deduct the state tax it pays against the 21 percent federal corporate income tax, its effective federal rate is reduced to 19.53 percent. When combined with the state tax, the total effective burden results in a combined rate of 26.53 percent rather than a simple mechanical addition of the two nominal rates.
In a few unique instances, the flow of deductibility moves in the opposite direction or offers even greater relief. Two states allow corporations to deduct federal corporate income tax liabilities against some portion of their state corporate income tax obligations. Alabama stands out by allowing full deductibility of federal corporate income tax liability against state liability, while Missouri permits a 50 percent deduction of federal corporate income tax liability. These rare provisions further lower the effective corporate income tax rate faced by corporations operating within those state borders.
When averaging across all fifty states—including those jurisdictions that impose no corporate income taxes whatsoever—the average combined state and federal corporate tax rate imposed in the United States settles at 25.5 percent.
When analysts and policymakers examine tax burdens on businesses, looking at both federal and state corporate taxes is essential for understanding economic competitiveness. Economists widely view corporate income taxes as one of the most economically damaging ways for governments to raise revenue, largely because heavy corporate taxation can discourage capital investment, depress productivity growth, and ultimately reduce wages for workers. For state lawmakers looking to stimulate local economies, reforming or reducing corporate tax burdens represents a promising area of policy to increase economic competitiveness and promote long-term growth that benefits both companies and the workforce.