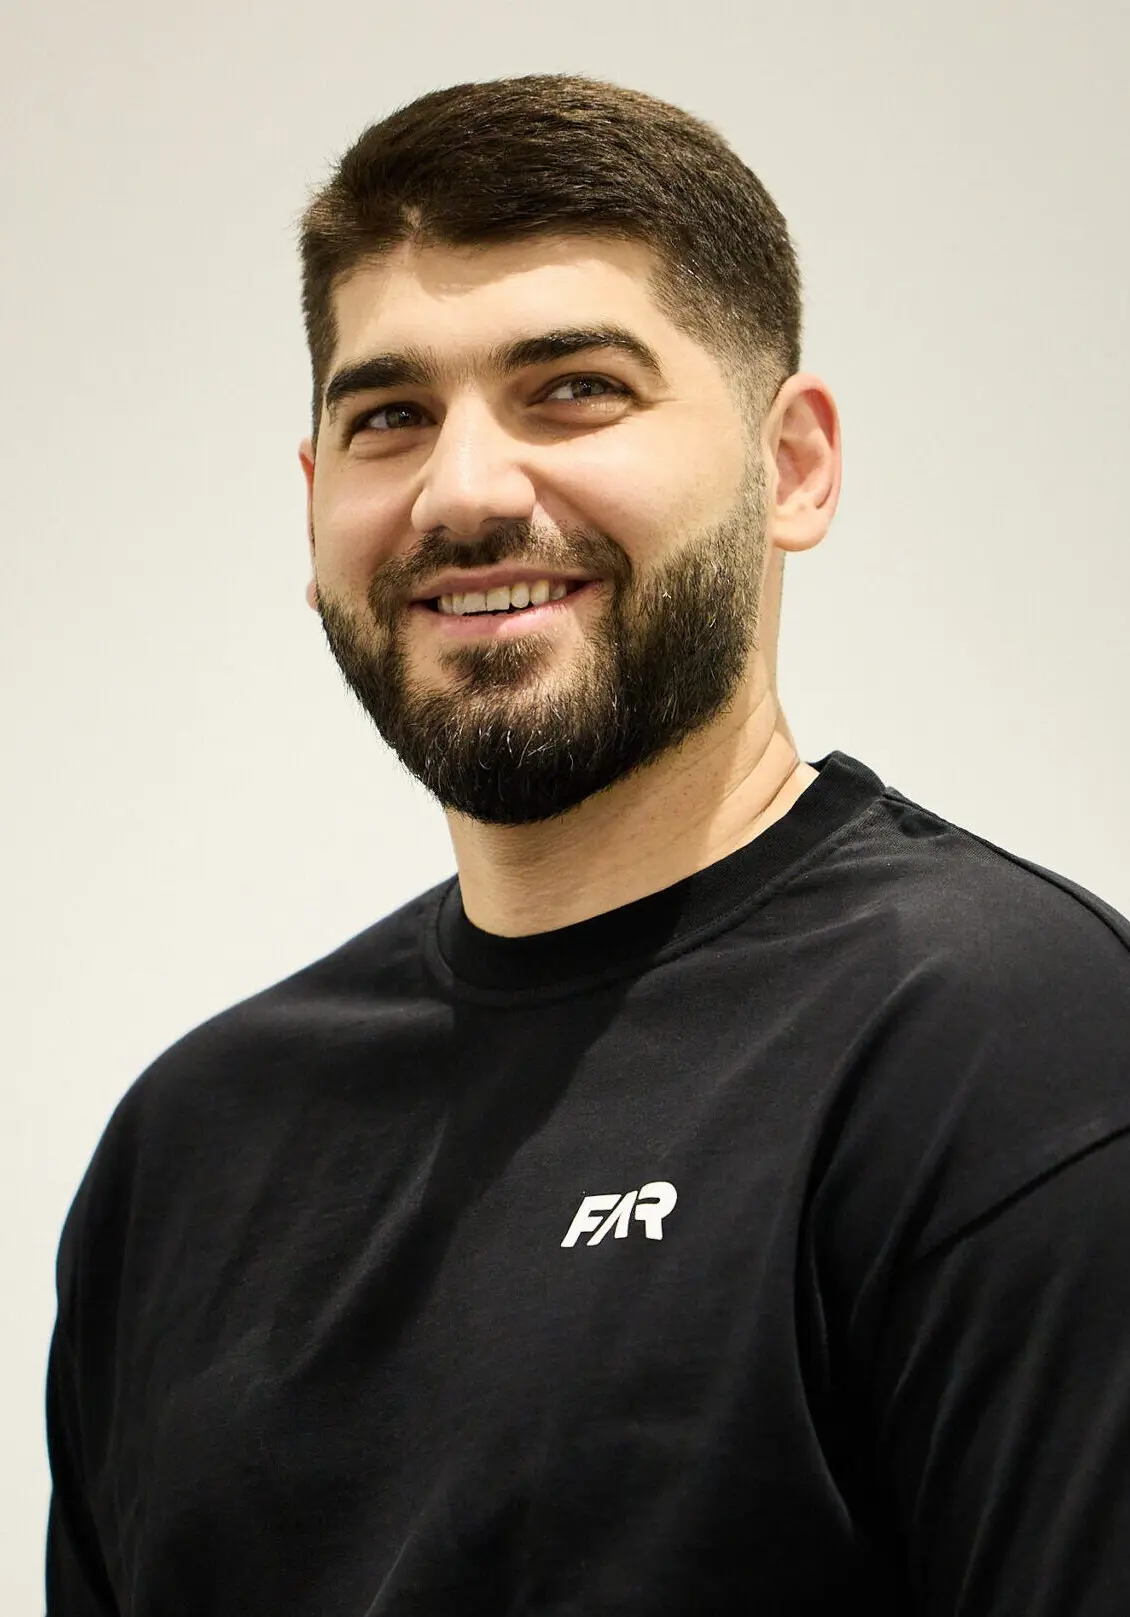
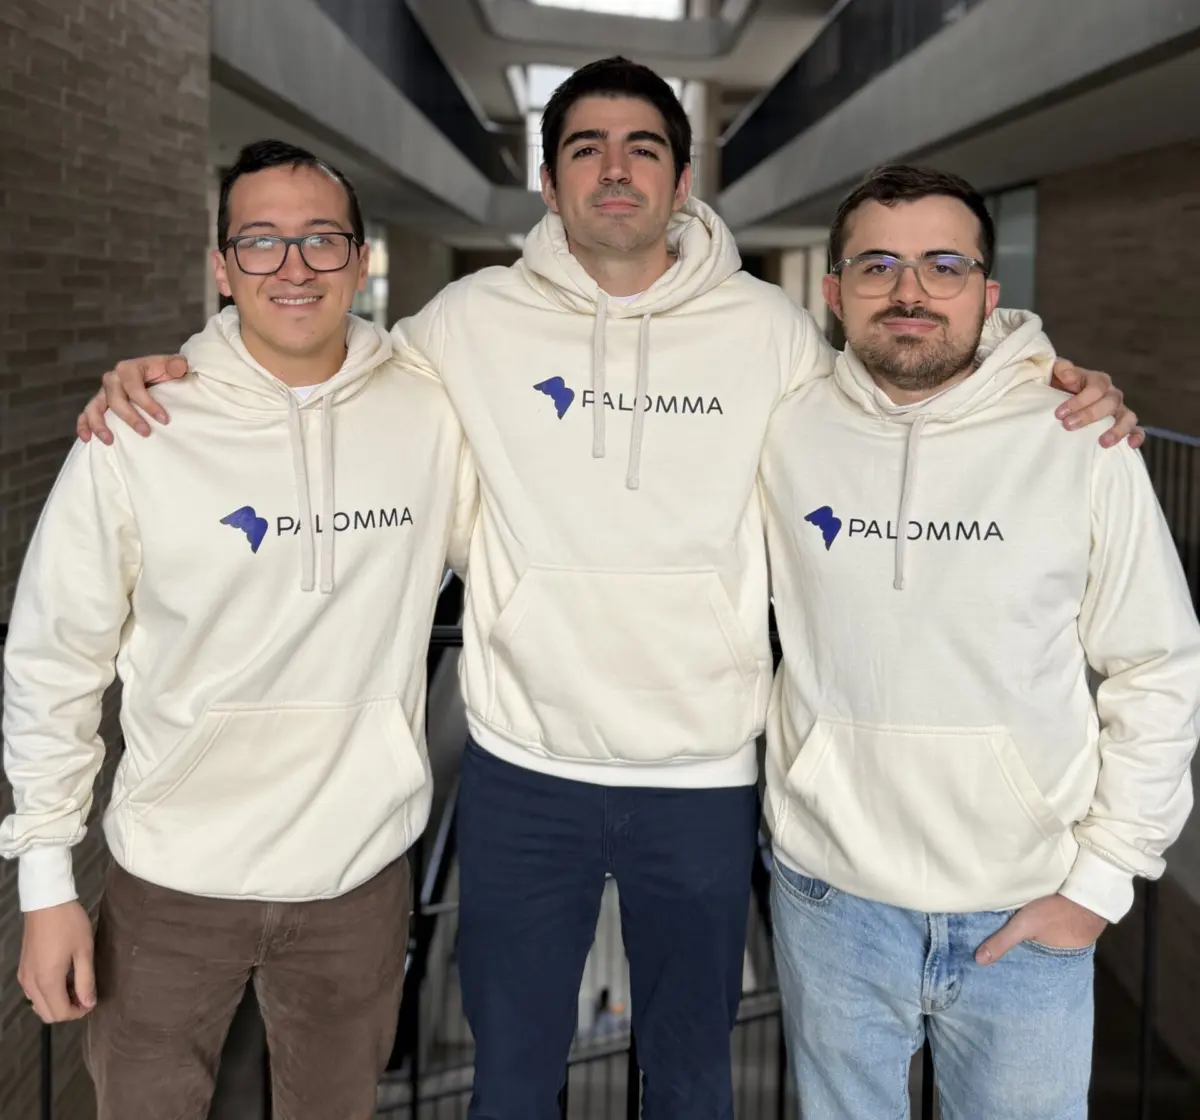
What started with a chance glance at a desk plaque in a New York office has evolved into one of Latin America’s most closely watched real estate technology startups. In 2020, Cipriano Echavarría was working at Morgan Stanley in New York, contemplating his next professional chapter, when he noticed a small plaque embedded in his desk. Among the names of the previous occupants etched into the wood was David Vélez.
Curious, Echavarría looked up the name and discovered that Vélez was not only a fellow Colombian hailing from his hometown of Medellín, but also the visionary founder of Nubank, the wildly successful Brazilian digital bank that disrupted traditional banking across the region. Seizing the moment, Echavarría took a photograph of the plaque, reached out to Vélez via LinkedIn, and politely asked for career guidance.
That single digital connection changed the trajectory of his career. Vélez revealed that Nubank was gearing up to announce its expansion into Colombia and was actively assembling a launch team. By late 2020, Echavarría had packed his bags, returned home to Colombia, and joined Nubank’s launch squad. Yet, even as he immersed himself in the fast-paced fintech world, he harbored a long-term ambition: to eventually start a company of his own.
Now, that ambition has materialized into Palomma, a Medellín-based proptech and fintech startup that has successfully raised $10 million in a Series A funding round. The round was led by Mexican venture capital firm Cometa, bringing Palomma’s total funding to $14 million, which includes $4 million in previously undisclosed capital.
The financing attracted participation from a robust roster of regional and international investors, including Volpe Capital, Clocktower Technology Ventures, Tekton Ventures, Simma Capital, and Yango Ventures. They were joined by existing backers such as Y Combinator, 17Sigma, Nido Ventures, and Norte Ventures.
Palomma’s rapid ascent is reflected in its financial and operational metrics. According to the company, its annual recurring revenue has multiplied thirtyfold over the span of 18 months, reaching approximately $3 million. The platform currently processes about $130 million in monthly rental payments, serving more than 200,000 tenants through a network of over 500 property managers across Colombia. The company estimates its annualized rent payment volume at an impressive $1.5 billion.
With fresh capital in hand, Palomma plans to deepen its footprint in Colombia, develop advanced artificial intelligence and financial products, and lay the groundwork for international expansion. While the company is evaluating potential entry into markets such as Mexico, Brazil, and the Spanish-speaking demographic in the United States, Echavarría emphasized that the home market remains the primary focus.
“We want to win Colombia,” Echavarría said in an interview.
Finding a Business in Rent Payments
Palomma’s business model occupies a unique intersection of property management software, automated payments, and tailored financial services. The company provides software that empowers property managers to streamline leasing inquiries, elevate customer service standards, and handle collections. Integrated directly into this software is a specialized payment system designed to collect rent from tenants and disburse funds reliably to landlords.
By owning these transactional relationships, Palomma unlocks the ability to cross-sell financial products—such as financing, rental guarantees, and credit-building options—directly to tenants and property owners alike.
Following nearly two years gaining invaluable experience at Nubank, Echavarría teamed up with Felipe Monsalve and Nicolás Gómez del Campo to found Palomma. Both co-founders are MIT-trained engineers whose professional backgrounds include high-level stints at Meta, Cobre, and JPMorgan Chase.
When the founding trio entered the prestigious Y Combinator accelerator program in January 2023, their initial intent was to build an account-to-account payments processor tailored for Spanish-speaking Latin America. During their first year, however, growth remained largely flat. It was only when property managers within their network began pleading for help with a specific, painful operational bottleneck—collecting rent—that the true market opportunity came into focus.
It quickly became apparent to the founders that structural friction plagued both sides of the rental transaction. Tenants were typically expected to pay their rent early in the month, yet many received their paychecks in bi-weekly installments, creating a cash-flow mismatch. Landlords, meanwhile, heavily depended on regular rental income to meet their own financial obligations, but routinely struggled to borrow against those future earnings or protect themselves when tenants defaulted. Furthermore, property managers were forced to handle collections and payouts through archaic, labor-intensive processes.
Rather than attempting the arduous task of acquiring individual tenants and landlords one by one, Palomma made a strategic pivot. The startup decided to leverage the existing infrastructure of the companies that already managed the properties.
“Let’s basically use the property managers as a distribution channel,” Echavarría recalled of the team’s strategic realignment.
From Software to Financial Services
Property managers gain access to Palomma’s proprietary AI-driven software, which automates routine leasing conversations and initial inquiries. Once integrated, the software offers to process the property’s rent payments. This direct payment flow grants Palomma continuous visibility into rental income streams and tenant payment histories, establishing a rich proprietary data asset that can be seamlessly leveraged to evaluate applicants for financial products.
From there, Palomma deploys a suite of targeted financial services tailored for both sides of the lease. Palomma Plus offers tenants loyalty rewards and credit-building benefits that formalize their payment habits. Palomma Advance allows landlords to collect up to 12 months of future rental income upfront, providing immediate liquidity. Palomma Protect steps in to cover rental income in the event of a tenant default. Additionally, the company is actively developing Palomma Flex, a product designed to let tenants split their monthly rent into more manageable bi-weekly installments.
The revenue model is structured to capture value across multiple touchpoints. Property managers pay a recurring subscription fee for the AI-powered software, while Palomma earns a transaction percentage on rent payments and financial services.
This multi-product approach has driven exceptional customer retention. Palomma reports a net revenue retention rate of 390% after 12 months, meaning that revenue generated from an existing cohort of customers has nearly quadrupled within a single year, even after factoring in customer churn or reduced spending.
This strategy of combining AI leasing software, automated payments, and comprehensive financial services aligns closely with Echavarría’s overarching thesis on how to build a scalable, enduring business in Latin America. Pointing to U.S. counterparts such as EliseAI, Bilt, TheGuarantors, and Flex as conceptual comparisons for different facets of Palomma’s operations, Echavarría argues that achieving massive scale in Latin America requires a much broader product suite.
“In the U.S., you can build one solution and be really large because the market allows it,” he explained. “In Latin America, if you want to be really large, you need to do all the things.”
Managing the Risk
Artificial intelligence plays a critical role not just in software efficiency, but also in risk management and underwriting. When prospective tenants inquire about a property, Palomma’s AI leasing agent communicates seamlessly through WhatsApp, guiding applicants through the conversation and collecting necessary documentation. The company states that its automated system can deliver a formal rental guarantee approval in under 30 seconds by analyzing conversation data alongside historical rental payment behaviors.
These rental guarantees place Palomma on the hook financially if a tenant fails to pay. While the startup initially absorbs that risk on its own balance sheet, Echavarría noted that the company is actively finalizing a partnership with an established insurance firm to share the risk, a move that will allow Palomma to safely issue a higher volume of guarantees.
AI has also allowed the startup to operate with a remarkably lean team. As of early November, Palomma employed just 18 people, up slightly from the 14 employees it had when it closed its Series A round roughly three weeks prior. To put that efficiency in perspective, a single customer service employee works alongside automated AI agents to support the roughly 200,000 tenants paying rent through Palomma’s platform.
The company operates on the foundational belief that artificial intelligence can drastically lower the cost of providing real estate financial services, mirroring how mobile technology once enabled digital banks to effectively compete with legacy lenders burdened by expensive branch networks. Looking further ahead, Palomma plans to expand its real estate footprint beyond residential rentals into homeowners association payments and full residential property transactions.
Pepe Bolaños, managing partner at lead investor Cometa, noted that Palomma immediately stood out due to the exceptional caliber of its founding team and the vast opportunity to modernize Latin America’s highly fragmented rental market. In Colombia alone, nearly 8 million households rent their homes, creating a massive addressable market.
“We look for companies tackling markets where outdated processes create an opportunity to build a proprietary data asset that can be leveraged and monetized through AI,” Bolaños wrote in an email.
Highlighting Echavarría’s operational experience scaling Nubank alongside Monsalve and Gómez del Campo’s elite technical and financial backgrounds, Bolaños pointed to the startup’s rapid scaling as a testament to exceptional execution. In roughly a year and a half, Palomma grew to process approximately $130 million in monthly rental volume and serve over 200,000 tenants with a team of only 14 people.
“That kind of execution is unusual. It convinced us that this team has what it takes to build a much larger business,” Bolaños added.
Unlike single-feature competitors that focus exclusively on isolated services, Palomma’s ability to weave rent collection, tenant screening, and financial guarantees into a unified ecosystem gives it a distinct advantage. Directly processing payments provides continuous behavioral insights that sharpen underwriting, preemptively flag potential defaults, and support the introduction of new financial products, all while AI handles the heavy lifting of daily operations.
“We believe the combination of distribution, proprietary payment data and AI gives Palomma a competitive advantage that can become stronger as the company grows,” Bolaños concluded.