As Father’s Day is observed, many people find themselves reflecting on the profound impact of the paternal figures and guiding forces in their lives. While wisdom comes from many sources throughout a person’s journey, the lessons passed down by parents often leave the most indelible marks. Growing up with parents who lived through the trials of the Second World War instills a unique perspective on resourcefulness, discipline, and the true value of money. For those who grew up in households where rationing books remained a tangible memory long after moving away from the United Kingdom, financial caution was not merely a preference; it was a way of life.
Yet, within that framework of profound thriftiness, occasional moments of unexpected philosophy emerge, revealing deeper truths about balancing frugality with the realities of living a full life. Looking back at the expressions, habits, and guidance offered by a father from a bygone era provides a fascinating lens through which to examine both personal finance and human behavior.
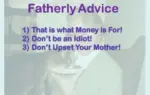
“That is What Money is For”
Growing up in a household managed by parents who experienced wartime scarcity meant that every penny was respected. They were by no means spendthrifts, and their careful approach to household finances defined much of their daily routine. Money was saved, tracked, and treated with utmost seriousness.
However, amidst this cautious backdrop, a specific phrase would occasionally surface to justify a rare departure from the norm. Whenever work ran exceptionally late, leaving public transit options exhausted, the decision would be made to take a cab home. To explain this deviation from the strict household budget, the rationale was simple and direct: “That is what money is for.”
This philosophy serves as a vital counterbalance to chronic financial anxiety. While it is entirely possible to pontificate endlessly about the dangers of overspending, the occasional splurge under specific circumstances is not only acceptable but necessary. Money functions as a tool meant to buy comfort, security, and peace of mind when life demands it. Recognizing when to loosen the purse strings is just as important as knowing when to tighten them.
“Don’t Be an Idiot!”
Transitioning from the protective environment of childhood into the independence of university life brings a wave of new experiences and temptations. When leaving for higher education, the advice offered by seasoned parents often centers on academics, career preparation, and diligence. Surprisingly, the advice received in September 1980 took a distinctly practical, albeit unconventional, turn.
The counsel was explicit: if out drinking, always consume two glasses of water before going to sleep. While this guidance is exceptionally sound for avoiding physical discomfort the following morning, it initially seemed disconnected from the academic rigors expected of a university student. When pressed with the question of how this related to studies and responsibilities, a much deeper, hidden message emerged.
The underlying sentiment was unmistakable and encapsulated by a classic phrase: “Don’t be an idiot.” Beneath the humorous surface of hangover prevention lay a reminder about personal accountability, proper behavior, and maintaining an awareness of one’s primary purpose. This principle extends far beyond campus life and applies directly to personal finance. Financial stability requires more than just understanding numbers; it demands the self-awareness to avoid reckless decisions and the discipline to act responsibly.
“Don’t Upset Your Mother”
Navigating relationships requires diplomacy, patience, and a deep respect for shared spaces and responsibilities. Among the various pieces of advice handed down during the mid-1970s, one directive stood out for its straightforward clarity: “Don’t upset your mother.”
While failing to follow this advice frequently enough yielded plenty of memorable lessons through trial and error, the underlying wisdom remains entirely sound. When translated into the context of modern financial partnerships, the principle takes on a practical economic dimension. In a shared household or partnership, financial decisions should ideally be collaborative. Working alongside a partner means striving to ensure that neither party is blindsided or distressed by major monetary choices. Mutual agreement and open communication form the bedrock of both a harmonious home and a stable financial future.
Father’s Day in Comparison
Looking at the broader cultural traditions surrounding family appreciation days, historical data highlights interesting patterns in how society connects with parents. When observing communication trends during the era when long-distance phone calls carried significant financial weight, Mother’s Day consistently held the record for the highest volume of long-distance calls made.
Father’s Day, on the other hand, held a rather distinct and humorous operational record of its own, notoriously generating the highest volume of collect phone calls. This lighthearted statistical quirk reflects the unique, sometimes pragmatic relationship many people shared with their fathers—where reaching out often required a little logistical finagling, perfectly capturing the enduring spirit of fatherhood across generations.