The US dollar is retreating for the fourth day running, declining against a shifting macroeconomic backdrop despite Brent crude oil’s persistent attempts to hold onto the key psychological level of $110 per barrel. The last time Brent crude was seen trading consistently at these elevated levels was in May, a period marked by significant disruptions to petroleum supplies through the vital Strait of Hormuz. Those disruptions had prompted the rushed conclusion of a fragile and ultimately short-lived peace agreement brokered between Washington and Tehran.
This time around, the landscape of supply and demand appears structurally different, yet geopolitical fragility continues to dictate market movements. According to recent estimates published by the US Department of Energy, current export volumes originating from the Middle East stand at approximately 80% of pre-war levels. This recovery in output would typically exert downward pressure on global energy markets. Nevertheless, a substantial and stubborn geopolitical risk premium remains baked into the market, actively preventing oil prices from experiencing a more pronounced fall.
Industry data compiled by Kpler indicates that 18 commercial ships have been directly attacked or harassed in the strategic waters of the Strait of Hormuz over the past two weeks alone. When coupled with the Houthis’ ongoing and persistent drone and missile attacks targeting infrastructure in Saudi Arabia, these maritime incidents are keeping geopolitical tensions exceptionally high across the Middle East. With its back against the wall amid international sanctions and diplomatic isolation, Iran finds itself with very few diplomatic levers, driving it to assert aggressive control over the world’s most critical oil transit artery.
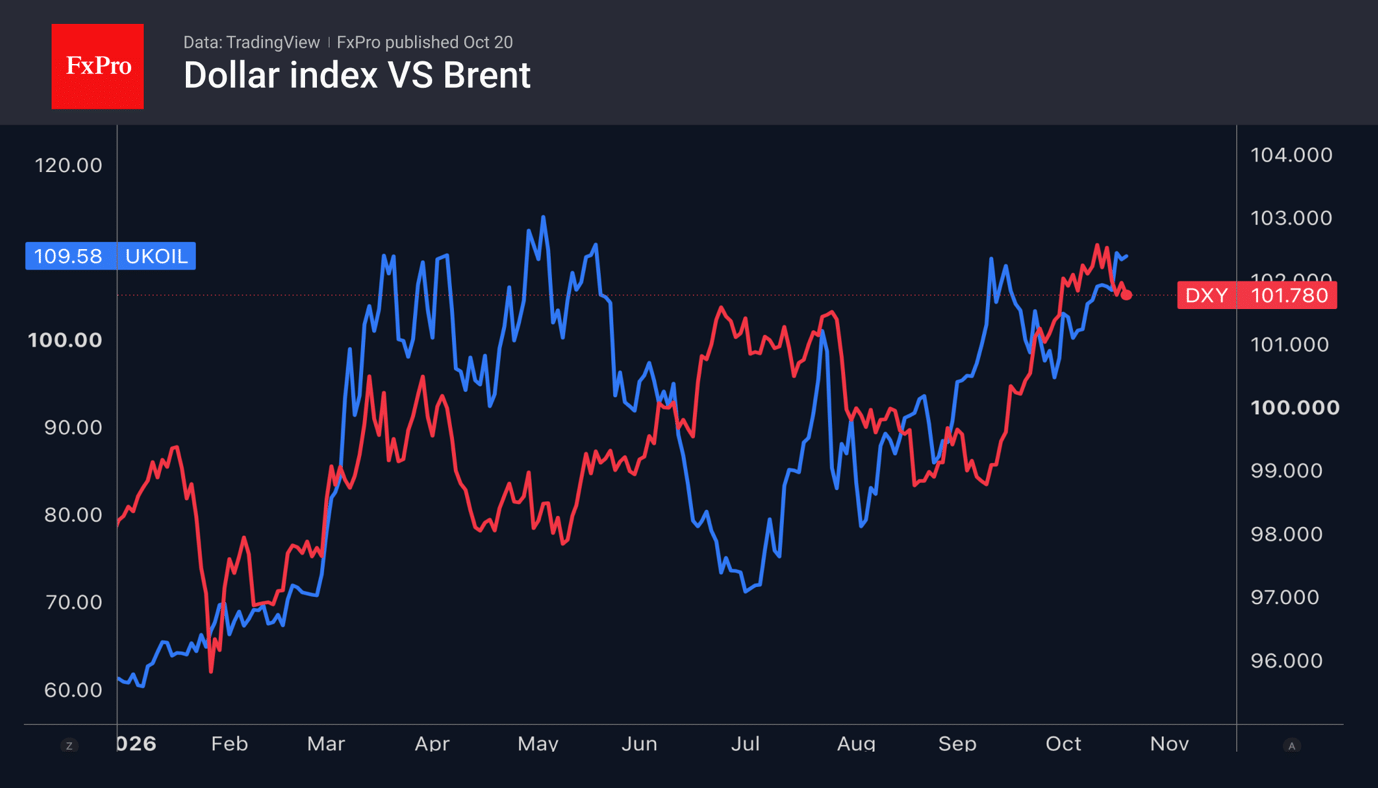
At the same time, the downward pressure on Brent prices is being effectively held back by two powerful counter-forces: a notable increase in maritime tanker traffic bound for China, and a significant, structural reduction in global oil inventories. At the very start of the renewed conflict in the Middle East, these global strategic and commercial stocks served as a vital buffer, helping to absorb the initial shocks and holding back an even more violent rally in North Sea crude. However, that safety net has worn thin. The International Energy Agency (IEA) has now formally announced the release of the final 100 million barrels from strategic petroleum reserves, forming the concluding tranche of a massive 400-million-barrel batch that was originally agreed upon back in March. Meanwhile, Beijing’s rapidly growing domestic appetite for energy imports is providing energy bulls with immense confidence that underlying demand remains remarkably robust.
The persistent divergence between the trajectory of Brent crude and the movement of the US dollar is fundamentally driven by a profound shift in prevailing market narratives and investor psychology. In the recent past, the American greenback typically strengthened hand-in-hand against the backdrop of an oil rally, benefiting simultaneously from its dual status as the currency of a major energy-exporting nation and a premier safe-haven asset during times of international crisis. Currently, however, the US Dollar Index is exhibiting a markedly different behavioral pattern, showing significantly greater sensitivity to domestic developments within the United States equity market than to external commodity shocks.
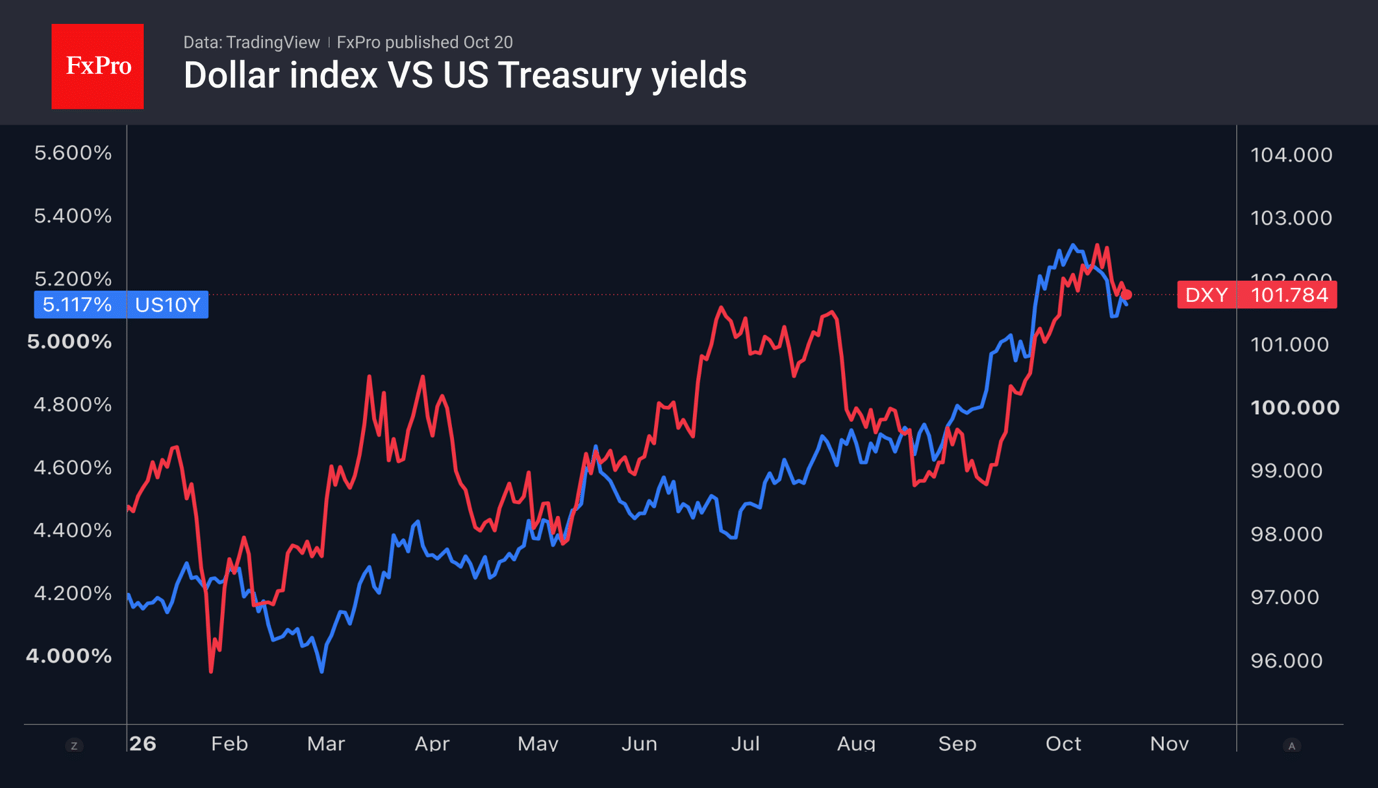
This shifting sensitivity was laid bare when the Nasdaq-100 recorded its worst weekly performance since April 2025. That sharp equity market sell-off triggered an immediate and aggressive plunge in US Treasury bond yields as institutional investors rushed toward traditional safe-haven assets in search of capital preservation. Consequently, the US dollar momentarily lost its main trump card, especially as domestic economic data and shifting market expectations diminished the likelihood that the Federal Reserve would pursue aggressive monetary policy tightening during its upcoming October meeting.
However, once technology shares managed to engineer a technical recovery later in the period, the downward momentum of the USD index noticeably slowed. As a result, participants in the broader foreign exchange market are currently paying far closer attention to incoming corporate earnings reports and equity market fluctuations than they are to breaking news dispatches coming out of the Middle East.