When currency traders speak of financial cracks developing on both sides of the Atlantic, they are referring to a simultaneous structural decay affecting both the U.S. dollar and the Euro. This fragile macroeconomic environment introduces a severe risk of global currency devaluation, driven primarily by an inescapable, competitive race to the bottom. As major Western economies grapple with compounding fiscal pressures, the traditional dynamics of the global financial system are undergoing a profound and historic shift.
The Cracks in Transatlantic Finance
The underlying structural fragility seen across the Atlantic is propelled by a combination of heavy fiscal deficits and unprecedented corporate and governmental leveraging. Both the United States and major Eurozone nations, including France, are running massive fiscal deficits that demand continuous monetary accommodation. At the same time, the staggering capital requirements needed to build global artificial intelligence infrastructure have forced major tech hyper-scalers to issue unprecedented amounts of corporate debt, heavily burdening the credit markets.
While artificial intelligence remains a powerful driver of stock market gains, particularly in the United States where the dominant mega-cap tech stocks capture the spotlight, the financial scale of global military re-armament is proving equally monumental. The planned increases in Group of Seven defense spending over the next decade are projected to rival the massive capital allocations directed toward Big Tech and AI. Additional defense commitments from G7 governments over the next ten years amount to roughly $8 trillion in additional re-armament spending, arriving on top of prior budgetary trends.
A Race to Worthless
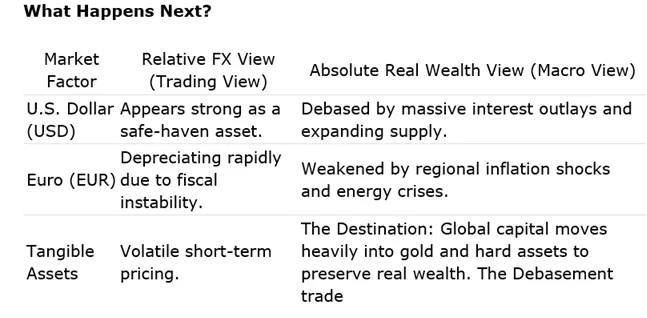
To fully comprehend the anxieties currently gripping currency trading desks, market participants emphasize the critical distinction between relative currency valuation and absolute purchasing power devaluation. Under normal market conditions, if Europe faces an acute economic or political crisis, the Euro plummets while the U.S. dollar surges. Recently, the Euro has fallen toward a 17-month low of $1.12. On paper, the U.S. dollar appears exceptionally strong, fulfilling its traditional role as what Wall Street analysts describe as the cleanest dirty shirt in the laundry.

However, the deeper danger perceived by macro traders is that both currencies are experiencing rapid real-world devaluation. This decline has already materialized prominently within the Euro, and corresponding weakness is widely anticipated for the U.S. dollar. Because the Federal Reserve and the European Central Bank are forced to continuously manage their massive sovereign liabilities through monetary expansion or by maintaining high interest rates to service mounting debts, both currencies are fundamentally losing their purchasing power against tangible, real-world assets.
Neither major power can afford a genuinely strong, restrictive currency without risking a sovereign debt default. Consequently, the global financial system faces a structural race to the bottom, where capital systematically begins moving out of paper promises altogether and flows directly into hard assets.
The Debasement Trade and Shifting Reserves
Gold and raw commodities are pricing in these systemic Atlantic cracks through a structural decoupling from fiat currencies, transforming from simple inflation hedges into defensive tools against sovereign risk. Although the safe-haven U.S. dollar can temporarily suppress paper commodity prices during periods of acute market panic, the underlying structural flow demonstrates investors steadily abandoning crumbling Western debt liabilities in favor of physical commodities.
For nearly thirty years, U.S. Treasuries held an unchallenged crown as the premier global reserve asset. However, data compiled by the European Central Bank and the World Gold Council reveals a dramatic structural crossover. By the end of 2025, gold’s share of global central bank reserve assets surged to 27%, while the share held in U.S. Treasuries contracted to 22%.

This shift marks the acceleration of the broader debasement trade. As Western sovereign debt levels cross critical psychological thresholds—with U.S. federal debt surpassing $40 trillion and total global debt reaching a record $365.5 trillion—investors are increasingly treating G10 government bonds not as safe havens, but as systemic financial liabilities.
The traditional financial relationship where soaring bond yields crush non-yielding hard assets has fractured. Modern market charts display this historic correlation breaking down completely. Despite Western bond yields climbing drastically due to ballooning sovereign deficits, gold has simultaneously surged to record highs. This visual divergence confirms that investors are treating gold as a systemic risk hedge rather than merely a tactical play on interest rates.
Global gold ETF holdings have reached record highs as Western retail and institutional investors catch up to non-Western central banks, which have proactively chosen bullion over U.S. Treasuries to diversify away from geopolitical and structural currency risks. Capital concentration reports indicate that money is flowing directly into tangible economic bottlenecks, including physical energy grids, artificial intelligence data center hardware, and essential base metals like copper, which face profound structural supply constraints.
The S&P GSCI Commodity Index has surged roughly 32% to 33% over the course of the year, reflecting a broad global pushback against transatlantic debt expansion and real-world currency debasement.

Macro Commodities and Structural Constraints
Beyond precious metals, raw commodities are pricing in a combination of structural supply-side constraints and massive infrastructure demands. Crude oil has faced extensive upward pressure, climbing toward the $90 to $95 range, driven by ongoing geopolitical tensions and the real-world cost of currency debasement embedded within global oil contracts.
Transatlantic debt is heavily funding digital transformations, and the monumental power and manufacturing needs of global artificial intelligence hardware have created inelastic demand for industrial metals like copper, shielding them from broader economic slowdowns. As the Atlantic alliance strains and the global economy fragments into distinct regional trade blocs, the physical cost of moving raw materials increases, prompting traders to price this structural inefficiency into food, energy, and soft commodities.
Ultimately, commodities are pricing in a world where paper contracts—whether denominated in Euros, Dollars, or government bonds—are viewed as increasingly unreliable stores of value compared to physical resources.
According to data compiled by the World Gold Council, global official institutions registered a staggering 289 tonnes of net gold purchases in the second quarter, marking the single largest second quarter on record. This follows a revised net total of 57 tonnes in the first quarter, during which large-scale liquidity sales from Turkey and Russia temporarily masked robust underlying institutional demand.

Sovereign Crisis Insurance
Rather than tracking standard consumer price inflation data, gold has effectively re-priced as a direct bet against the stability of Western central bank governance. Gold reached an all-time nominal high of $5,608.35 per ounce early in the year, and while it has consolidated near $4,138 ahead of upcoming central bank guidance, it remains structurally elevated compared to historical norms.
Emerging market central banks, such as the People’s Bank of China, are aggressively substituting U.S. Treasuries and Euros for gold. This creates a permanent floor under the market, driven by a structural imperative to avoid sanctionable and depreciating Western paper liabilities. During moments when European political stress flares up, the U.S. dollar briefly spikes on relative safe-haven demand, creating localized downward corrections in paper futures that highlight the ongoing divergence between short-term spot volatility and long-term accumulation trends.
Sovereign accumulation patterns highlight a profound shift in the psychology of global reserve managers. As Deutsche Bundesbank Chief Joachim Nagel noted at the London Bullion Market Association conference, gold’s share of world central bank reserves has jumped from 14% to nearly 25% in a remarkably short span. Central banks are treating gold as an irreplaceable shield against transatlantic vulnerabilities, supported by findings from the World Gold Council’s annual survey, which revealed that 89% of reserve managers expect global gold holdings to continue expanding over the coming year, with 45% actively planning to increase their own bullion reserves. Concurrently, 74% of central banks explicitly forecast that the U.S. dollar’s dominant share of global reserves will contract over the next five years.
This wave of accumulation is anchored by a tight group of sovereign participants pursuing multi-year asset-diversification mandates, while other central banks consistently alternate between mining domestic supply and stacking reserves, logging steady monthly net additions as hard assets transform from tactical hedges into core structural anchors for the international financial system.