Managing rental properties across multiple LLCs, tracking income and expenses by individual property, and keeping security deposits rigorously organized requires financial infrastructure that far exceeds the capabilities of a standard business checking account. Modern real estate investors and portfolio operators need banking tools engineered specifically to handle the intricate cash flow dynamics of multi-property portfolios. The right banking solution can fundamentally transform how an investor organizes incoming revenue and operating expenses across different entities, while seamlessly connecting daily banking activity with long-term bookkeeping and tax reporting workflows.
Whether an investor manages a single rental property or an extensive portfolio spanning dozens of units, choosing a financial platform that genuinely understands real estate investing can streamline operations and provide critical support for portfolio growth. Standard small business banking accounts often fall short when applied to the multi-entity and property-specific demands of real estate.
The evolution of financial technology has introduced specialized digital platforms alongside traditional commercial lenders, giving real estate operators a broad spectrum of choices. Understanding these options requires examining how different institutions serve the market, ranging from integrated proptech banking solutions to major national banking networks and specialized commercial real estate lenders.
Why Real Estate Investors Need Specialized Banking
Banking for rental properties differs fundamentally from standard retail or small business banking. A real estate investor or operator managing multiple properties across distinct limited liability companies faces an entirely different set of operational challenges than a traditional business owner operating out of a single checking account. Utilizing separate bank logins and disjointed mobile applications often scatters critical financial data across disconnected systems, making monthly reconciliation and annual tax preparation exceptionally time-consuming.
A robust banking solution designed for real estate investors and operators should support granular cash flow separation, automated transaction categorization aligned with tax schedules, and integrated rent collection mechanisms. Furthermore, these platforms must be able to handle specialized funds like tenant security deposits securely and transparently.
The financial marketplace now features a diverse array of platforms, including digital-first ecosystems built specifically for real estate, traditional commercial banks with extensive branch networks and lending capabilities, and online institutions offering specialized commercial and credit products.
Baselane and Integrated Real Estate Bookkeeping
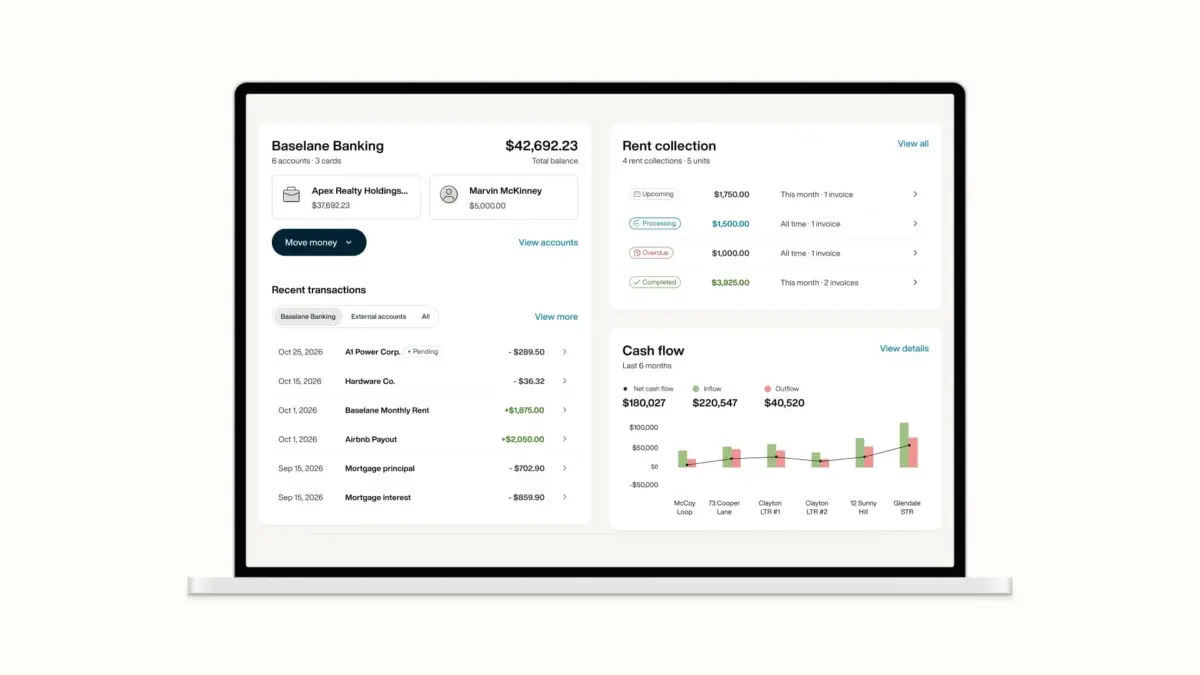
Platforms like Baselane have emerged to address the specific intersection of banking and bookkeeping for multi-property real estate investors and operators. By combining property-level banking accounts, automated bookkeeping, and built-in rent collection into a single integrated system, these platforms target the core operational friction points that traditional banking leaves unaddressed.
Real estate operators frequently struggle with cash flow spread across disparate accounts, multiple logins for separate LLCs, and the arduous manual labor required to categorize transactions at tax time. Digital platforms designed for this sector allow investors to open unlimited checking and savings accounts organized cleanly by property, entity, or specific operational purpose, all accessed through a centralized dashboard.
By automatically assigning incoming and outgoing transactions to each property, entity, and tax category using extensive real estate-specific taxonomies, these platforms significantly reduce the manual work traditionally required at year-end. This automation supports clean tax preparation workflows, particularly for IRS Schedule E reporting. While these digital-first platforms lack physical branch networks, many offer cash deposit capabilities through partner ATM networks, though investors requiring intensive teller-based services or direct commercial real estate loans often choose to pair them with traditional financial institutions.
Portfolio Tracking and Cash Management Alternatives
Other market participants approach the challenge from slightly different angles. Stessa, a property management platform based in Oakland, California, incorporates cash management features directly into its broader suite of portfolio tracking tools. Its built-in accounts allow investors to separate funds by property or portfolio while tying banking activity directly into property management, leasing, and maintenance tracking workflows. While highly effective for portfolio oversight, investors whose primary objective is deep banking and bookkeeping automation may find the software oriented toward a broader operational scope.
Meanwhile, general online business banking platforms like Bluevine offer high-yield interest checking and access to business lines of credit. These solutions work well for investors looking to separate funds using subaccounts within a single banking relationship while maintaining ready access to working capital for emergency repairs or portfolio expansion. However, because they are designed for general small business use rather than real estate specifically, investors still require separate tools for property-level bookkeeping automation and specialized tax reporting.
Traditional Banking and Commercial Lending Networks
Traditional national banking institutions continue to play a vital role for real estate investors who prioritize physical branch access, extensive cash handling, and direct commercial real estate lending relationships. Institutions such as Chase and Wells Fargo provide massive branch networks and commercial lending divisions capable of handling complex multifamily portfolios and agency financing programs through Fannie Mae, Freddie Mac, or FHA frameworks.
Similarly, U.S. Bank offers direct investment property loans spanning multifamily, office, warehouse, retail, and mixed-use assets, often paired with simplified business checking options. Live Oak Bank operates as a national specialist in SBA-backed financing, assisting investors with acquisitions and major renovations through streamlined digital processes. Other digital-first institutions like Axos Bank provide online DSCR and rental property loan programs without requiring physical branch visits, catering to investors pursuing specific debt service coverage ratio financing strategies.
Technology-Forward Platforms and Multi-Account Management
Tech-forward business banking platforms like Mercury offer API access for custom financial automation workflows, appealing primarily to investors managing complex holding company structures. However, because these platforms are built for broader technology businesses rather than rental property operators, they typically require supplementary software for property-level accounting and rent collection.
Other online business banking options, such as Relay, focus heavily on multi-account cash flow management and team collaboration. These platforms allow investors to set up numerous checking accounts and utilize percentage-based automated transfer rules for cash flow allocation strategies like Profit First. While powerful for cash separation across multi-LLC portfolios, platforms of this nature generally concentrate on account architecture rather than real estate-specific automation, meaning investors may still need supplementary tools for automated property bookkeeping and integrated rent collection.
Choosing the Right Financial Partner
Ultimately, the choice between a specialized digital proptech banking platform and a traditional banking institution depends heavily on the unique operational scale and strategy of the investor. Digital-first platforms provide property-level organization, automated bookkeeping, and streamlined rent collection that traditional banks rarely offer out of the box. Conversely, traditional institutions deliver vital in-person branch services, cash deposit infrastructure, and large-scale commercial real estate financing. Many active real estate investors choose a hybrid approach, leveraging specialized digital platforms for daily operational banking and bookkeeping automation while maintaining traditional banking relationships for long-term debt and commercial lending.