
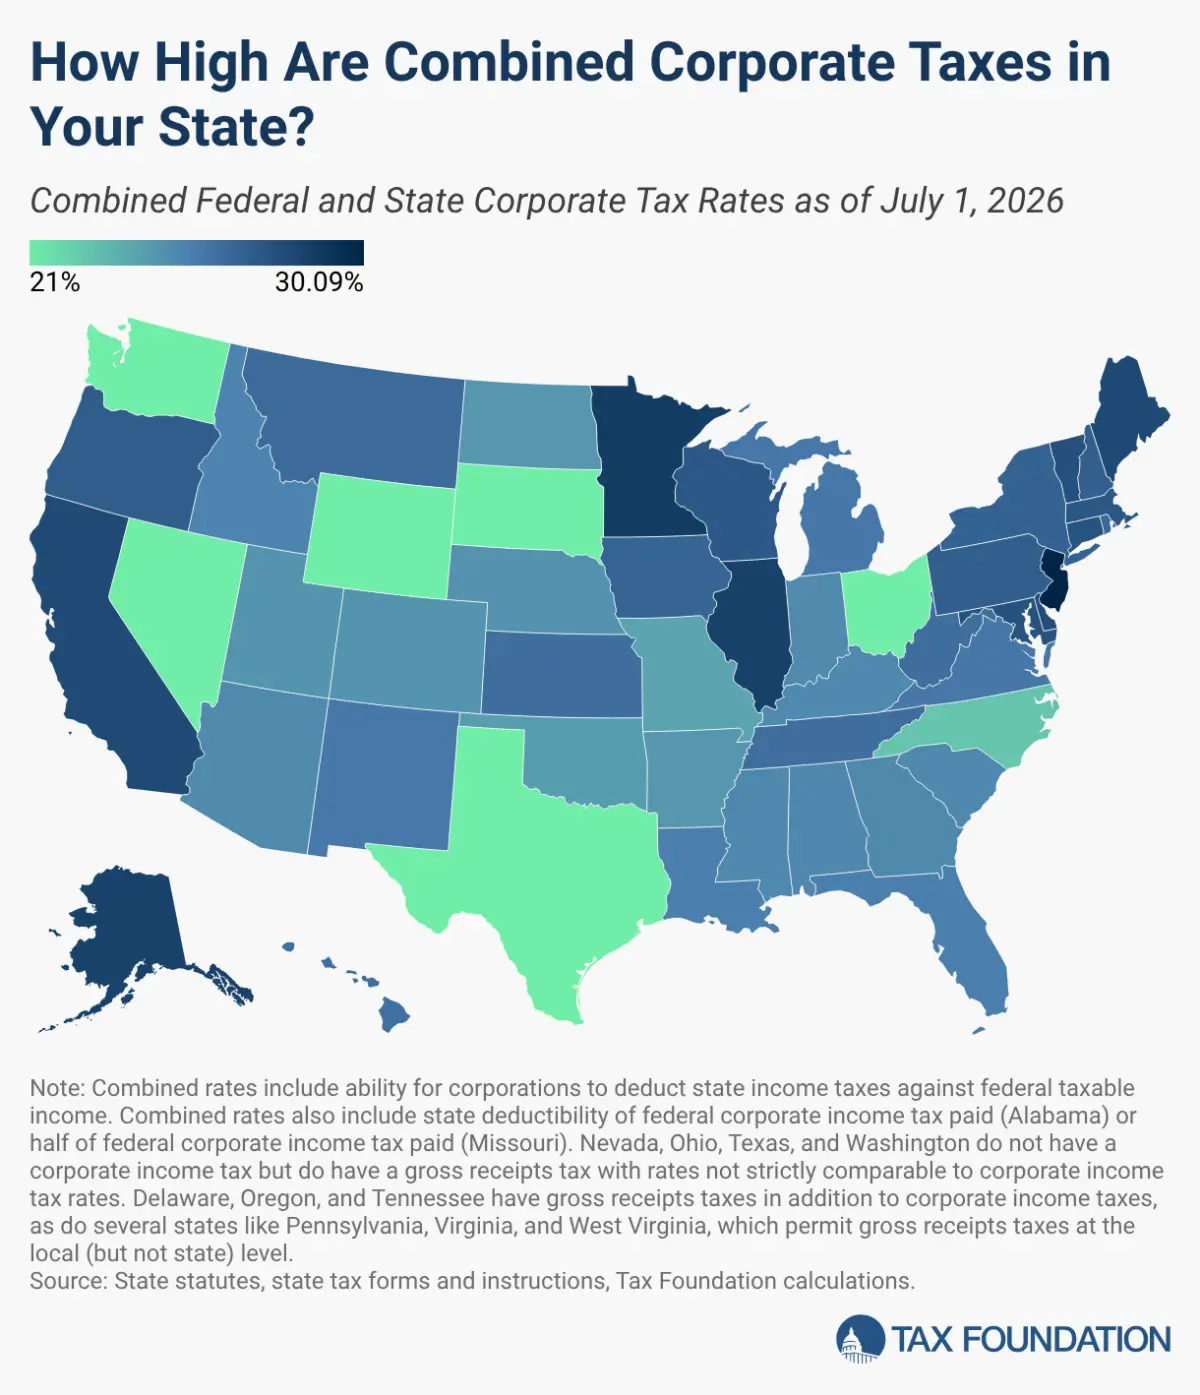
When analyzing the true tax burden borne by corporations operating within the United States, looking at a single statutory rate tells only part of the story. Corporations navigate a multi-layered tax environment consisting of federal obligations, state-level corporate income taxes, gross receipts levies, and a complex system of deductions that ultimately dictates their effective tax rates. With a federal corporate income tax rate anchored at 21 percent, businesses must also contend with the diverse tax policies enacted by individual states, creating a patchwork of economic incentives and burdens across the country.
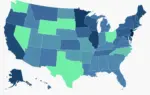
At the federal level, corporations in the United States pay a flat corporate income tax rate of 21 percent, a benchmark established under recent federal tax reforms. However, corporate taxation does not stop at the national border. Forty-four states, alongside the District of Columbia, levy their own taxes on corporate income. These state-level top marginal rates vary significantly, ranging from a modest 2.0 percent in North Carolina to a steep 11.5 percent in New Jersey.
The structural approach to state corporate income taxes also differs widely across jurisdictions. Thirteen states employ graduated corporate income tax rates, meaning the tax percentage increases as a company’s taxable profits rise. Meanwhile, the vast majority—31 states plus the District of Columbia—levy a flat rate on corporate income, providing a uniform percentage regardless of the total profit generated by the firm.
Adding to this complexity, not all states rely primarily on corporate income taxes to generate revenue. In Nevada, Ohio, Texas, and Washington, corporations are subject to gross receipts taxes instead of traditional corporate income taxes. Gross receipts taxes are applied directly to a company’s total gross sales, without allowing deductions for standard business expenses such as employee compensation, the cost of goods sold, or overhead costs. Unlike a standard retail sales tax, a gross receipts tax is assessed directly on businesses and applies to transactions at every stage of the production process. This cascading structure often leads to tax pyramiding, where the tax is compounded at multiple phases of production before the final product ever reaches the consumer.
Furthermore, some states take a hybrid approach. Delaware, Oregon, and Tennessee impose both a traditional tax on corporate income and a separate levy on gross receipts. At the local level, cities and municipalities in Pennsylvania, Virginia, and West Virginia also levy gross receipts taxes, even though their respective state governments do not utilize them in the same manner. On the opposite end of the spectrum, two states—South Dakota and Wyoming—stand out by levying neither a corporate income tax nor a gross receipts tax at the state level, offering a streamlined tax environment for businesses operating within their borders.
When combining federal and state obligations, the total tax burden shifts dramatically depending on geography. The state with the highest combined corporate income tax rate in the nation is New Jersey, reaching a top rate of 30.1 percent when federal and state levies are calculated together. Other states enforce similarly heavy combined burdens; in Alaska, Illinois, Maine, and Minnesota, corporations face combined corporate income tax rates at or above 28 percent.
Conversely, six states—Ohio, Nevada, South Dakota, Texas, Washington, and Wyoming—levy no state corporate income tax at all. Corporations in these states face only the federal statutory tax rate of 21 percent, though it is important to note that four of these jurisdictions—Ohio, Nevada, Texas, and Washington—compensate for the lack of an income tax by levying statewide gross receipts taxes.
Calculating the final tax liability is further complicated by the interaction between federal and state tax codes. Corporations are generally permitted to deduct state corporate income tax payments against their federal taxable income. This deduction effectively lowers the corporation’s effective federal income tax rate. For example, a corporation subject to Rhode Island’s corporate income tax may deduct the tax paid at a 7 percent flat rate against the 21 percent federal corporate income tax. This deduction reduces the effective federal rate to approximately 19.53 percent, resulting in a total combined rate of 26.53 percent for the firm.
In a unique twist, a select few states allow corporations to perform the inverse calculation by deducting federal corporate income tax liabilities against a portion of their state corporate income tax obligations. Alabama stands out by allowing full deductibility of federal corporate income tax liability against state tax liability, while Missouri permits a 50 percent deduction of federal corporate income tax liability. These rare provisions further lower the effective corporate income tax rates faced by corporations operating within those specific states.
When factoring in all jurisdictions—including the states that impose no corporate income taxes whatsoever—the average combined state and federal corporate tax rate imposed across the United States sits at 25.5 percent. This figure highlights the balancing act policymakers must perform when evaluating business taxation.
Tax policy experts emphasize that when examining the overall tax burdens on businesses, policymakers and economists must consider both federal and state corporate taxes simultaneously. Corporate taxes are widely regarded by economic analysts as one of the most economically damaging ways for governments to raise revenue. Because capital is mobile, high and complex corporate tax burdens can discourage investment, hamper business expansion, and ultimately slow wage growth for workers.
Consequently, reforming corporate tax structures remains a promising area for states looking to increase their competitive edge and promote broader economic growth. By modernizing tax codes, reducing compliance burdens, and addressing the compounding effects of complex levies, states can foster environments that benefit both operating companies and the workforce they employ.