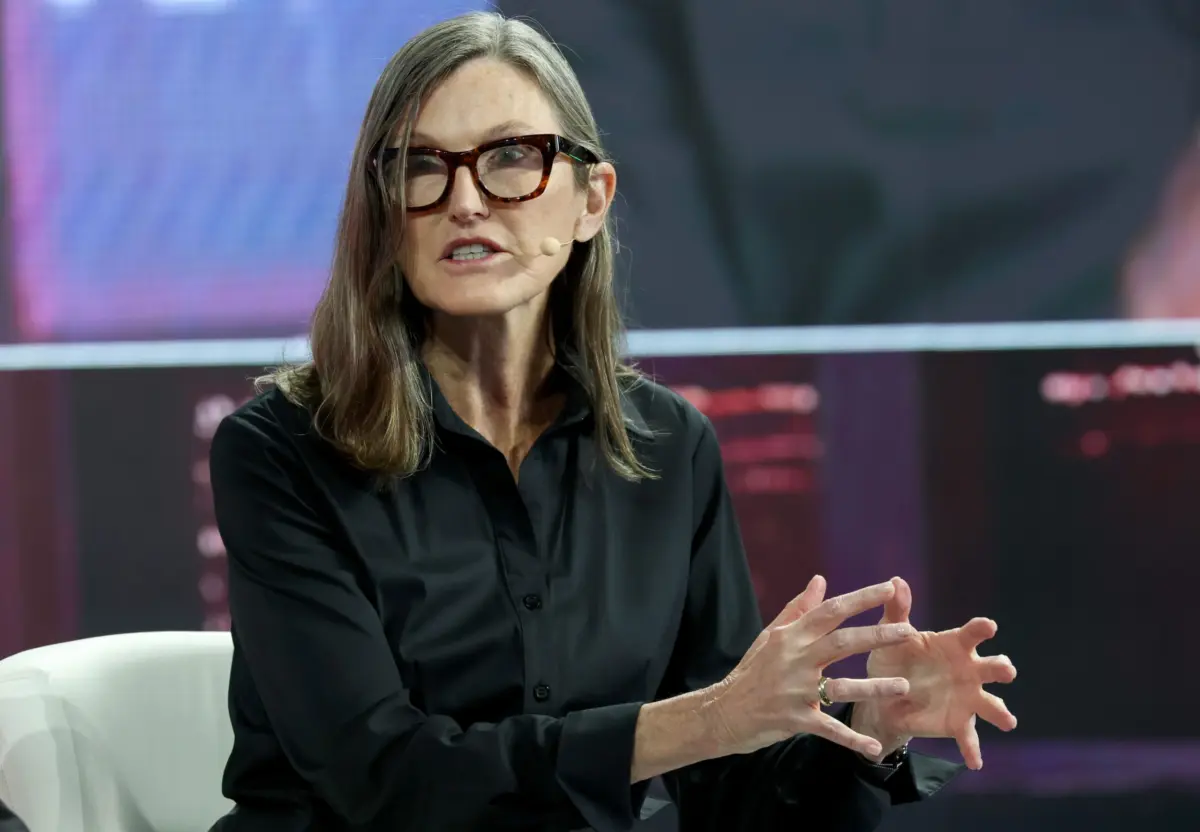
As artificial intelligence systems rapidly evolve from answering simple text prompts to executing complex, real-world tasks, a profound shift is taking place in the global technology and financial landscapes. For years, visionary investors like ARK Invest CEO Cathie Wood urged market participants to “follow the developers” to identify the next wave of technological disruption. Speaking at Robinhood’s Summit in Houston, Wood suggested that the time has come for a new maxim: “follow the agents.”
Wood was referring to autonomous AI agents—advanced software programs capable of acting independently on behalf of human users. Unlike traditional chatbots that merely generate text or retrieve information, these sophisticated agents can make decisions, negotiate terms, and execute workflows across digital ecosystems. This transition from passive advisory tools to active economic participants has triggered an urgent race among investors, legacy financial institutions, and major technology companies. The core objective is to control the underlying financial networks and payment rails that will power machine-driven commerce.
While Wood’s remarks during the panel discussion were relatively brief, they underscored a critical question that is rapidly coming to the forefront of the tech industry: What happens when artificial intelligence stops simply answering people’s questions and starts spending their money?
Historically, tracking software developers has served as a reliable indicator of technological momentum because engineers naturally gravitate toward efficient and scalable tools. In a future where millions or even billions of AI agents independently select software packages, digital services, and network infrastructures, observing their transactional choices could provide unprecedented clarity regarding where market demand is truly heading. However, for these autonomous agents to function as independent economic actors, they must possess secure, frictionless, and universally accepted mechanisms to transfer value.
This operational reality has brought the plumbing of digital finance under intense scrutiny. In a series of analytical posts published last month, Joseph Chalom, co-CEO of SharpLink and the former head of digital assets at BlackRock, warned against allowing a small oligopoly of traditional banks or dominant technology monopolies to monopolize the financial architecture designed for intelligent machines.
“A world full of intelligent agents means nothing if a handful of companies decide where your money can go,” Chalom wrote in the concluding chapter of a three-part series examining the emerging paradigm of agentic finance.
Chalom emphasized that the primary challenge is not merely technical capability—enabling an agent to spend money is relatively straightforward—but rather establishing proper governance, granular user permissions, and competitive neutrality. For instance, a human user might grant an AI agent the explicit authority to spend up to five hundred dollars to book a hotel accommodation without exposing their broader bank account to unlimited access. Furthermore, users must retain the ability to instantly revoke that authority and inspect a comprehensive, immutable audit trail documenting every action the agent performed.
Another critical requirement highlighted by industry experts is portability. Consumers should not be locked into a single proprietary financial ecosystem controlled by one technology conglomerate. Just as mobile phone users can seamlessly switch network carriers while retaining their phone number, individuals should be able to migrate their AI agents, along with their associated financial identities, histories, and permissions, across different providers without friction.
To prevent fragmentation and monopolistic control, Chalom and other market analysts argue that open, decentralized blockchain networks could play a pivotal role. Public blockchains such as Ethereum could serve as a shared, neutral financial settlement layer utilized by diverse agents, independent software applications, and rival enterprises. Instead of every major technology firm constructing isolated, closed-loop payment silos, autonomous agents could route transactions across a common, interoperable network. This would eliminate the need for a single centralized intermediary or commercial bank to extract fees and insert control points into every machine-to-machine transaction.
This perspective imbues Cathie Wood’s advice to “follow the agents” with a deeply financial dimension. If autonomous software agents emerge as primary drivers of economic activity, investors will need to monitor not only which machine learning models and software suites these agents select, but also the specific financial rails and settlement networks they employ to complete transactions.
Institutional giants are already analyzing these macro trends. In a research paper published in September, asset management titan BlackRock explored the profound intersection between artificial intelligence and digital assets. The report asserted that AI agents will inevitably generate entirely new streams of demand for payment infrastructures explicitly engineered for machines rather than humans. For example, an autonomous agent might need to execute micro-transactions instantly—such as paying for a specialized application programming interface call, purchasing raw dataset access from a third-party provider, or renting decentralized cloud computing power—all without pausing to seek manual approval from a human user for every individual line item.
According to BlackRock, stablecoins and programmable blockchain protocols offer a viable framework to manage these high-frequency, automated payments. Stablecoins operate around the clock without traditional banking hours, while decentralized payment protocols enable software applications to route fraction-of-a-cent payments directly to other software programs. As an illustrative example, Coinbase’s x402 payment protocol is specifically designed to facilitate machine-to-machine transactions, allowing automated systems to settle payments for online services, data feeds, and API access instantaneously.
Signs of this convergence are already manifesting across the cryptocurrency sector. Coinbase CEO Brian Armstrong recently noted on social media platform X that xAI’s Grok has emerged as a leading client for agentic traders operating on Coinbase infrastructure, though specific transactional volumes and detailed metrics were not immediately disclosed.
At the same time, the crypto industry will not hold a monopoly over machine-driven commerce. Major fintech heavyweights and tech giants—including Stripe, Visa, Google, and OpenAI—are actively developing proprietary payment solutions designed to empower AI agents to conduct consumer purchases and business transactions. BlackRock’s analysis notes that traditional, legacy payment rails will continue to command a significant share of the market as agentic commerce matures.
This fierce multi-sector competition is precisely what makes Cathie Wood’s directive to “follow the agents” so compelling for market observers and digital asset investors alike. As autonomous software agents transition from theoretical concepts to dominant economic actors in the global marketplace, closely watching where they route their transactions will provide investors with a vital real-world metric. It will reveal whether decentralized stablecoins and public blockchains capture meaningful adoption in the age of artificial intelligence, or whether the financial infrastructure of machine commerce ultimately consolidates within traditional, centralized payment networks.