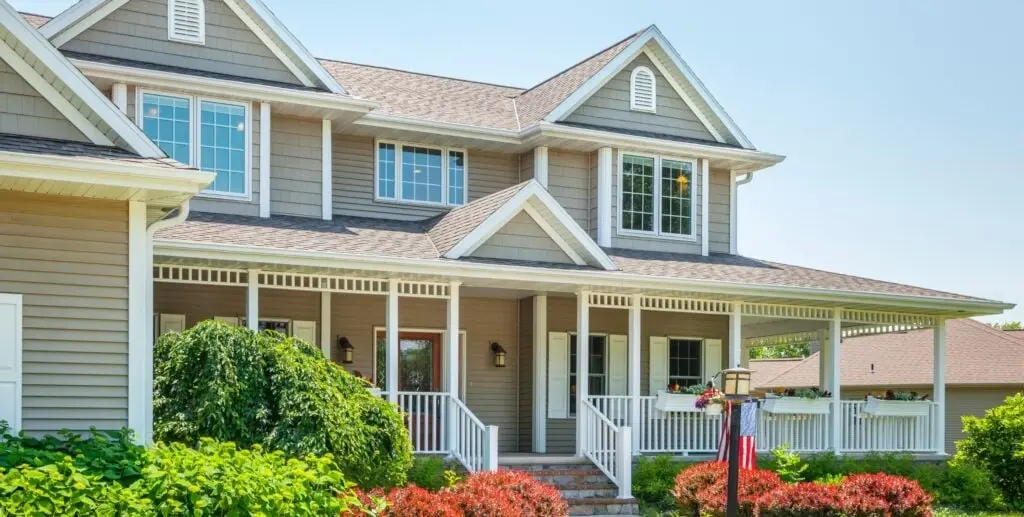
Turnkey real estate investing has long been built on a straightforward yet demanding premise: a provider delivers a rent-ready property, places a tenant, sets up local property management, and hands the buyer a projection of expected rental income. These properties typically fall into two categories—brand-new construction or older homes that have undergone extensive rehabilitation and renovation prior to the sale. Because a significant portion of turnkey real estate investors purchase properties remotely without ever seeing the homes in person, these projected rent figures carry immense weight, serving as the foundational metric in the decision-making process.
In an effort to bring objective transparency to this corner of the market, Rent to Retirement (RTR), a prominent turnkey single-family rental provider, recently decided to put its historical track record to the test. According to the company, approximately 80% of its current inventory consists of newly constructed properties, with the remaining 20% comprising older, renovated homes. To evaluate how these properties perform in the real world over extended periods, RTR opened its comprehensive sales records to an independent third party for a rigorous audit.
The independent reviewers examined 3,090 residential properties sold by RTR between 2017 and 2026. Out of that broader inventory, the reviewers successfully matched 2,763 homes to public resale records to track ownership duration and market appreciation. Additionally, they compared initial projected rental income against actual investor-reported rent on a subset of 740 properties. The findings from this extensive data review provide valuable insights into three central questions that every prospective turnkey investor should consider: how long buyers actually hold their assets, how those properties perform when they are eventually sold, and how closely initial rent projections align with real-world collections.
Most Buyers Hold for the Long Term
When evaluating the staying power of turnkey real estate investments, the properties sold by RTR in 2017 and 2018 offer the longest available ownership record, providing buyers with a seven- to eight-year window to determine whether to retain or divest their assets. Out of the 489 homes sold by the company across those two specific years, a striking 369 properties remain under the ownership of the original buyers, representing an overall retention rate of 75.5%. A closer look at the annual breakdown reveals that among investors who purchased in 2018, 79.2% still own their homes, while 71.1% of the 2017 cohort maintain their original investments.
RTR attributes a substantial portion of this long-term staying power to its operational scale and established market presence. The company coordinates closely with local builders, lenders, and property management firms across its various operational footprints. These established industry relationships help property owners navigate and resolve common real estate hurdles—such as unexpected maintenance repairs, tenant vacancies, and financing challenges—during the early, critical stages of ownership. Furthermore, RTR actively encourages its investor base to work through temporary market setbacks rather than rushing to sell, aligning its entire business model with the principles of long-term real estate accumulation.
Owners Who Held Sold Above Cost
Beyond the high percentage of ongoing ownership, the independent review identified 148 recorded market resales among properties previously sold by RTR. The data revealed that the median home ultimately sold for 1.41 times its original purchase price, with approximately three out of every four resales fetching more than the buyer had initially paid.
The findings indicate a direct correlation between ownership duration and financial outcomes. Investors who held their properties for four years or more realized sale prices above their original purchase price 96% of the time, with median sale prices ranging from 1.57 to 1.86 times their initial investment. Conversely, investors who chose to sell within two years typically broke even at the median level. For those owners who maintained their properties for at least two years, sale prices climbed by a median rate of 8.7% per year. Because this figure reflects raw sale price appreciation alone, an individual investor’s total return would also incorporate the accumulated rental income, financing structures, and ongoing operational expenses associated with each specific property.
While market performance varied for the subset of investors who elected to sell, RTR emphasizes that its buyers of newly constructed homes begin their investment journey from a position of relative strength. Through its extensive network of builder relationships, the company secures institutional-level buyer incentives that reportedly surpass standard concessions available on the open market. These developer incentives grant RTR investors advantageous purchase terms compared to typical retail buyers navigating the open market independently.
Despite these opportunities for profitable resales, the majority of RTR investors choose not to liquidate their portfolios. According to company data, the typical investor maintains ownership for seven to nine years. Many utilize this timeframe to execute strategic financial maneuvers, such as refinancing the property to pull out accumulated equity or executing a tax-deferred 1031 exchange to trade up into larger or more lucrative assets. Both strategies enable investors to remain active in the market while continuing to expand their net worth.
Most Rents Landed Right on Projection
Rental income is arguably the single most critical metric upon which a turnkey real estate buyer relies. To test the accuracy of its forecasting models, the independent reviewers analyzed 740 properties that featured both a documented projected rent and a verified investor-reported rent. The results demonstrated a high degree of accuracy, with the median home renting for the exact amount that RTR had projected.
Across the broader sample, 598 properties—representing 80.8% of the analyzed homes—succeeded in collecting at least 95% of their projected monthly rent. Furthermore, 476 homes, or 64.3%, landed within a narrow 5% margin of the original forecast in either direction. For example, an independent review of an Alabama property purchased for $332,400 revealed an initial rent projection of $2,350 per month, a figure that was matched precisely by the actual rent collected.
While the forecasts proved reliable overall, the data acknowledges that no predictive model is infallible. Properties that fell below 95% of their initial rental projection missed their targets by a median margin of 15%. On a baseline monthly rent of $2,000, that variance translates to a $300 shortfall, underscoring the importance for investors to maintain adequate cash reserves for every rental property in their portfolio to absorb unforeseen income gaps.
Ohio Projections Were the Most Accurate
Projection accuracy was not uniform across all geographies, varying notably by regional market. Ohio, which accounted for the largest segment of RTR’s rent sample with 355 analyzed homes, demonstrated the highest level of forecasting precision, with 94.9% of properties renting at or above 95% of their projected figures. Tennessee and Alabama followed closely behind, recording accuracy rates of 89.5% and 89.1%, respectively.
In contrast, properties located in Florida exhibited softer rental performance compared to other regions included in the review. Just under half of the analyzed Florida homes—specifically 46%—reached the 95% threshold of their initial projections, while the median Florida property achieved 93% of its forecast amount. These regional variations suggest that investors eyeing Florida real estate should incorporate additional financial buffers into their initial pro forma calculations.
Lower-Priced Homes Hit Projection Most Often
Analysis of the portfolio by purchase price revealed a distinct pattern regarding both forecasting accuracy and financial yields. Homes purchased for under $150,000 achieved at least 95% of their projected rent in 97.5% of cases. Meanwhile, properties priced above $350,000 hit that same performance threshold in 51.2% of instances.
In addition to higher projection reliability, lower-priced properties delivered superior gross yields, a metric that calculates annual rental income as a percentage of the initial purchase price. The median gross yield reached 10.8% for properties priced under $150,000, compared to a median gross yield of 7.7% for homes valued above $250,000.
What to Check Before You Buy
The findings of the independent review highlight the importance of careful evaluation when entering the turnkey market. Because a pro forma financial projection is generated as a snapshot on closing day, industry professionals emphasize that buyers must thoroughly scrutinize what these projections include. A comprehensive pro forma should itemize every operating expense, including dedicated allowances for tenant vacancies and capital expenditures for major future repairs. It should also clearly outline existing loan terms, allowing buyers to stress-test how an investment would perform if rental income decreases or unexpected maintenance costs arise.
Prospective investors are advised to request detailed historical track records from turnkey providers, broken down specifically by market and price point, given how significantly those factors influenced performance in RTR’s data set. Beyond reviewing provider metrics, buyers are encouraged to execute standard due diligence protocols, which include commissioning independent property inspections, verifying comparable rental rates with local property managers, reviewing property management agreements, and securing independent quotes for hazard insurance and property taxes.
What This Means for Investors
The comprehensive review of Rent to Retirement’s operational history provides empirical data on the realities of turnkey real estate investing. The findings suggest that success in this asset class rewards investors who approach the market with a long-term strategy. This entails maintaining ownership across multi-year horizons, preserving sufficient cash reserves to manage intermittent vacancies and repairs, and expanding portfolios in a disciplined, gradual manner. Diversifying holdings by acquiring multiple properties rather than relying on a single asset helps spread operational risk and strengthens the long-term viability of a real estate portfolio.