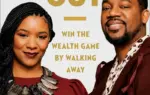
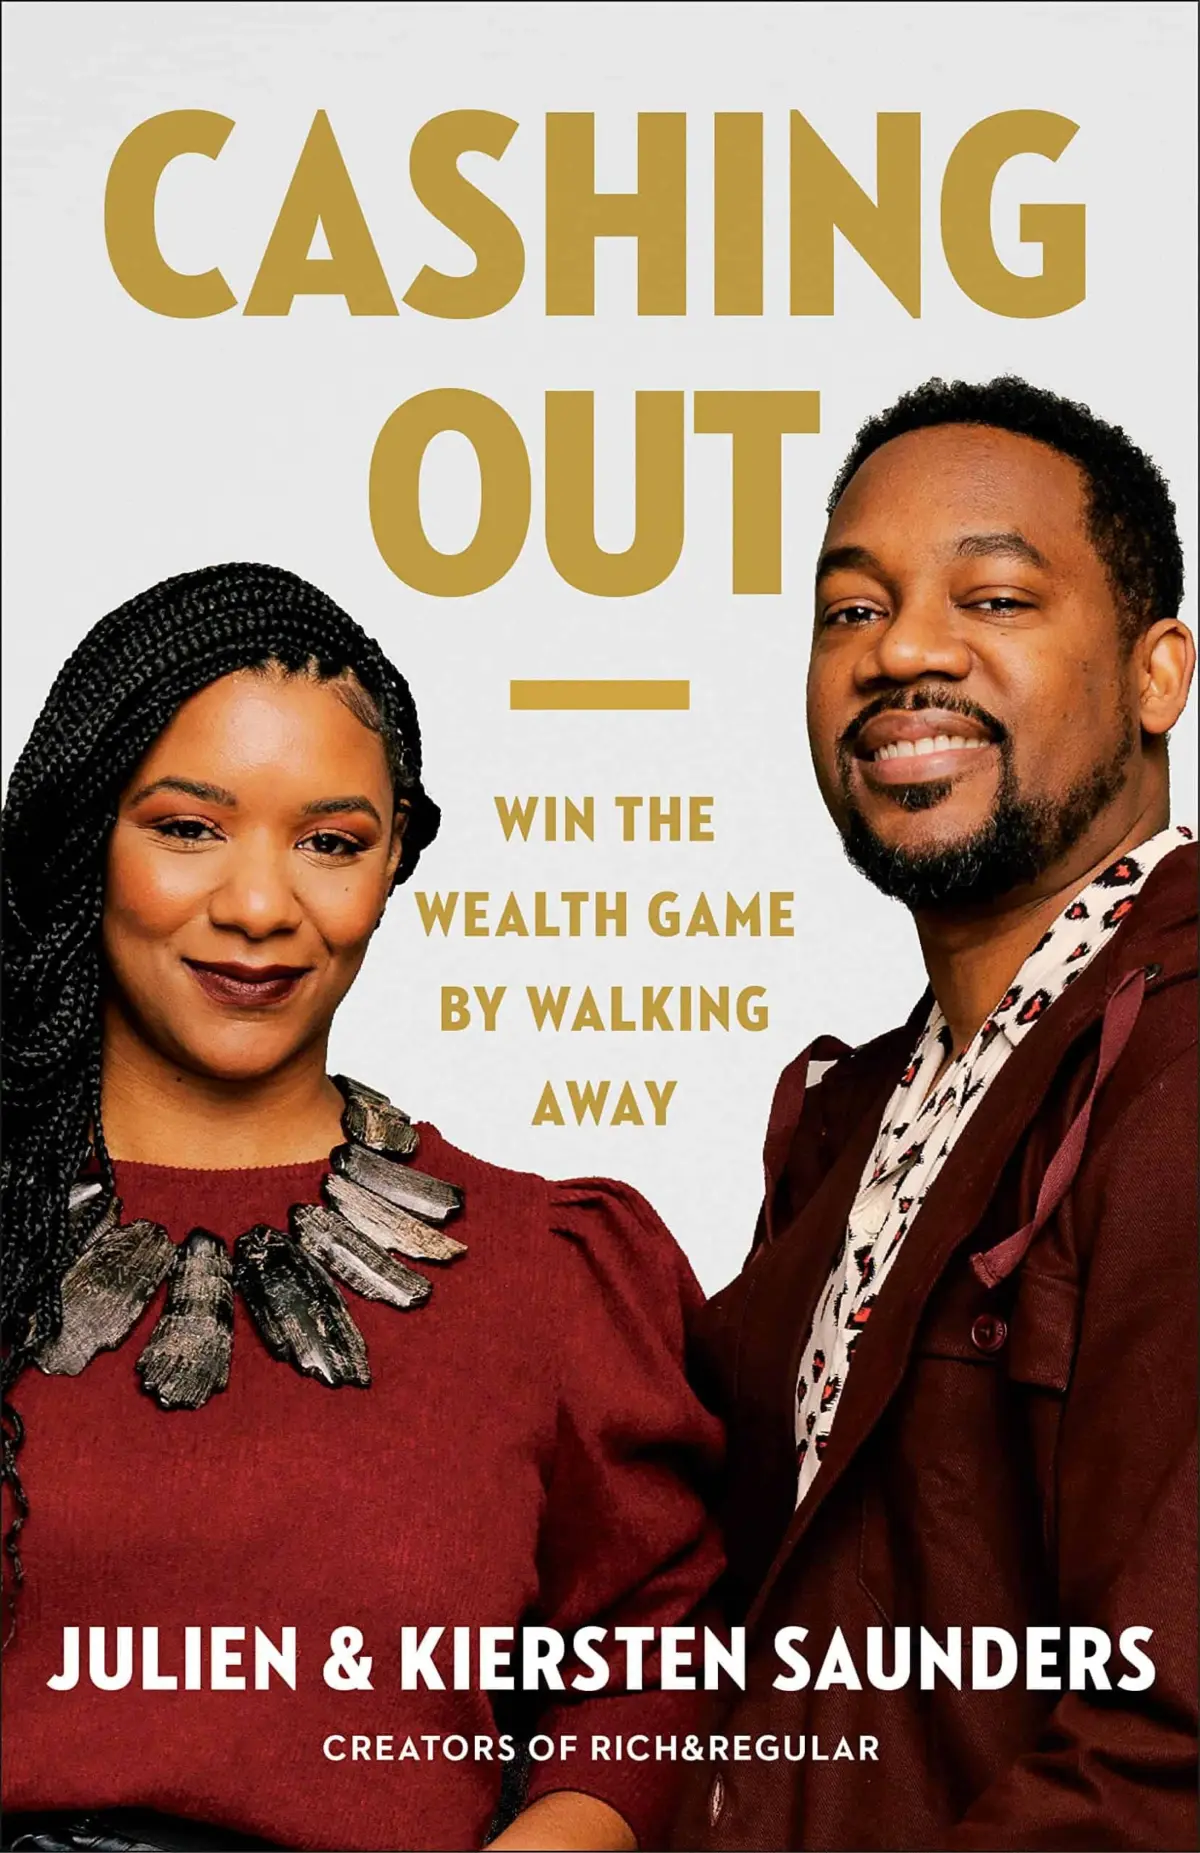
The summer book series on Get Rich Slowly concludes with a vital look into the intersection of personal finance and human relationships, featuring an exclusive excerpt from Cashing Out: Win the Wealth Game by Walking Away. Written by Julien and Kiersten Saunders, the prominent couple behind the rich & Regular blog and YouTube channel, the book addresses a reality that many financial advisors overlook: managing money as a couple is rarely just about math. Instead, it is an emotionally charged choreography that requires profound psychological attunement.
Published by Portfolio/Penguin, Cashing Out challenges traditional notions of how couples approach wealth building, spending, saving, and debt. At the core of the Saunderses’ philosophy is a concept borrowed from Dr. Sue Johnson, a clinical psychologist specializing in emotionally focused therapy. Dr. Johnson posits that when couples argue, the topic itself is rarely the true issue. Rather, partners are engaged in a relational dance, where one person makes a move and the other responds accordingly. The rhythm of this interaction defines the dynamic, and recognizing this pattern is the first step toward true financial harmony.
To understand financial conflict, the authors suggest thinking of emotions as the music behind the dance. Being emotionally attuned means partners can hear the same song or at least acknowledge that multiple perspectives exist. When couples avoid discussing money, they function as participants in a silent disco, where everyone moves independently without hearing the underlying melody. To resolve financial friction, couples must learn to identify the emotional language of their unresolved disagreements, which typically manifest in three distinct areas: spending, saving, and debt.
Name-Calling: Conversations About Spending
Over years of engaging with couples about their finances, Julien and Kiersten Saunders observed that spending habits generate the most frequent friction. Disagreements often feature one partner bewildered by the volume of purchases accumulating in the household, resembling frustrated pet owners seeking help from a behavioral specialist when conventional methods fail.
Inevitably, these conflicts crystallize around tired labels: one partner is cast as the responsible saver, while the other is labeled the irresponsible spender. This dynamic creates a moral hierarchy where the saver represents the virtuous decision-maker and the spender embodies the financial antagonist who requires correction.
The Saunderses argue that this dichotomy is a false construct. Saving and spending are not fixed moral traits, but fluid concepts differentiated only by their time horizons. Spenders allocate funds for the present, while savers set aside capital to spend in the future. For example, saving twenty thousand dollars over a year to purchase a vehicle with cash transitions the buyer from a saver to a spender depending entirely on the timeline in question.
True emotional attunement begins by stripping away these rigid labels and eliminating the concept of villains and heroes. By shifting the conversational paradigm from good versus bad to now versus later, couples can stop assigning restrictive personas to one another. Every purchase is fundamentally an attempt to chase a specific feeling—whether that is security, spontaneity, or pleasure. Once partners recognize that they share the same underlying goal of emotional fulfillment, financial discussions shift from defensive debates to objective, collaborative problem-solving.
Nagging: Conversations About Saving
While spending habits spark direct confrontations, persistent anxiety over saving often leads to nagging, which strains relationships through constant surveillance. Continuous, panicky warnings that a partner should accumulate more wealth erode objectivity and turn everyday conversations into an exhausting routine. When financial reminders blend with unsolicited prompts regarding household chores, the individual receiving the critique often concludes that the underlying grievance is personal rather than financial.
The authors note that saving is simply planning to spend later. Therefore, transforming the tone of these discussions requires focusing on future plans rather than present restrictions. Meaningful conversations about shared aspirations act as a release valve, stabilizing high-pressure situations through anticipation and shared optimism.
Rather than issuing reprimands over minor daily expenses, the Saunderses recommend adopting collaborative framing and "I" statements that establish partnership rather than parental authority. By focusing on shared goals—such as cutting back on minor luxuries to fund a major upcoming purchase—couples can leverage the psychological benefits of anticipation. Incorporating small, themed rewards that reflect future travel destinations or shared milestones can provide necessary distractions and build disciplined habits far more effectively than sheer willpower or nagging.
Blaming: Conversations About Debt
Debt represents another major flashpoint in relationships, often driven by disparities in what each partner brings into the union. One person may carry significantly more financial obligations than the other, giving rise to insecurity, resentment, and deep-seated shame. The person carrying the debt may internalize it as a personal moral failure, while the partner without debt may feel undue pressure or obligation, creating an unsustainable dynamic.
Reflecting on their own early relationship, Kiersten Saunders recalls how shame regarding her debt triggered intense defensiveness, leading her to rely on conflict avoidance strategies rather than addressing the problem head-on. For the couple, overcoming this barrier required letting go of romanticized notions of being rescued, shedding judgment, and abandoning rigid debt-payoff frameworks that treated financial liabilities as moral failings.
Whether couples choose to tackle their debts jointly or manage them independently based on personal preference and legal eligibility, emotional attunement remains essential. Financial coordination requires both individuals to participate actively, ensuring that whatever path they select is supported by mutual understanding and shared responsibility.
"Tell Me More"
To facilitate healthier dialogues, the Saunderses advocate for a simple yet powerful conversational tool: the phrase "tell me more." When partners encounter misunderstandings or require broader context, using this phrase signals curiosity and encourages the other person to share their perspective without fear of immediate judgment.
Harsh language and premature criticism function like a sudden scratch on a record player, abruptly halting the rhythm of the conversation. Conversely, inviting further explanation acts as a gentle nudge that sustains the dialogue. However, the authors caution that this tool must be used with care. When emotions run high and a partner feels genuinely threatened, intimidated, or overwhelmed, pushing for immediate analysis can be counterproductive. In moments of acute distress, patience and the preservation of emotional safety are far more valuable than forcing a difficult conversation before the relationship is ready to resume its rhythm.