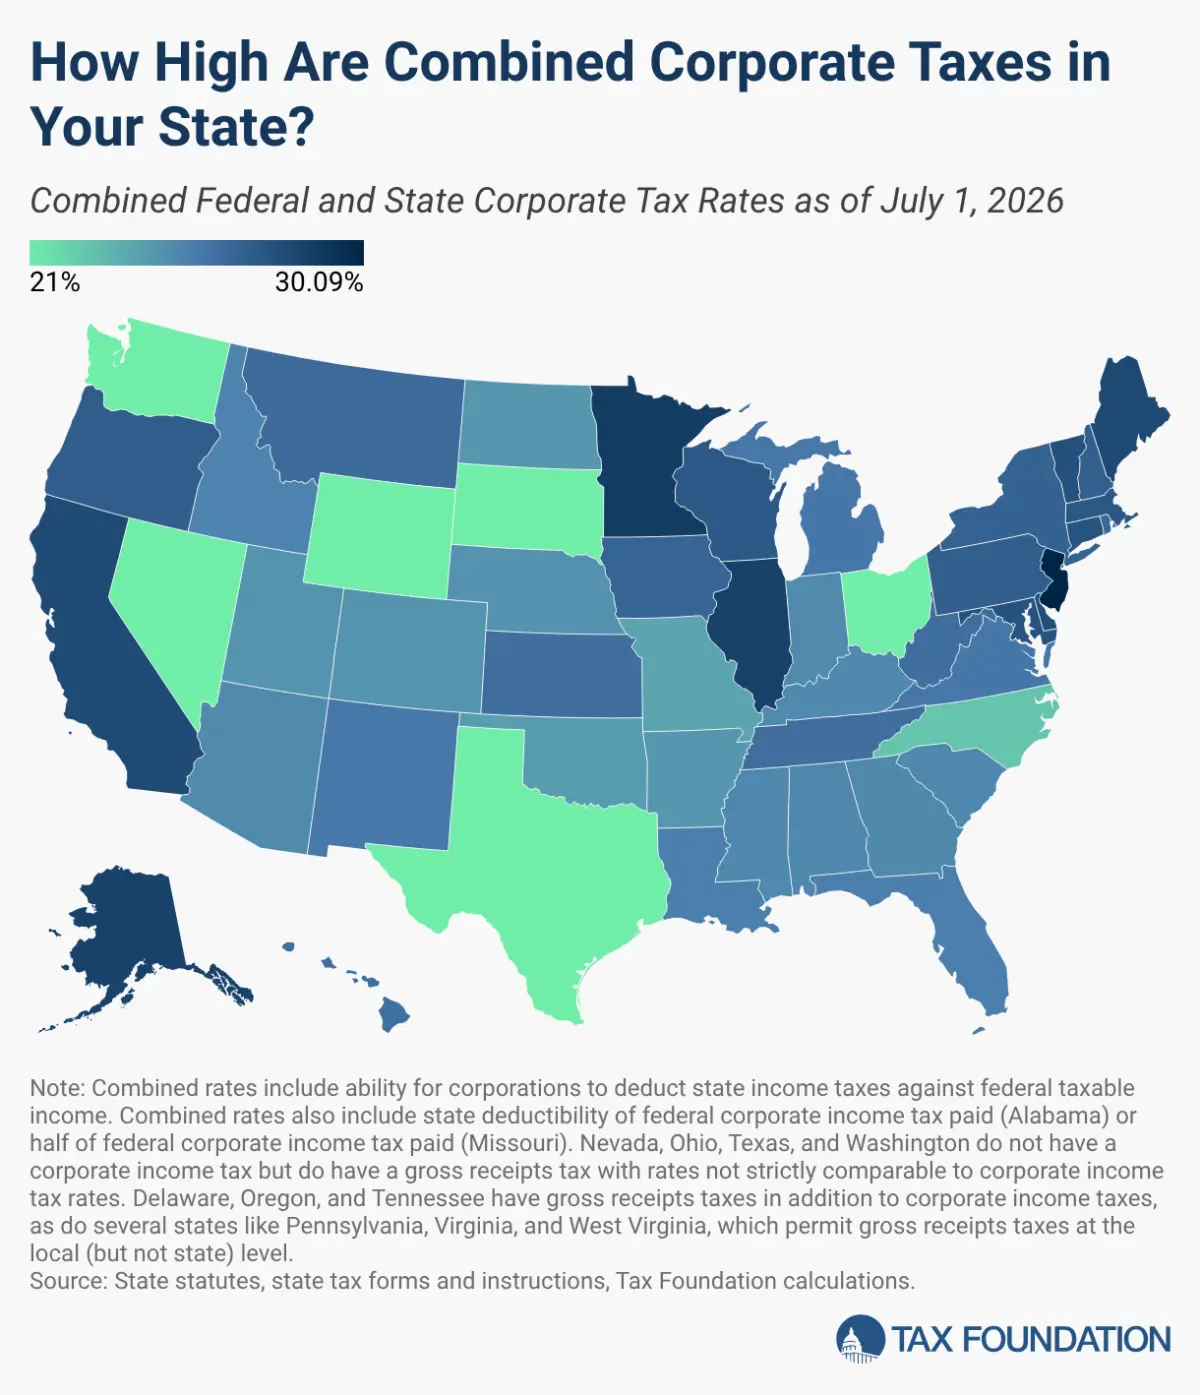
When businesses evaluate their operational costs, tax liabilities invariably stand out as one of the most critical factors influencing expansion, hiring, and long-term strategy in the United States. At the center of this landscape is the federal corporate income tax, which is levied at a flat rate of 21 percent. However, looking solely at federal figures provides an incomplete picture of the actual tax burden American corporations face. Forty-four states and the District of Columbia also levy taxes on corporate income, creating a complex web of overlapping jurisdictions, varying brackets, and alternative tax structures that profoundly affect companies nationwide.
The diversity among state-level corporate income taxes is vast. Top marginal rates vary significantly across the country, ranging from a modest 2.0 percent in North Carolina to a steep 11.5 percent in New Jersey. To administer these taxes, states generally employ one of two structural approaches: thirteen states utilize graduated corporate income tax rates, where the tax percentage increases as a company’s profits grow, while thirty-one states and the District of Columbia levy a flat rate on corporate income.
Adding to the complexity, not all states rely on traditional corporate income taxes. In Nevada, Ohio, Texas, and Washington, corporations are subject to gross receipts taxes rather than corporate income taxes. Unlike traditional corporate income taxes, which apply to net profits after business deductions, gross receipts taxes are assessed on a company’s total gross sales. These levies offer no deductions for fundamental business expenses such as employee compensation, the cost of goods sold, or overhead costs. Furthermore, because gross receipts taxes are applied to transactions at every stage of the production process, they can lead to tax pyramiding, where the same economic value is taxed multiple times before reaching the final consumer.
The landscape becomes even more intricate in states that employ a dual approach. Delaware, Oregon, and Tennessee impose both a tax on corporate income and a separate levy on gross receipts. Meanwhile, Pennsylvania, Virginia, and West Virginia do not levy state-level gross receipts taxes, but they permit local jurisdictions to impose them. At the opposite end of the spectrum, two states—South Dakota and Wyoming—stand out by levying neither a corporate income tax nor a gross receipts tax, leaving businesses operating there subject exclusively to federal taxation.
Because corporations must navigate both federal and state regulations, the combined tax burden can vary dramatically depending on geography. The state with the highest combined corporate income tax rate in the nation is New Jersey, where the interaction between federal and state levies results in an effective top rate of 30.1 percent. Several other states push corporations toward similarly high combined burdens; in Alaska, Illinois, Maine, and Minnesota, corporations face combined corporate income tax rates at or above 28 percent. Conversely, the six states that levy no state corporate income tax—Ohio, Nevada, South Dakota, Texas, Washington, and Wyoming—expose companies only to the federal rate of 21 percent, though businesses in four of those states must account for statewide gross receipts taxes instead.
Understanding the true cost of these taxes requires examining how federal and state systems interact through deductions. Crucially, corporations are generally permitted to deduct state corporate income tax payments against their federal taxable income. This mechanism effectively lowers the federal corporate income tax rate for companies operating in states with income taxes. For instance, a corporation subject to Rhode Island’s 7 percent flat corporate income tax may deduct those state payments against the 21 percent federal corporate income tax. This deduction reduces the effective federal rate to 19.53 percent, resulting in a combined rate of 26.53 percent rather than a simple sum of the two rates.
In a few unique cases, the flow of deductions works in reverse or offers additional relief. Two states allow corporations to deduct federal corporate income tax liabilities against a portion of their state corporate income tax obligations. Alabama provides full deductibility of federal corporate income tax liability against state liability, while Missouri permits a 50 percent deduction. These provisions further lower the effective corporate income tax rates faced by corporations operating within their borders.
When averaging across all fifty states—including those that impose no corporate income taxes at all—the average combined state and federal corporate tax rate in the United States stands at 25.5 percent. This figure underscores the reality that while the federal rate provides a baseline, state-level policies play a decisive role in shaping the financial environment for American businesses.
Tax policy experts emphasize that when examining the overall tax burdens on businesses, policymakers and economists must consider both federal and state corporate taxes simultaneously. Corporate income and gross receipts taxes are widely regarded by economists as some of the most economically damaging ways for governments to raise revenue, as they can discourage capital investment, slow wage growth, and hamper productivity. Consequently, reforming these tax structures remains a promising area for states looking to increase their competitive edge, foster a more dynamic business climate, and promote broader economic growth that benefits both companies and the workers they employ.