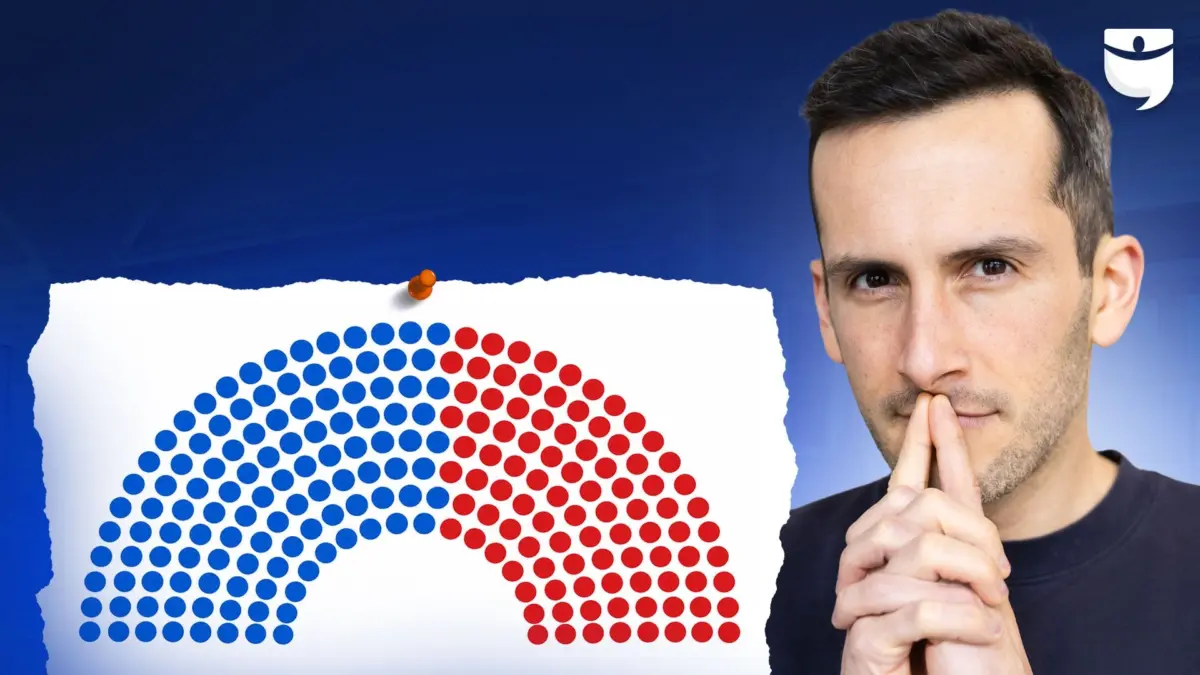
The 2026 midterm elections have officially drawn to a close, offering a clear glimpse into how the political landscape will dictate the trajectory of American real estate over the next two years. With Democrats taking control of both the U.S. House of Representatives and the Senate, the federal government enters a phase of divided governance as the new Congress takes office in January, following two years of full Republican control. Under normal circumstances, severe political partisanship and a divided government would drastically lower the probability of significant legislation clearing Capitol Hill before the next presidential election in 2028. However, housing policy continues to prove an extraordinary exception to this rule.
Housing affordability has escalated into such a pressing socioeconomic challenge across the entire political spectrum that it remains one of the few remaining topics where Democrats and Republicans can realistically forge bipartisan compromises. Dave Meyer, chief investment officer at BiggerPockets, breaks down these developments, explaining how the new legislative lineup, federal housing laws, capital gains considerations, and shifting local property tax dynamics could fundamentally alter home prices, supply, demand, and overall tax burdens for homeowners and investors alike.
The Bipartisan Blueprint: The 21st Century ROAD to Housing Act
To understand where federal housing policy is heading, analysts point to the passage of the 21st Century ROAD to Housing Act, which was signed into law by President Trump on July 11, 2026, after sweeping through the Senate with an 85-5 vote and the House with a 358-32 margin. While federal legislation is rarely a silver bullet for localized housing crises—given that the vast majority of real estate policy occurs at the state and local levels—this landmark bill established a vital precedent. Historically, federal interventions have leaned heavily on the demand side, such as tinkering with mortgage rates or offering buyer subsidies. While these tactics can provide temporary relief, critics argue they often create artificial demand that ultimately pushes home prices higher and exacerbates affordability constraints.
In contrast, the ROAD to Housing Act pivoted decisively toward the supply side, targeting governmental barriers that inhibit the construction of new inventory. Chief among these provisions are expedited environmental reviews for projects utilizing Department of Housing and Urban Development (HUD) funding. Environmental reviews historically consume months or even years depending on the municipality, injecting immense risk and financial overhead into development pipelines. Streamlining this process lowers developer risk and helps more housing projects pencil out financially.
Furthermore, the law encourages pre-approved municipal building designs to radically accelerate the permitting process, allowing builders to bypass costly, time-consuming individual reviews. It also removes federal chassis requirements that previously impeded financing for manufactured and prefabricated homes, aligning government lending rules with traditional housing to help lower construction costs. Additional components of the law include enhanced financing programs for homes under $100,000, adjusted income limits for government housing initiatives, and increased regulatory flexibility for community banks.
While the law took effect over the summer, its operational impacts are slated to roll out progressively through 2027 as Congress addresses necessary appropriations and program funding.
Examining the Institutional Investor Provisions
One of the most heavily publicized elements of the ROAD to Housing Act involved restrictions targeting institutional real estate buyers. Media coverage frequently characterized the measure as a sweeping ban on corporate landlords, but industry experts emphasize that the reality is far more nuanced.
The legislation prohibits corporate entities that already own more than 350 single-family homes from acquiring additional residential properties on the open market, backed by severe penalties reaching up to $1 million per home or triple the purchase price. However, the law contains numerous exemptions. Institutions maintaining portfolios above the threshold are still permitted to purchase properties for renovate-to-rent strategies, engage in lease-to-own or rent-to-own agreements, trade homes directly with other institutional portfolios, and execute build-to-rent developments.
Because institutional investors historically own only a small fraction—roughly two to three percent—of single-family rental properties nationwide, analysts view the provision largely as a targeted policy response rather than an existential shift for the housing market. Retail mom-and-pop investors continue to control the vast majority of the rental market, meaning competition from institutional buyers will persist, albeit under adjusted regulatory boundaries.
Legislative Outlook for the Lame-Duck Session and Beyond
As Washington transitions past the midterms, lawmakers face an immediate lame-duck session before the new Congress is sworn in. With government funding deadlines looming and potential debates over federal spending threatening routine shutdowns, speculation has also turned toward whether lawmakers might pursue a reconciliation bill during the final weeks of the current alignment.
Within these behind-the-scenes discussions, real estate investors are closely monitoring potential adjustments to the tax code, specifically proposals to index capital gains to inflation. Under current rules, taxable capital gains are calculated as the final sale price minus the purchase cost and qualified improvements. Indexing gains to inflation would reduce the taxable portion by stripping away the paper gains driven purely by inflationary pressures over time, potentially cutting tax liabilities significantly for buy-and-hold investors upon asset disposition.
Once the new, divided Congress convenes in January, single-party legislative pushes will largely stall. However, the proven viability of bipartisan cooperation on housing opens the door for new proposals modeled after the Build More Agenda, introduced by the bipartisan Build America Caucus. This coalition of approximately 40 House members, who were instrumental in shaping the ROAD to Housing Act, has outlined several forward-looking concepts aimed at expanding housing supply.
Among these proposals are voluntary "right to build zones," wherein municipalities that streamline zoning and permitting to automatically approve standardized housing receive federal incentive payments for every new home constructed above historical baselines. Another prominent focus is federal backing for secondary mortgages dedicated to Accessory Dwelling Units (ADUs). This mechanism would allow homeowners to finance ADU construction based on future rental income and projected property value without disturbing their existing, low primary mortgage rates—a critical advantage given that traditional lenders often refuse to factor prospective rental income into secondary financing.
Additionally, the Build More Agenda targets escalating construction material costs, which have outpaced general inflation with a 42 percent surge over the past five years, compounded by tariffs that add nearly $11,000 to the cost of a typical single-family build. The proposal calls for targeted tariff relief on residential construction materials and exemptions from "Buy America" rules for affordable housing projects to help alleviate development bottlenecks.
Anticipating the 2028 Tax Bill and Primary Residence Exclusions
Looking further ahead toward 2028, tax provisions enacted in previous legislative packages are scheduled to expire, setting the stage for comprehensive tax negotiations. This future legislative vehicle could potentially incorporate the More Homes on the Market Act, which currently enjoys substantial bipartisan sponsorship across both congressional chambers.
The proposed act addresses the capital gains tax exclusion on primary residences, which has remained fixed at $250,000 for single filers and $500,000 for joint filers since its establishment in 1997. By indexing these exclusion thresholds to inflation, the bill aims to alleviate the tax burden on long-term homeowners—particularly seniors—who possess substantial equity that currently exceeds historical exemptions. With nearly 29 million households holding equity surpassing the current single-filer exclusion, supporters argue the adjustment could help ease the "lock-in effect" keeping aging homeowners from selling and listing properties. While carrying an estimated federal revenue cost of over $46 billion, the provision remains a key focal point for lawmakers navigating future tax reform.
State and Local Property Tax Referendums
While federal policies shape broad market frameworks, housing dynamics ultimately remain localized. Recent state-level ballot measures underscore how regional governments are actively addressing affordability and taxation pressures independent of Washington.
In North Carolina, voters approved a constitutional amendment directing lawmakers to establish statutory caps on local government property tax revenue increases, offering property owners greater predictability against rising tax burdens. Meanwhile, Florida voters cleared a constitutional amendment reducing the annual assessment increase cap for rental properties from 10 percent to 5 percent. Because the cap applies to assessed values rather than local tax rates, local jurisdictions retain some operational flexibility, but the measure signals ongoing state-level efforts to moderate housing costs for tenants and landlords.
As the political dust settles from the 2026 midterms, real estate professionals and property owners are advised to monitor both emerging bipartisan federal frameworks and localized municipal policy shifts that continue to govern day-to-day market conditions.