A new legislative proposal introduced in Washington aims to upend how states handle tax policy for the booming artificial intelligence industry. Senator Bernie Moreno (R-OH) has formally introduced the RECLAIM Act (S. 5689), a measure designed to impose a 100 percent federal tax on any state or local incentive granted to large-scale AI data centers.
The mechanism behind the proposal functions similarly to international minimum tax structures. By design, the bill would effectively "top up" the sales tax on data center servers and microchips in states that currently offer exemptions for those business inputs, imposing an equivalent federal tax matching the exemption amount. Economists and policy analysts anticipate that states would likely respond by implementing the taxes themselves to capture the revenue rather than allowing the federal government to collect it.
Supporters of the measure argue that it closes loopholes utilized by massive technology companies. Senator Moreno emphasized a hardline stance against corporate subsidies in statements accompanying the bill’s release, asserting that taxpayers should not subsidize the infrastructure powering artificial intelligence. Prior to introducing the legislation, the Ohio lawmaker criticized specific local arrangements, including a sales tax exemption granted to a private equity-backed data center project that he characterized as a multi-million-dollar subsidy creating very few permanent jobs.
However, tax policy experts warn that the broad language of the proposed legislation extends far beyond targeted economic development incentives, threatening fundamental principles of sound state taxation and putting pressure on the supply chains required for advanced computing technology.
What Would the Proposed RECLAIM Act Do?
A close reading of the legislative text indicates that the consequences of the RECLAIM Act could reach significantly further than state sales tax exemptions for equipment. As currently drafted, the bill possesses the potential to transform standard corporate income taxes for covered data centers into a levy that resembles a tax on gross receipts.
The proposal defines prohibited state or local incentives broadly. This includes any state or local grant, loan, loan guarantee, cooperative agreement, tax credit, deduction, exclusion, exemption, or abatement. Because the language is so expansive, it could potentially penalize routine business deductions, such as standard operational write-offs for wages and capital depreciation. Unless lawmakers clarify the specific intent and scope of the legislation, standard accounting deductions for everyday business operations could be caught in the crosshairs.
The policy explicitly targets "covered data centers," a category encompassing massive facilities primarily dedicated to artificial intelligence operations and heavy computing workloads. By neutralizing state-level efforts to attract these multi-billion-dollar investments, the bill seeks to eliminate what its sponsors view as unfair advantages for hyperscalers and private equity firms investing in digital infrastructure.
Which States Would Be Topped Up?
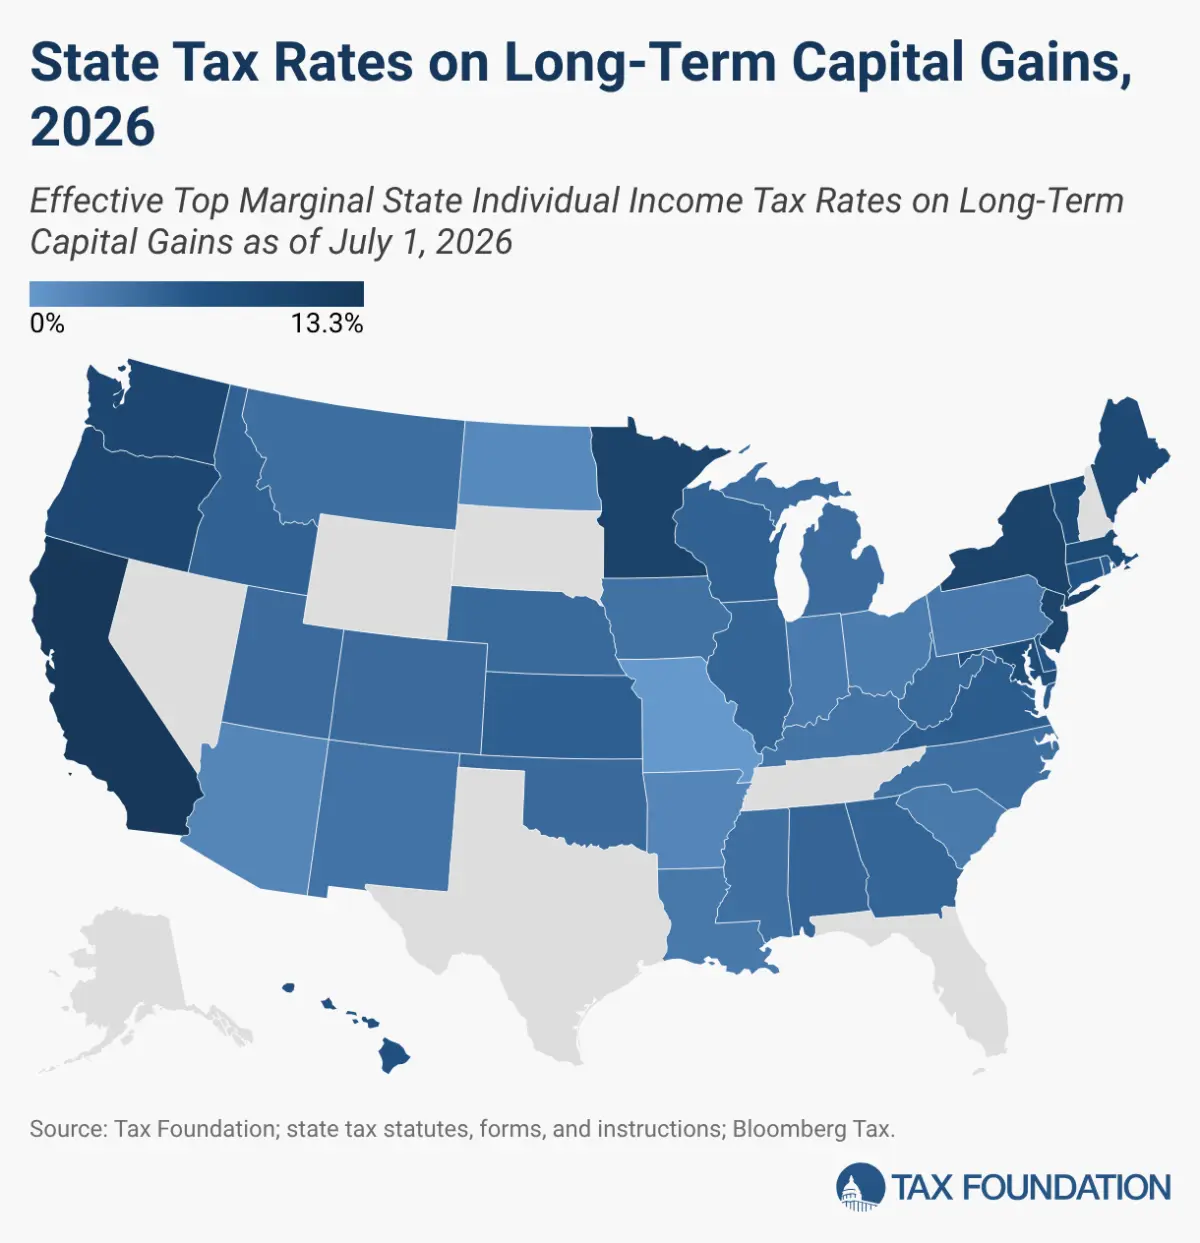
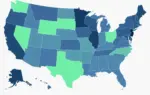
An analytical breakdown of state tax codes indicates that the legislation would create widespread disruption across the country. According to a state-by-state survey conducted for the National Taxpayers Union, at least 31 states feature conditional or discretionary programs that exempt data center equipment from sales taxes. These jurisdictions represent the clearest targets under the proposed framework, as their policies explicitly offer exemptions tailored to the development or commercial operation of large technology facilities.
A small number of states maintain policies structured closer to automatic, by-right exemptions, leaving some legal ambiguity regarding whether federal regulators would classify them strictly as prohibited incentives under the proposed statute.
Meanwhile, 18 jurisdictions would face no immediate federal top-up tax on new projects. States like California and New Jersey, along with roughly a dozen other jurisdictions including the District of Columbia, already tax data center equipment at full standard sales tax rates, meaning there are no existing exemptions for the federal government to offset. Additionally, five states—including Oregon—do not levy a general sales tax at all, shielding them from the direct sales tax provisions of the measure.
Exempting Business Inputs from State Sales Tax Is Not a Subsidy
The central disagreement between the bill’s sponsors and public finance economists revolves around the economic definition of a subsidy. While lawmakers view exemptions for servers and chips as special favors for wealthy corporations, tax experts argue that removing business inputs from a retail sales tax is a foundational element of sound tax design.
A standard retail sales tax is intended to fall strictly on final consumer consumption and to do so only once. When a government levies sales taxes on intermediate business inputs—such as the specialized equipment used in manufacturing or data processing—that tax becomes embedded in the final cost of production. As the product moves through the supply chain, the tax is taxed again at subsequent stages, a phenomenon known as tax pyramiding. This dynamic distorts market neutrality and causes the effective tax burden to vary unpredictably depending on the length and complexity of a given supply chain.
Data center equipment functions as a business input much like assembly machinery in an automobile plant. The vast majority of states recognize this economic reality for traditional manufacturing, with 41 states exempting manufacturing machinery and equipment by right. Data center exemptions often face political backlash simply because they are frequently enacted through specialized economic development statutes rather than general code provisions. This distinction in legal form, however, does not alter the underlying economic principle that business-to-business transactions should remain untaxed to prevent pyramiding.
Tax Foundation analyses routinely evaluate state tax competitiveness by rewarding jurisdictions that exempt business-to-business transactions from sales taxes. By penalizing states that apply sound tax principles to the digital economy, the RECLAIM proposal would actively discourage states from maintaining economically neutral tax codes.
A Sales Tax on Equipment Is a Negative Investment Tax Credit
To understand the economic weight of taxing data center equipment, analysts often look to the concept of a negative investment tax credit. While a traditional investment tax credit reduces the upfront purchase price of capital machinery by a specific percentage, a sales tax increases the acquisition cost by its statutory rate.
Historical economic research demonstrates that uniform investment incentives and taxes do not treat all assets equally. Because short-lived assets must be replaced much more frequently than long-lived infrastructure, they bear the brunt of repetitive taxation every time a company reinvests. This dynamic is particularly pronounced in the technology sector, where advanced microchips and processing units experience rapid obsolescence and must be replaced every few years.
Even a seemingly modest sales tax rate of 7.5 percent translates into a remarkably heavy effective tax burden when it is repeatedly triggered by short replacement cycles. Factoring in real required returns and rapid depreciation rates, a standard sales tax on data center chips can result in a marginal effective tax rate approaching 37 percent on investment returns. By comparison, federal tax provisions, including temporary full expensing rules for equipment investments, generally impose much lower marginal effective tax rates on new capital outlays.
Tax Neutrality and Federalism
The implications of the RECLAIM Act extend beyond immediate sales tax disputes. The measure also addresses property tax abatements and other local concessions, which often represent non-neutral fiscal interventions that economists frequently question. Whether federal intervention is appropriate for addressing localized property tax disputes touches on core debates regarding fiscal federalism.
However, policy analysts stress that state sales tax exemptions for intermediate business inputs are fundamentally different from discretionary corporate giveaways. By conflating sound structural tax policy with targeted subsidies, the proposed legislation risks penalizing states that are simply trying to prevent tax pyramiding in an increasingly digital economy.